

Oil prices are in the middle of their biggest downturn since the military action by the U.S. and Israel began at the start of March, and the benchmark price used for most fuel surcharges is trying to keep up.
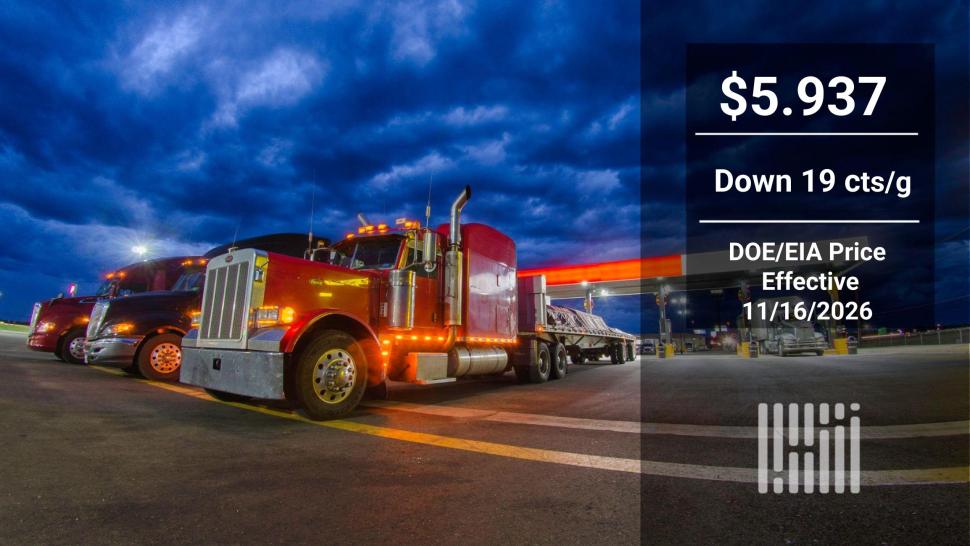
The Department of Energy/Energy Information Administration average retail diesel price fell 19 cents/gallon effective Monday, published Tuesday, to $5.937/gallon. The one-week drop is the largest since a slide of 22.7 cts/g on June 22, and is the third-largest in the up-and-down (mostly up) movement in the volatile diesel market since the start of military action.
It’s also the first time the price has been less than $6/g since September 8. With the decline, the price is now down 59.2 cts/g since it set its all time-high of $6.529/g on September 22.
The DOE/EIA price is now several cents less than the AAA average daily price for retail diesel. That figure price dropped below the $6 level Monday, and on Tuesday stood at $5.9848/g.
The latest DOE/EIA decline follows a rapid drop in the petroleum “complex” in the last several trading days in trading on the CME commodity exchange. Given the lag in retail pricing, barring a reversal, there are more declines to come at the pump.
Ultra low sulfur diesel (ULSD) settled at $4.4216/g on November 2, the first trading day of the month. After an enormous selloff Monday when ULSD settled down 20.47 cts/g at $4.0818/g, the price is down about 34 cts/g in the first half of November.
The decline in diesel futures prices have tracked the slide in crude, with the already enormous margin between diesel and crude–high by historical standards–holding steady on both the comparison between global crude benchmark Brent and first-month ULSD as well as second-month ULSD.
Brent settled at $104.77/barrel on the first trading day of the month. It settled Monday at $92.44/b and hit its October low settlement on October 10 at $91.49/b.
Where is the push coming from?
With most analysts having predicted continued higher prices, the question is what is driving the decline?
The market’s bears got a big boost last week with the release of the November supply/demand report from the International Energy Agency.
The IEA report repeated something it was writing a year ago at this time: there will be lots of crude in the market.
That was the forecast going into 2026, but the ability of that prediction to come true was derailed by war in the Middle East.
However, the IEA is back for 2027. “After a decline of 4.8 million b/d in 2026, oil supply is expected to rebound by 6.6 million b/d, reaching an average of 108.1 mb/d in 2027,” the IEA wrote.
Already, crude supplies are rising, according to the IEA. It said September global supplies increased 3 million b/d and then added 2.3 million b/d in October to 105.4 million b/d. Meanwhile, the IEA sees global demand this year averaging about 104.3 million b/d, far less than supply.
But that surplus is going to be needed to replenish inventories, which the IEA said globally have fallen about 460 million barrels since the beginning of the war.
The rising supplies are as a result of increased flows–mostly of crude, with refined products still restrained–going through the Strait of Hormuz.
Can’t count on Hormuz stability
Amrita Sen, the director of market intelligence at the research firm of Energy Aspects, told CNBC in an interview that her firm’s estimate is that flows out of the Middle East through all routes are up to about 16 to 17 million b/d, compared to a pre-war norm of about 20 million b/d.
But to show the precarious nature of that supply, Sen also said loadings “have started to come off in the last week.”
The most bullish voice in the market for months has been that of Jeffrey Currie, the CEO of Real Macro and the former head of commodities research at Goldman Sachs.
Also in an interview on CNBC, Currie said the Strait is in a position whether “we don’t know if it’s open or closed.”
But there are strong flows emerging now, “and that caps the prompt barrels, but it doesn’t make the next one any cheaper. So you’re kind of stuck in this limbo land at about $95 (per barrel for crude).”
The uncertainty means that the market lacks “any ability to escape to the upside or any ability to really drop much lower,” Currie said.
Without a long-term resolution of the situation in the Strait of Hormuz, Currie said, “it’s very unclear how we’re going to get a resolution here.”
More articles by John Kingston
Amazon-focused bill likely to pass in NYC but only after changes
Amazon workers’ union gets a contract, but it’s in Canada
Transportation committee in House set for overhaul post-election