




J.B. Hunt Transport Services’ third quarter slightly surpassed analysts’ lowered expectations following the company’s earnings warning issued in September.
J.B. Hunt (NASDAQ: JBHT) reported third-quarter revenue of $3.68 billion Thursday after the market closed. The result was ahead of a $3.59 billion consensus estimate. Earnings per share of $1.82 were 1 cent higher than analysts’ revised expectations. (A higher tax rate was a 4-cent EPS headwind in the quarter, partially offset by a 2-cent decline in net interest expense.)
Click for full report: “J.B. Hunt experiences growing pains in Q3”
The result was slightly better than its September update, calling for a 5% to 10% sequential decline in EPS, implying $1.77 at the midpoint of the range. At the time, the company flagged near-term cost pressures—a sharp runup in diesel prices ($10 million), driver-related costs ($25 million) and elevated cargo claims ($10 million)—as headwinds. The actual impact in the quarter was over $50 million.
The third quarter marked a fifth straight quarter of year-over-year improvement in operating income and EPS. The company’s earnings turnaround started in the 2025 third quarter, well ahead of peers.
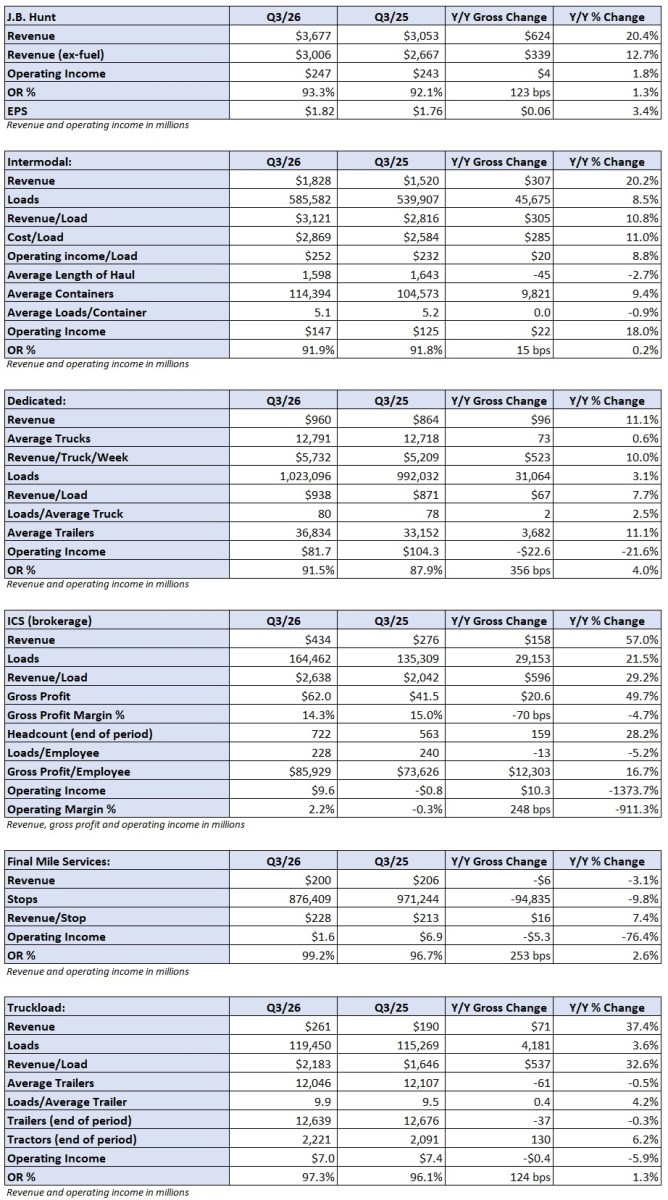
Intermodal revenue increased 20% y/y to $1.83 billion as loads were up 8% and revenue per load increased 11%. Higher fuel prices pushed revenue higher in the period. Excluding fuel, revenue per load was up 2% y/y. Volumes increased 18% y/y in the East and 1% on transcontinental lanes. A 3% decline in length of haul, due to a mix shift to the East, was a modest headwind to revenue per load.
The unit booked a 91.9% operating ratio (inverse of operating margin), which was 15 basis points worse y/y. Higher costs (driver personnel, equipment and employee benefits) were a drag in the quarter.
The dedicated OR deteriorated 360 bps y/y to 91.5%. Revenue was up 11% y/y, almost entirely due to higher revenue per truck per week (inclusive of fuel). Revenue per truck was up just 3% excluding fuel. Average trailers in service increased 11% even though load counts grew just 3%. Higher driver costs, group medical claims, insurance premiums and new account startup costs were among the culprits.
Click for full report: “J.B. Hunt experiences growing pains in Q3”
The brokerage unit booked a second straight operating profit after 13 quarters in the red.
The company’s asset-light truckload unit swung to a $7-million operating profit after a modest second-quarter loss.
Shares of JBHT were down 2.4% in after-hours trading on Thursday. The stock fell 14% from its mid-September earnings update to the Thursday close.
J.B. Hunt will host a call at 5 p.m. EDT on Thursday to discuss third-quarter results.
Why it matters? J.B. Hunt’s quarterly results serve as a bellwether for the intermodal, trucking and logistics industries. The company’s third quarter was a modest slowdown after four quarters of strong recovery. However, some of the incremental costs that plagued the period were likely transitory in nature.
