




Heavier shipments are driving higher tonnage and revenue per bill at ArcBest’s less-than-truckload unit. Freight lost to a once-depressed truckload market is returning alongside an improved manufacturing complex. The changing freight mix helped the company beat third-quarter expectations on Wednesday.
The Institute for Supply Management’s Manufacturing PMI remained in expansion territory for a 10th consecutive month in October. The 55.5 reading was 100 basis points above expectations and the September mark. (A reading above 50 signals expansion, while one below 50 indicates contraction.)
ArcBest (NASDAQ: ARCB) reported adjusted earnings per share of $2.62 on Wednesday before the market opened. The result was 80% higher year over year and 11 cents better than the consensus estimate. (The adjusted number excluded restructuring, technology and other nonrecurring costs.)
Consolidated revenue was up 15% y/y to $1.21 billion, in line with consensus.
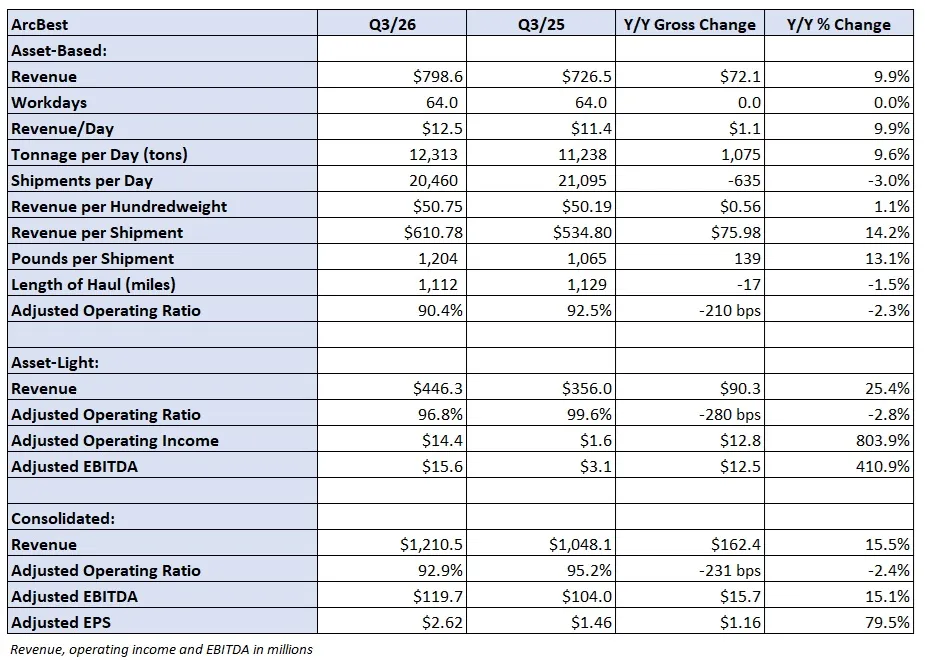
LTL: Q3 by the numbers
The company’s asset-based unit, which includes LTL subsidiary ABF Freight, reported revenue of $799 million, a 10% y/y increase. Tonnage was up 10% y/y as shipments declined 3% and weight per shipment jumped 13%. On a y/y comparison, tonnage increased 8.1% in July, 9.1% in August and 11.6% in September.
Revenue per hundredweight was 1% higher y/y (inclusive of fuel surcharges) and revenue per shipment was 14% higher, with both metrics being impacted by the higher shipment weights. Yield (ex-fuel) was down by a low-single-digit percentage during the period, but the increase in shipment weights along with a 2% decline in length of haul were drags on the metric.
Contractual rate increases averaged 5.1% in the period (up 9.6% on a two-year-stacked comp). ArcBest implemented a 5.9% general rate increase for LTL services in both of its business units in June.
A 90.4% adjusted operating ratio (inverse of operating margin) was 210 bps better y/y. The result was 40 bps better than the second quarter and management’s outlook for no material sequential change.
ArcBest said it reduced its base liability insurance premiums while maintaining coverage limits during a recent renewal. However, it said it has retained higher risk on one of its excess insurance layers, but that coverage has only been touched twice over the past 25 years.
The period also had the impact from an annual union wage increase.
Q4 asset-based outlook
Revenue per day was up 20% y/y in October as tonnage increased 15% and yield increased 4%. (Shipments were up 1% with revenue per shipment up 18%). Yield (ex-fuel) was again off by a low-single-digit percentage y/y, largely due to a 14% increase in weight per shipment. It noted that weight per shipment growth will begin to moderate as the prior-year comparisons get tougher. It will continue to lean on its dynamic quote pool, which matches available network capacity to available transactional shipments each day.
The unit’s OR normally deteriorates by 180 bps from the third to the fourth quarter, but management expects just 50 to 150 bps of erosion this year. The implied 91.4% OR guide (at the midpoint of the range) would be 480 bps better y/y. It said 2027 will likely be another positive step on its path to achieve its 2028 financial targets.
Asset-light beats raised expectations
The company’s asset-light segment, which includes truck brokerage, beat raised expectations. Adjusted operating income of $14.4 million in the third quarter was ahead of the revised guidance ($10 million to $12 million) management provided in its August update. (The initial guide for the unit was $6 million to $8 million.)
Revenue of $446 million was 25% higher y/y as shipments increased 1% and revenue per shipment jumped 24% (including fuel). Purchased transportation expense (as a percentage of revenue) was up 10 bps y/y to 85%. Shipments per person per day increased 8% and selling, general and administrative expenses declined 2%.
The trends carried through October, with revenue per day 27% higher y/y (shipments up 8%, yield up 18%). Adjusted operating income is expected to range from $7 million to $10 million in the fourth quarter.
The company will host a call at 9 a.m. EST on Wednesday to discuss third-quarter results.
Why it matters? ArcBest is one of a few publicly traded LTL companies. Its quarterly results provide insight into a subsegment of trucking where few public datasets exist.
