

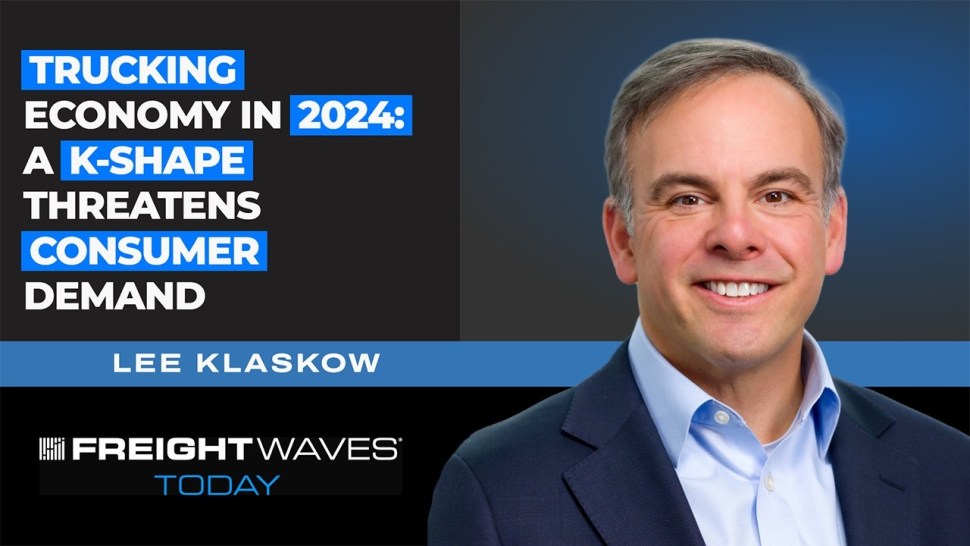
The trucking economy is navigating a unique ‘K-shaped’ recovery, with industrial strength diverging from struggling consumer demand. Bloomberg Intelligence analyst Lee Klaskow unpacks why this trend, coupled with tight capacity, could lead to a prolonged, less volatile rate cycle extending into 2027. We discuss the unexpected tailwinds from AI and data centers, the impact of federal mandates on driver capacity, and what it all means for freight demand and brokerage consolidation.
Truckload contract rates could climb into the high single digits in 2025 — and touch low double digits if consumer demand holds — according to Lee Klaskow, senior analyst for transportation and logistics at Bloomberg Intelligence. The forecast hinges not on a surge in freight volumes but on a structural tightening of truck supply that Klaskow expects to sustain rate momentum through at least 2027.
“We think that we can get on the contractual side, you know, on average rates at the high single digits to low double-digit level in terms of growth on top of what we’ve had this year in 2026, which has been pretty robust growth as well,” said Klaskow. The analyst added that drivers pushed out of the market by federal mandates are unlikely to return as quickly as in prior cycles, reducing the capacity whipsaw that has historically cut rate rallies short.
The key risk to that outlook is the consumer. Klaskow pointed to a K-shaped economy in which higher fuel and food costs are squeezing lower-income households even as upper-income consumers remain largely insulated. That divergence could dampen freight volumes even while nominal spending holds up.
“If you’re spending more money at the pump and more money at the grocery store, you’re spending less money on stuff. And everyone on this broadcast cares about the delivery and the movement of stuff,” Klaskow said.
On the industrial side, Klaskow cited several positive signals: the ISM manufacturing index has been in expansion territory every month this year, and the AI and data center construction boom has been a notable tailwind for the flatbed market. He cautioned, however, that uncertainty around U.S. trade policy is slowing cross-border investment, particularly in Mexico, as companies wait for clarity on tariffs before committing capital.
Klaskow also weighed in on brokerage consolidation, arguing that the Supreme Court’s Montgomery ruling will accelerate mergers by forcing brokers to build the scale needed to absorb rising insurance costs and legal liability. He said synergies from the RXO and C.H. Robinson transaction — which he described as the largest deal in freight brokerage history — could exceed the $300 million target the companies have outlined. Larger, well-capitalized brokers will increasingly direct freight toward carriers with rigorous driver-vetting processes, he said, favoring publicly traded fleets over small owner-operators.
Looking further out, Klaskow stopped short of calling the current environment a supercycle but said the industry should expect longer, more stable rate cycles rather than the sharp 18-month spikes and collapses of the past. That stability, he argued, benefits shippers as well as carriers by making capacity more reliable and giving fleets the margin to reinvest in their businesses rather than cut corners on safety.
- Lee Klaskow forecasts high single-digit to low double-digit truckload contract rate growth in 2025-2026, driven by structural capacity constraints rather than demand strength.
- A K-shaped economy poses the chief downside risk, with lower-income consumers spending more on fuel and food and less on goods that move by truck.
- The Montgomery Supreme Court ruling is expected to accelerate freight brokerage consolidation; RXO/C.H. Robinson synergies could surpass the $300 million target, Klaskow said.
This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.