

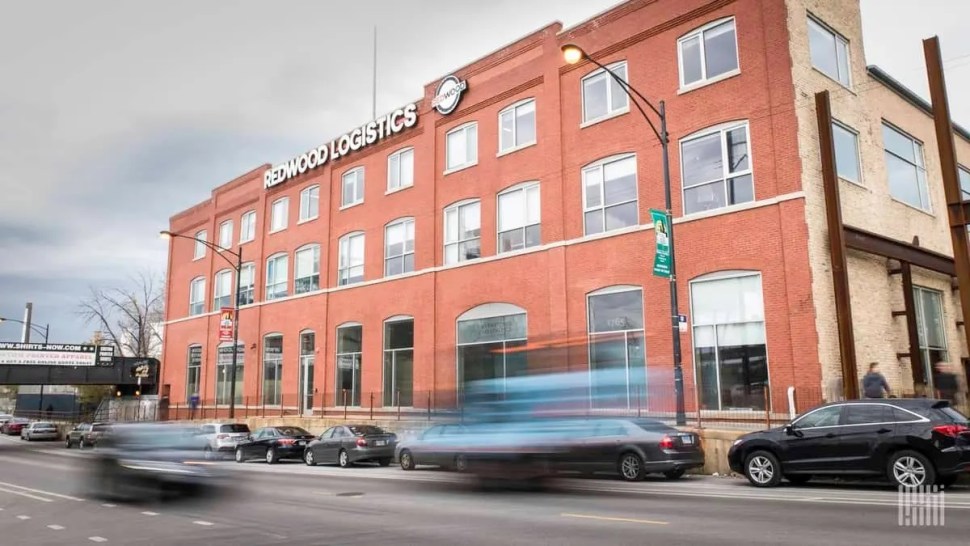
Redwood Logistics is telling shippers to slow down any 4PL selection that shows one of nine warning signs, starting with managed transportation rebranded as a 4PL. The checklist anchors the State of 4PL 2027 report the Chicago-based company released Nov. 11, a 43-page case for what it calls an open 4PL.
The report arrives nearly a year after Gartner’s first Magic Quadrant for fourth-party logistics named Redwood a Visionary, as shippers struggle to get a return on technology they already own. Redwood argues fragmented provider networks are the reason, and that AI makes the problem more expensive.
Redwood frames the fix as a choice about who adapts to whom.
“Every 4PL relationship embeds a fundamental architectural choice: either the provider adapts to the shipper’s ecosystem, or the shipper is forced to adapt to the provider’s closed stack,” said Mike Reed, Redwood’s chief product officer, in the release.
That gap shows up in PwC’s 2026 Digital Trends in Operations Survey of 767 U.S. operations and supply chain leaders, where 89% gave at least one reason their tech investments haven’t fully delivered the expected results, with integration complexity at the top of the list. The 2025 edition put the figure at 92%, the number Redwood cites in its release.
Nine warning signs for 4PL buyers
The list covers managed transportation rebranded as 4PL, visibility without resolution, closed technology or provider requirements, savings guarantees based primarily on procurement, undefined AI claims, heavy dependence on manual coordination, no dedicated continuous-engineering resources or measurable improvement backlog, ambiguous decision rights, and no credible benefit-measurement methodology.
The report adds two tests adapted from Better Supply Chains’ 4PL NExus checklist. First, shippers should ask what share of a provider’s exceptions are resolved by system-executed actions and how many hours pass between a disruption and the provider’s executed fix.
“A provider that cannot answer is describing visibility, not execution,” the report says.
Second, shippers should check whether their current provider is paid on a cost-plus, transactional basis or shares financial risk through an outcome-based agreement.
“The most useful questions a shipper can ask an orchestration partner are the ones a provider cannot answer with a slide,” said Erin Breen, Redwood’s chief growth officer, in the release.
What separates a 4PL from a 3PL
Gartner defines a 4PL as a provider that engages in “the design, build, implementation and ongoing orchestration” of all or part of a logistics network, according to the report. A 3PL runs a defined function such as transportation, warehousing, or customs. A 4PL governs the providers and systems around it.
Redwood splits that category in two. In what it calls a closed 4PL, the shipper standardizes on the provider’s TMS, a fixed carrier set, and a bundled service scope. In an open 4PL, the provider connects to the systems the shipper already runs and picks carriers and tools for each job, including ones that compete with its own offerings. Redwood moved to its modern 4PL positioning after Gartner analysts rejected the company’s original platform label.
Redwood’s five-level maturity model
The report’s five-level maturity model runs from fragmented logistics through managed execution, a connected control tower, and continuous orchestration to an adaptive supply chain. Redwood places most North American shippers at Level 2 or Level 3.
The climb to Level 4 is the steepest, according to the report, because three things have to be true: the provider holds authority to act, the network runs a closed loop from sensing a problem to learning from the fix, and engineering becomes a standing function. The report also says a focused midmarket shipper can operate at Level 2 for years. At Level 1, it says, agentic AI automates the fragmentation.
“Deploying advanced technology or agentic AI into a fragmented network simply automates the chaos,” said Eric Rempel, Redwood’s chief innovation officer, in the release. “Our research found that only 13% of shippers deploying AI see quantifiable results, because unintegrated data and fragmented tools act as instant innovation blockers.”
That figure comes from Redwood’s AI in Logistics report, released in May and drawn from the company’s Customer Advisory Board. The May report described the figure as applying to companies actively deploying AI. Redwood did not disclose how many companies responded. Rempel warned at a FreightWaves event in July that supply chain AI is nearing the Trough of Disillusionment.
Switching costs and RedwoodConnect
Integration debt keeps shippers with providers past the point where the relationship works, the report says, because carrier relationships, system integrations, data history, and team workflows all tangle with the incumbent.
Redwood’s answer is RedwoodConnect, an integration platform the company says links to more than 150 products and platforms. In a typical engagement, it connects 3.5 systems per client, with 85% of connections running over API, 10% over EDI, and 5% still manual. The company added Cincinnati-based managed transportation provider Stridas in March, a week after buying Laredo, Texas, customs broker EELCO, and is connecting Stridas to that platform.
The report cites TileBar, a tile and bath design company with nine showrooms, as one result. Redwood kept many of its incumbent carriers, added two experienced in residential freight, and remapped its LTL pool distribution network, including new pool points for an expansion into Arizona. The report puts the combined procurement and optimization savings at more than $2 million.
The trade-offs in an open model
But the report concedes the model’s cost. Openness “swaps the shipper’s lock-in risk for a heavier governance and integration burden on the provider,” it says. It also says none of Redwood’s design choices is unique to the company in principle. And the Level 2 or 3 placement is Redwood’s own assessment, which the report does not tie to survey data.
Among its 10 predictions through 2031, the report says neutrality will become a leading criterion in 4PL selection, with neutrality and portability clauses in contracts as the early indicator.
“Optionality given up in year one is extraordinarily expensive to buy back in year four,” Breen said.
Why it matters: Shippers narrowing their roster of logistics providers can use the report’s tests to check a 4PL’s execution and exit terms before signing, when leaving costs the least. The signal to watch is whether neutrality and portability clauses start showing up in new 4PL contracts.