

RXO remains a publicly-traded company as it prepares to be acquired by C.H. Robinson, posting its earnings Thursday that showed mostly positive numbers in all key categories.
Given the pending deal with C.H. Robinson, RXO (NYSE: RXO) did not hold an earnings call with analysts. The summary slides that also accompany earnings were not released either.
On the growth side, the company’s revenue was $1.9 billion in the third quarter, compared to $1.4 billion a year ago. Revenue was $1.8 billion in the second quarter.
One key metric that was slightly negative was company-wide gross margin at 14.6%, compared to 16.5% a year ago. However, the third quarter performance was improved on the 13.9% margin in the second quarter.
Adjusted EBITDA numbers were improved. The $51 million recorded in the third quarter came with a 2.7% EBITDA margin, up from 2.3% a year ago when EBITDA was $32 million. The EBITDA margin in the second quarter also was 2.3%.
RXO’s EBITDA of $51 million exceeded the forecast of $35 million to $45 million issued by RXO in its second quarter earnings. “We exceeded the high end of our third-quarter profit outlook, demonstrating the momentum we’re building across RXO,” RXO CEO Drew Wilkerson said in the company’s prepared statement releasing earnings.
One of the more positive figures in the earnings was the fact that RXO made money for the second consecutive quarter. RXO had adjusted net income of 2 cents per share in the third quarter after a second quarter net income of 6 cents per share. Profitability at RXO has been spotty for several years, with some positive net income quarters reported but more frequently showing red ink.
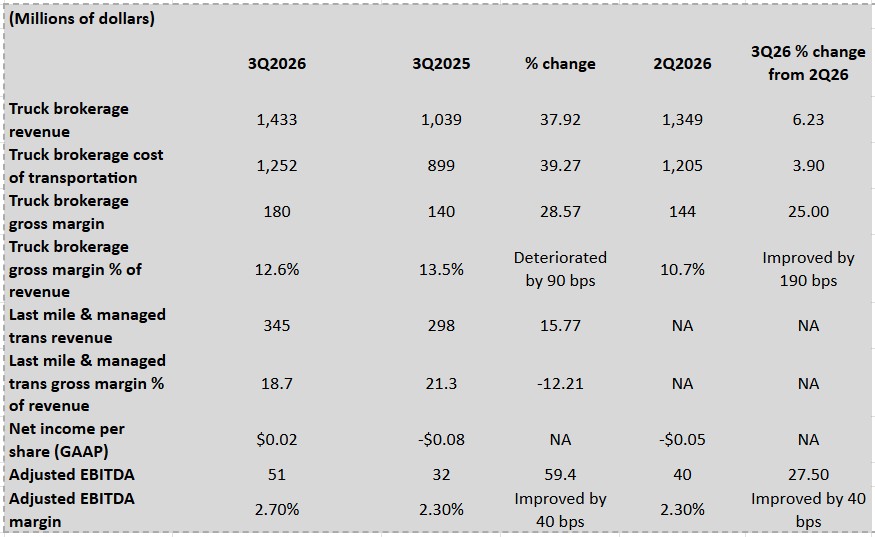
Brokerage volume for the company–the specifics of which are not disclosed by RXO–was up 2% from a year ago. RXO also said truckload volume increased all three months of the quarter.
The mix at RXO’s truckload segment shifted heavily toward the spot market in the quarter. It accounted for 51% of volume, up from 59% a year ago and 42% sequentially.
“This helped drive the largest sequential gross profit per load growth rate in more than four years,” the company’s prepared statement said.
LTL volume was up 2% from a year ago, RXO said. The company’s Last Mile segment–which C.H. Robinson (NASDAQ: CHRW) touted as an attractive part of the RXO business that would strengthen the acquiring company–recorded a 5% increase in stops compared to a year ago.
Jacobs, RXO’s creator, backs its acquisition by C.H. Robinson
Wall Street analysts positive on C.H. Robinson deal; S&P more cautious
RXO, post-Montgomery, sees benefit in its insurance, vetting