Spot rates above $3/mile in 46 of 100 lanes
Carriers are rejecting as much freight now than at any point in the past three years. Spot rates poised to break $3/mile on a national level.
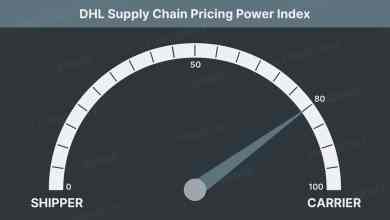
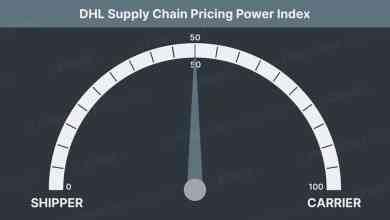
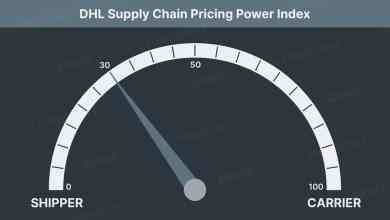
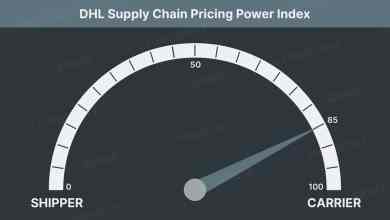
The FreightWaves Pricing Power Index uses analytics and data from FreightWaves’ SONAR platform to analyze the market and estimate the negotiating power for rates between shippers and carriers based on eight key market indicators.
Weekly updates can be found below.
Carriers are rejecting as much freight now than at any point in the past three years. Spot rates poised to break $3/mile on a national level.
Accepted freight tenders are running up 18% year-over-year. Carriers are rejecting 1 in 4 contracted tenders and driving rates up. National spot rates above $2.75/mi. and trending higher.
Spot rates out of LA and Dallas are remarkably high and the tight capacity in those markets is driving the freight cycle.
Buckle up, folks, this should be good. Volumes are gushing and rates pushing higher.
The carriers did not lose ground this week, but rather further solidified their dominant pricing position. Volumes remain well above 2018 and 2019, running in the +20% to 25% range. The elevated volumes are giving carriers options in the market and they are exercising those options at a high clip.
There is no change in the Pricing Power Index this week despite a continuation of the trends we’ve seen over the past few weeks: astounding volumes, carriers rejecting contracted freight at a high clip and rates continuing to trudge upward.
Carrier momentum continues.
Carriers continue their power grab this week adding 10 points and hitting another new series high. Volumes remain in the stratosphere, and carriers are rejecting contracted freight at levels unseen since the summer of 2018.
Carriers are inteh strongest position in the DHL Supply Chain Pricing Power Index’s 10 month history. Rates have pushed higher in recent weeks as carriers reject more freight than anytime in 2019 and volumes remain elevated.
The Independence Day holiday disrupted both our OTVI and OTRI this week. Volumes are poised to bounce back and remain elevated after the moving average distortion is over.
This week’s DHL Supply Chain Pricing Power Index: 55 (Carriers) Last week’s DHL Supply Chain Pricing Power Index: 50 (Balanced) Three-month DHL Supply Chain Pricing Power Index Outlook: 60 (Carriers) The DHL Supply Chain Pricing Power Index uses the analytics and data contained in FreightWaves SONAR to analyze the market and estimate the negotiating power […]
The carriers gained significant pricing power this week. Volumes continue to burst from the seams and tender rejections have skyrocketed in the past week.
The carriers continues their power grab this week. Shippers remain in control, but carriers are much better off than they were a few weeks ago. Capacity is beginning to tighten and rates are being pushed up.
Carriers gained another 5 points of pricing power this week. This marks 6 weeks of power gains, but shippers remain in control.
The carriers gained pricing power this week on the back of surging volumes. Capacity remains loose although tightening each of the past five weeks.
This week’s DHL Supply Chain Pricing Power Index: 25 (Shippers) Last week’s DHL Supply Chain Pricing Power Index: 20 (Shippers) Three-month DHL Supply Chain Pricing Power Index Outlook: 50 (Balanced) The DHL Supply Chain Pricing Power Index uses the analytics and data contained in FreightWaves SONAR to analyze the market and estimate the negotiating power […]
This week the carriers gain some pricing power on the back of surging volumes. Tender rejections are beginning to show signs of life and spot rates are up in most markets.
The DHL Supply Chain Pricing Power index moved up for the first time since the volume surge in March. The index now sits at 15, which is still positions the shippers comfortably in bid negotiations.
National volumes and tender rejections have been roughly flat for the past week. There is no change in the DHL Supply Chain Pricing Power Index this week. Shippers remain in dominant pricing power position.
The DHL Supply Chain Pricing Power Index fell another 5 points this week to its lowest total in series history. Volumes are beginning to come back to life, but capacity remains historically loose and spot rates are extremely low.