




Forward Air said Monday it has paused the planned sale of its intermodal unit in conjunction with its third-quarter report. Management told analysts on a quarterly call that the business is “back on track” and that it remains open to offers reflecting “fair value.”
Forward (NASDAQ: FWRD) commenced a strategic review at the beginning of 2025, which contemplated the sale of parts or all of the company, as pressure from investors mounted following its contested merger with Omni Logistics.
It said on its second-quarter call in August that the potential loss of a contract logistics customer—representing 10% of annual revenue (approximately $250 million)—derailed the plan to sell the entire enterprise to private investors. It instead turned its attention to divesting intermodal and two smaller Omni businesses.
It recently entered a two-year agreement through 2028 to retain a significant portion of the once at-risk account. Although the deal allows the customer to transition some business away between November and March, revenue from the retained portion of the account is expected to grow and exceed revenue generated by the account in 2025.
It has sold both Omni units.
Q3 takeaways
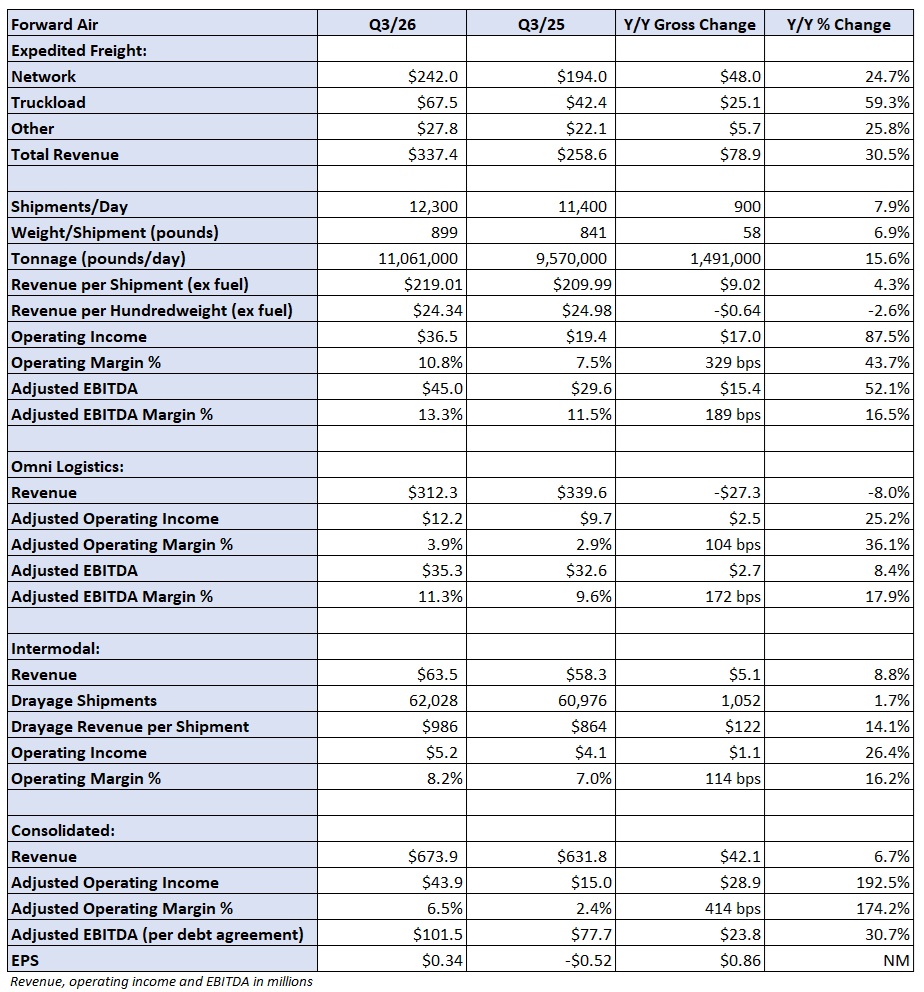
Forward reported consolidated revenue of $674 million, which was up 7% year over year. Consolidated adjusted EBITDA of $101 million was 31% higher y/y.
The company’s expedited unit, which includes less-than-truckload operations, reported a 31% y/y increase in revenue to $337 million. Tonnage increased 16% y/y as shipments and weight per shipment grew by 8% and 7%, respectively.
Yield (ex-fuel) was down 3% y/y, but the jump in shipment weights was a notable drag on the metric. Revenue per shipment (ex-fuel) was up 4% y/y.
Adjusted EBITDA increased 52% y/y at the unit, with the adjusted EBITDA margin increasing 190 basis points to 13.3%.
Omni reported revenue of $312 million, an 8% y/y decline. Adjusted EBITDA of $35 million was 8% higher y/y. The adjusted EBITDA margin improved 170 bps to 11.3%.
Intermodal revenue was up 9% y/y to $63 million. The unit reported an 8.2% EBITDA margin, which was 110 bps better y/y.
Operating cash flow of $51 million in the quarter was $28 million lower y/y, but the period included transaction and integration costs. Liquidity of $446 million was up $45 million sequentially, benefitting from the aforementioned asset sales.
Net debt of $1.6 billion stood at 4.7 times last 12 months’ adjusted EBITDA of $342 million, down from 5.2x at the end of the second quarter, and below the 5.75x debt covenant.
Shares of FWRD were up 7.7% in after-hours trading on Monday.
Why it matters? Forward Air’s results provide a rare look at airport-to-airport ground transportation in an LTL configuration. Its ongoing post-merger restructuring following its combination with Omni Logistics offers valuable insights into the financial complexities of large-scale logistics consolidation.
