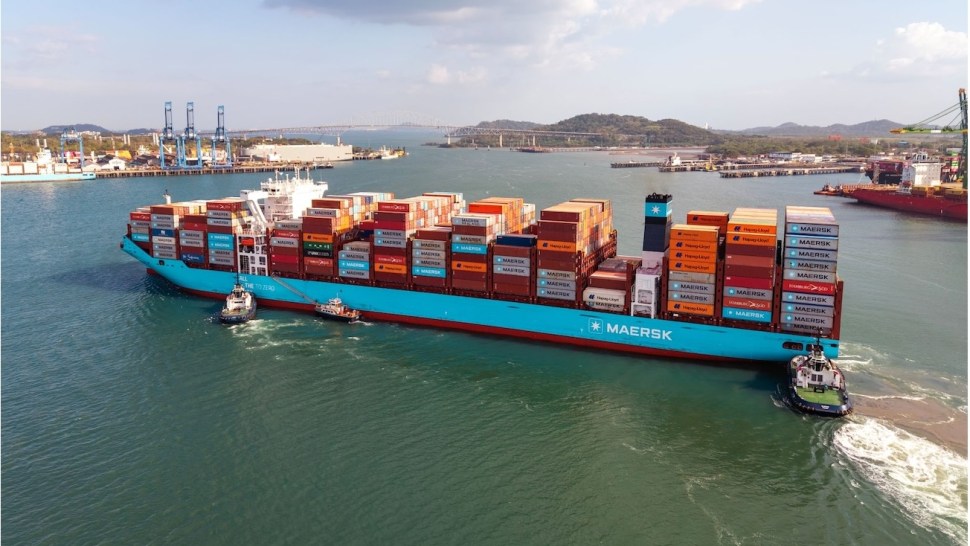
A.P. Moller-Maersk raised its full-year earnings forecast on Thursday after higher freight rates drove a sharp increase in third-quarter profit, but its shares fell as the results and upgraded outlook disappointed investors. The stock dropped as much as 11.6% in Copenhagen trading.
The Danish shipping and logistics group (OTC: AMKBY) reported quarterly earnings before interest, taxes, depreciation and amortization, or EBITDA, of $4.7 billion, up from $2.7 billion a year earlier. That fell short of the $5.04 billion average forecast in an LSEG analyst poll, despite a 27% increase in revenue to $18.1 billion.
Maersk, the world’s second-largest container liner, now expects full-year underlying EBITDA of $14 billion to $14.5 billion, compared with its previous forecast of $10.5 billion to $12.5 billion. It also raised its underlying earnings before interest and taxes, or EBIT, forecast to $8 billion to $8.5 billion from $4.5 billion to $6.5 billion. Free cash flow is expected to exceed $3 billion, versus its previous forecast of above zero.
The increase marks Maersk’s third profit-guidance upgrade this year. The company attributed the latest revision to its third-quarter performance and improved visibility for the remainder of 2026, with the outlook based on global container-market volume growth of around 4%.
Analysts cited by Dow Jones said expectations had risen following strong outlook revisions from rivals Hapag-Lloyd and Zim.
Maersk partners with Hapag-Lloyd in Gemini ocean services.
Maersk’s Ocean division generated quarterly operating profit of about $2.6 billion, up from $567 million a year earlier, as higher freight rates more than offset a slight decline in cargo volumes. The result nevertheless missed a FactSet forecast of $3.07 billion.
Maersk benefited more from what it charged to transport containers than from carrying additional cargo. Volumes in its main shipping business fell about 1%, even as global container demand increased between 2% and 4% during the quarter.
At group level, EBIT increased to $3.3 billion from $1.3 billion, producing an operating margin of 18.1%. Growth extended beyond ocean shipping as Logistics & Services revenue rose 13%, with its EBIT margin improving to 5.8%, while Terminals reported record revenue and maintained strong earnings.
Elevated freight rates have benefited from port congestion and resilient demand. Those conditions helped Maersk raise its earnings expectations substantially even without strong growth in its own shipping volumes.
The company said its financial performance remains subject to uncertainty around macroeconomic conditions, bunker-fuel prices and freight rates. It also continued executing its $1 billion share-buyback program.
Why it matters: Elevated freight rates helped Maersk raise earnings expectations even without strong growth in volumes.
Read more articles by Stuart Chirls here.
Read more:
Asia-US container rates hold as carriers seek $3,000 November rate hikes
ONE lifts profit forecast to $2 billion as earnings surge
Successful quarter at Expeditors boosted by hyperscaler business