

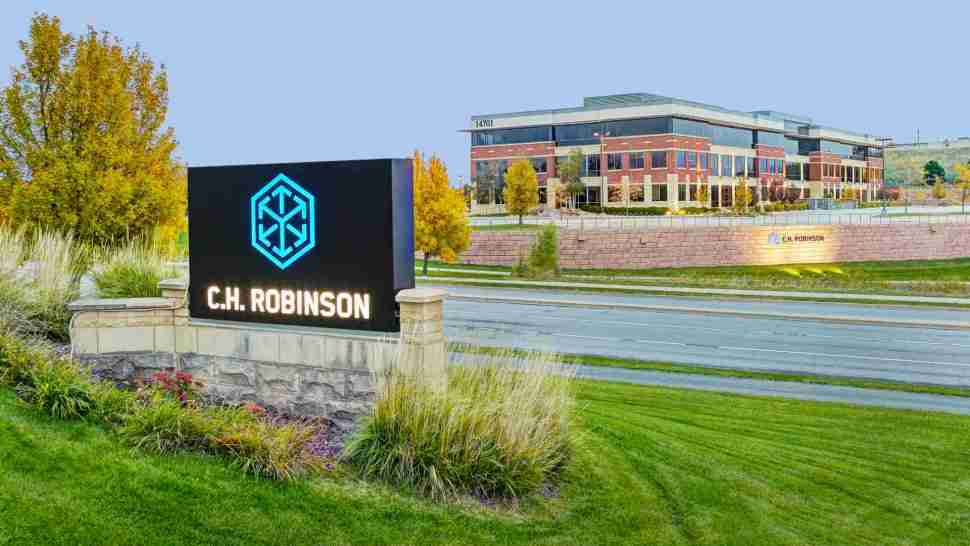
One concern after another was raised by the buy side analysts who follow C.H. Robinson and RXO on the phone call that Monday morning rapidly followed the shocking announcement that C.H. Robinson, the largest broker in the U.S., was buying RXO, generally considered the 3rd biggest 3PL.
What about antitrust concerns? How will you handle technology integration? What kind of legal “docket” does RXO face?
And one by one, those concerns were swatted away. Given that most of the analyst questions included a “congratulations” to C.H. Robinson CEO Dave Bozeman, it seemed clear that Wall Street was sold on the close to $6 billion acquisition.
The shock nature of the deal was best expressed by Tom Wadewitz of UBS on the call. He noted that C.H. Robinson had “talked about being active in acquisitions, but I think this is bigger than expected.”
The two C.H. Robinson executives on the call, Bozeman and CFO Damon Lee, repeatedly said the deal was not done with the legal fallout from the Montgomery vs. Caribe Transport II case in mind. Still, the term “post Montgomery world” was kicked around during the call, and it represented more of an acknowledgement that the 3PL industry is going to change beyond just protecting itself legally.
“I do certainly think in the post-Montgomery world that the flight to quality is important,” Lee said. “So I think that factors into our confidence.” Shippers who were confident in using C.H. Robinson and RXO separately, Lee said, “are going to be even more confident in our capability as a combined entity. Post-Montgomery, this makes the discussion a lot easier as well.”
The end goal numbers are that RXO (NYSE: RXO) is being valued at approximately $5.8 billion in the deal, and that the combined company will have an enterprise value of more than $25 billion.
RXO up on Monday, down on Tuesday
The initial reaction on Wall Street to the merger Monday was a sharp increase in the price of RXO stock–not surprising given that at the very least, the cash-only option or cash portion for shareholders is $30.25 per share–and a decline in the price of C.H. Robinson.
At approximately 1:05 p.m. EDT Tuesday, C.H. Robinson (NASDAQ: CHRW) stock was down $6.63, or 4.72% to $133.98. A day earlier, C.H. Robinson was down $17.11 to $140.61, a drop of 10.85%.
The Monday increase for RXO did not carry into Tuesday. Also at about 1:05 p.m. EDT, RXO was down 37 cts, or 1.29%, to $28.28. It was closer to flat by the end of the day.
One day earlier, RXO finished up $5.27 to $28.65, a gain of 22.54%. The stock price has not reached the cash portion of the deal.
But even if investors right out of the gate may have not been fans of the deal, those sell side analysts with their congratulations told a different story.
Analysts see the synergies as doable
A focus on the post-announcement reports from investment banks was C.H. Robinson’s projections that synergies in the deal will be worth $300 million and that the deal would be accretive to earnings within nine months of the deal’s close, which is anticipated in the first half of next year. Longer-term, C.H. Robinson said the merger would be “mid-teens accretive to adjusted EPS in 2028.”
In the first half of 2026, C.H. Robinson reported adjusted EPS of $2.95, which was up 19.9% from a year earlier.
In a report that it slugged “First Read,” analysts at UBS said that “a backdrop where CHRW has been very good at realizing cost synergies and visibility to stronger truckload volume growth is limited, we believe the deal makes clear strategic sense.”
The decline in the C.H. Robinson price Monday (when the UBS report was published) “provides opportunity, but we also realize it will take time for more visibility to deal integration & other risks.”
At Bank of America Merrill Lynch, the transportation research team led by Ken Hoexter made a similar argument: the drop in the C.H. Robinson stock price, for now, makes sense. But so do the company’s arguments in favor of the deal.
Bank of America Merrill Lynch held its buy rating on the stock, but said its Price Objective was cut to $203 from $226 “as we account for equity dilution in the expected deal.”
The argument for significant cost savings is solid, the bank said. “We believe CHRW’s productivity track record sets a credible path to narrowing RXO’s productivity gap and exceeding its $300 mil synergy target,” it said in its report.
Ratings agencies check in
There was one significant mildly dissenting voice on the strengths of the deal: S&P Global Ratings.
While S&P Global (NYSE: SPGI) did not change its rating on C.H. Robinson–it would not make such a move that quickly–it did shift the outlook on its debt rating to negative.
Both S&P Global and Moody’s (NYSE: MCO) by the end of the day Monday had affirmed their current rating on C.H. Robinson, a BBB+ from S&P Global and Baa2 at Moody’s. Both are investment grade, but the S&P rating is considered higher on an equivalency scale.
In the call with analysts, Bozeman said he expects the deal would not impact the company’s investment-grade debt rating. In an interview with FreightWaves, he added that discussions with the ratings agencies took place as part of the process C.H. Robinson undertook in agreeing to acquire RXO, which is a fairly standard practice for companies about to make a big acquisition.
But S&P Global’s move to negative went one step further than Moody’s, which did not change the outlook on the company.
With new debt to be taken on to finance the acquisition, S&P Global described the expanded levels as “meaningful.”
Those levels are significant enough, S&P Global said, that it will create a need for C.H. Robinson “to materially increase S&P Global Ratings-adjusted EBITDA to achieve credit measures we view as commensurate for our rating on the company. It also reflects our view of the prolonged timing to close, and industry uncertainty in the subsequent 24 months thereafter that could impact our forecasts.”
Identifying the metrics
Among the standards S&P Global and Moody’s looks at in publishing a rating, the ratio of funds from operations (FFO) to debt is a key metric. It is one of the reasons for S&P Global’s move to a negative outlook.
The acquisition, S&P Global said, “will cause expected proforma FFO to debt at close (mid to high 20% area) to be materially below our stated downside scenario (45%), and we consider the potential for integration challenges that could preclude a sufficient and timely improvement.“ To offset that, S&P said, C.H. Robinson will need both growth in EBITDA (as measured by S&P Global, as it is not a standard definition) and “material debt repayment.”
To help strengthen the company’s finances, C.H. Robinson said it would halt stock buybacks until it reaches its “target leverage ratio.” That target, according to the company’s statement announcing the acquisition, is 1.75x to 2.25x net debt to adjusted EBITDA by the end of 2028 for the trailing 12 months.
Moody’s said in its affirmation of its C.H. Robinson debt rating that its estimate is that the 3PL’s debt-to-EBITDA ratio will be approximately 3.6x at the end of 2027, but should fall to about 2.4x by the end of 2028.
Not a lot of overlap
Once the talk on the analysts’ call got past the finances Bozeman talked about the fact that this was not going to be a merger of two companies that are essentially a mirror image of each other.
“We will have an expanded business mix with the combined company offering more solutions across the supply chain,” Bozeman said. “This network density and diversity will allow us to do enhanced freight matching, improve service levels and better compete across transportation markets.”
Both Bozeman and Lee made several references to C.H. Robinson’s “cost to serve efficiencies,” with the estimated synergy savings coming in part from taking RXO’s activities and have them operating under those efficiencies.
Lee said the amount of customer overlap is “a very de minimis number. It is not material at all.”
He said RXO “has built a fantastic business with a technology-enabled platform, a talented team with deep industry expertise, strong customer relationships, a high-quality carrier network, and a proven track record of growth.”
In its presentation to analysts, C.H. Robinson said the number of shippers it serves is 75,000. By contrast, RXO’s shipper network is 18,000.
Carriers served by C.H. Robinson total 450,000. At RXO, its pool is a third of that: 150,000.
One key distinction between the two companies is the level of activity underneath the core truck brokerage. C.H. Robinson’s North American Surface Transport (NAST) segment accounts for 73% of gross revenue. AT RXO, truck brokerage is the same amount. (The entire RXO operation at C.H. Robinson will be under NAST, which is headed at C.H. Robinson by Michael Castagnetto).
But Last Mile is 19% at RXO. Global Forwarding at C.H. Robinson is 18%. Those respective strengths that are not overlapping were viewed as a key reason supporting the deal.
Bozeman said the “complementary” last mile and transportation solutions business at RXO “are where they truly excel.”
More articles by John Kingston
FMCSA’s Elison: ‘weeks’ away from fixing Motus user experience
Daimler Truck: concerned about using cash to avoid new NoX rules
For transportation cybersecurity, AI isn’t helping fight..so far
Brokerage Compliance Symposium
The day before F3. Every compliance issue you face - fraud exposure, carrier liability, FMCSA rules, cargo theft, insurance gaps - navigated by attorneys and operators defining best practices in a changing industry.
F3 Awards Dinner
The night before F3. FreightTech100 companies honored. FreightTech 25 and Shipper of Choice winners revealed live. Cocktail reception into dinner and live music - 300 industry leaders in one purpose-built room.
F3: Future of Freight Festival
Industry-defining keynotes, rapid-fire technology demos, and industry leaders networking in experiences across Chattanooga - plus the inaugural F3 Awards Dinner featuring the FreightTech and Shipper of Choice reveals.
The day before F3. Every compliance issue you face - fraud exposure, carrier liability, FMCSA rules, cargo theft, insurance gaps - navigated by attorneys and operators defining best practices in a changing industry.
The Signal at Chattanooga Choo Choo • Chattanooga, TN Register NowThe night before F3. FreightTech100 companies honored. FreightTech 25 and Shipper of Choice winners revealed live. Cocktail reception into dinner and live music - 300 industry leaders in one purpose-built room.
The Signal at Chattanooga Choo Choo • Chattanooga, TN Register NowIndustry-defining keynotes, rapid-fire technology demos, and industry leaders networking in experiences across Chattanooga - plus the inaugural F3 Awards Dinner featuring the FreightTech and Shipper of Choice reveals.
The Signal at Chattanooga Choo Choo • Chattanooga, TN Register Now