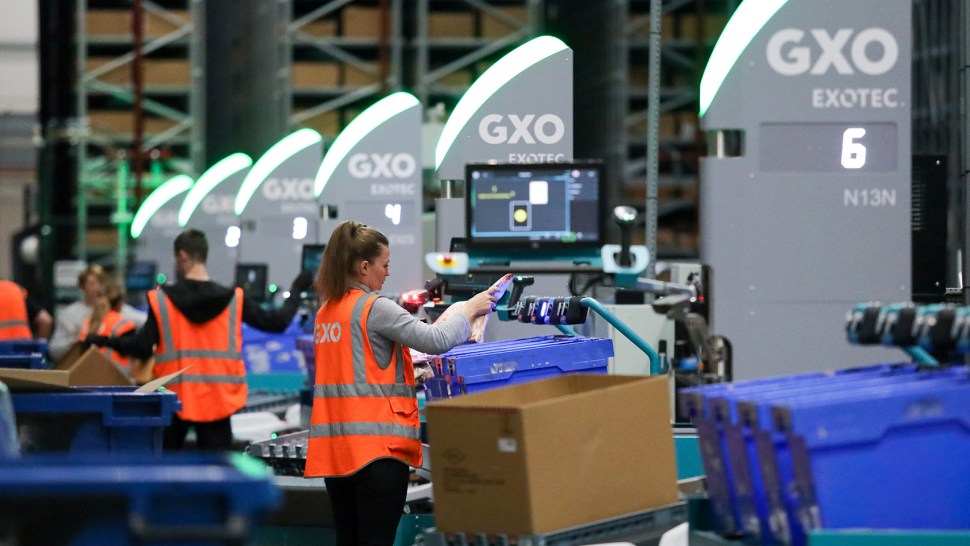
GXO Logistics is seeing accelerating demand for its contract logistics services, particularly in North America, as data centers, aerospace and defense customers fuel a record sales pipeline.
During a Wednesday earnings call, CEO Patrick Kelleher said the company’s renewed commercial strategy is generating larger contracts and expanding opportunities in specialized industries, with momentum expected to continue into 2027.
“The focus on North America, the focus on the strategic verticals, has been additive to the organic growth agenda,” Kelleher told analysts during the call.
Greenwich, Connecticut-based GXO (NYSE: GXO) reported third-quarter revenue of $3.59 billion, a 5.7% increase from $3.4 billion a year earlier. Organic revenue increased 6.4%, while adjusted earnings per share rose 13% to 89 cents.
The company secured $375 million in new business wins during the quarter, a 34% year-over-year increase, and ended September with a record $3.1 billion sales pipeline, up more than 30%.
He said GXO’s contract logistics business typically operates on a six-month sales cycle, meaning initiatives launched over the past year are only beginning to translate into revenue.
North America, data centers drive expansion
North America has emerged as GXO’s largest growth opportunity, with its regional sales pipeline increasing more than 80% year over year to approximately $1.3 billion.
Chief Strategy Officer Kristine Kubacki said the company’s pipeline across the United Kingdom and Europe reached approximately $1.7 billion.
Technology and consumer electronics were GXO’s fastest-growing customer category during the quarter, with revenue increasing 19%, largely driven by data center activity.
Kelleher said GXO continues to see strong demand from technology companies expanding their data center infrastructure, with no signs of a slowdown in requests for proposals.
The company is also pursuing more business in aerospace and defense, industrial logistics and life sciences. Those strategic growth industries accounted for approximately 40% of GXO’s new business wins through the first nine months of 2026.
Kubacki said contracts involving data centers and aerospace customers often require more complex logistics services than traditional retail and consumer distribution.
“Those are very complex mandates, very complicated supply chains,” Kubacki said. “It tends to be stickier. It tends to be higher value-added services.”
GXO also reported new or expanded business relationships during the quarter with Applied Materials, Boeing, NetApp, Unilever and L’Oréal.
The company expects to enter 2027 with more than $850 million in incremental revenue from previously signed contracts, compared with $774 million entering 2026.
Rapid contract growth pressures margins
While revenue and contract wins accelerated, GXO executives said that the pace of new customer onboarding created additional expenses during the quarter.
Adjusted earnings before interest, taxes, depreciation and amortization remained flat at $251 million, resulting in a 7% adjusted EBITDA margin.
Kelleher said the company had to bring in outside consulting and implementation resources to support the rapid launch of several large customer operations.
“With organic growth accelerating at the pace it has, we really found ourselves in Q3 stretched in terms of implementation resources,” he said.
Kelleher characterized those additional expenses as specific to the quarter rather than an ongoing structural problem. He said GXO is expanding its internal implementation capabilities to support future growth.
GXO maintains 2026 outlook
Despite the costs associated with expanding operations, GXO reaffirmed its full-year financial guidance.
The company continues to expect organic revenue growth of 4% to 5%, adjusted EBITDA of $945 million to $965 million and adjusted diluted earnings per share of $2.95 to $3.15.
Suchinski said GXO expects fourth-quarter organic growth slightly above 5%, assuming flat customer volumes. However, if stronger demand continues through the holiday shipping season, growth could approach the 6.4% achieved in the third quarter.
Third-quarter operating cash flow declined to $156 million from $232 million a year earlier, while free cash flow fell to $85 million from $187 million.
Suchinski attributed the free cash flow decline primarily to the timing of enterprise resource planning investments and higher net capital expenditures.
GXO expects the fourth quarter to be its strongest cash-generating period of the year.
GXO third-quarter financial results
| Metric | Q3 2026 | Q3 2025 | YoY change |
| Revenue | $3.59B | $3.40B | +5.7% |
| Organic revenue growth | 6.4% | — | — |
| Net income | $65M | $60M | +8.3% |
| Adjusted EBITDA | $251M | $251M | Flat |
| Adjusted diluted EPS | $0.89 | $0.79 | +12.7% |
| Operating cash flow | $156M | $232M | -32.8% |
| Free cash flow | $85M | $187M | -54.5% |
Why it matters: GXO’s results highlight the challenge facing contract logistics providers: scaling operations quickly enough to capture new business without sacrificing margins.