




Emily Ricks
Wednesday, September 9, 2020
Daily Infographic: Surcharge Surge
To read the full article, click here.
To read the full article, click here.

Accepted freight tenders are running up 18% year-over-year. Carriers are rejecting 1 in 4 contracted tenders and driving rates up. National spot rates above $2.75/mi. and trending higher.

Spot rates out of LA and Dallas are remarkably high and the tight capacity in those markets is driving the freight cycle.

Buckle up, folks, this should be good. Volumes are gushing and rates pushing higher.

The carriers did not lose ground this week, but rather further solidified their dominant pricing position. Volumes remain well above 2018 and 2019, running in the +20% to 25% range. The elevated volumes are giving carriers options in the market and they are exercising those options at a high clip.
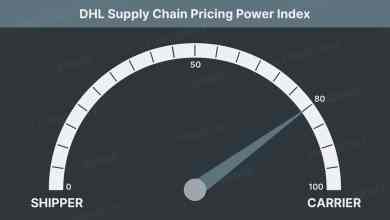
There is no change in the Pricing Power Index this week despite a continuation of the trends we’ve seen over the past few weeks: astounding volumes, carriers rejecting contracted freight at a high clip and rates continuing to trudge upward.

Carriers continue their power grab this week adding 10 points and hitting another new series high. Volumes remain in the stratosphere, and carriers are rejecting contracted freight at levels unseen since the summer of 2018.

Carriers are inteh strongest position in the DHL Supply Chain Pricing Power Index’s 10 month history. Rates have pushed higher in recent weeks as carriers reject more freight than anytime in 2019 and volumes remain elevated.

The Independence Day holiday disrupted both our OTVI and OTRI this week. Volumes are poised to bounce back and remain elevated after the moving average distortion is over.

“We anticipate an above-normal probability for major hurricanes making landfall along the continental United States coastline.”

The carriers continues their power grab this week. Shippers remain in control, but carriers are much better off than they were a few weeks ago. Capacity is beginning to tighten and rates are being pushed up.
The concept of shared truckload isn’t new, but technological advancements in the space make the method more viable than ever.

Carriers gained another 5 points of pricing power this week. This marks 6 weeks of power gains, but shippers remain in control.
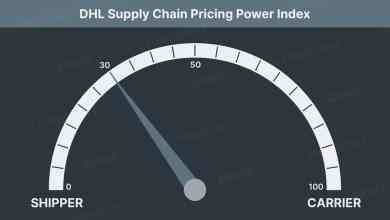
The carriers gained pricing power this week on the back of surging volumes. Capacity remains loose although tightening each of the past five weeks.

While the current COVID-19 pandemic is changing the way we live and work, the adaptations—at least for our working lives—may point to a new paradigm of work self-determination, lower overhead, and more productivity. Ramping up your technological capabilities will allow your business to build on these productivity gains by being able to work from anywhere […]

This week’s DHL Supply Chain Pricing Power Index: 25 (Shippers) Last week’s DHL Supply Chain Pricing Power Index: 20 (Shippers) Three-month DHL Supply Chain Pricing Power Index Outlook: 50 (Balanced) The DHL Supply Chain Pricing Power Index uses the analytics and data contained in FreightWaves SONAR to analyze the market and estimate the negotiating power […]

This week the carriers gain some pricing power on the back of surging volumes. Tender rejections are beginning to show signs of life and spot rates are up in most markets.

The DHL Supply Chain Pricing Power index moved up for the first time since the volume surge in March. The index now sits at 15, which is still positions the shippers comfortably in bid negotiations.
The world of transportation has changed due to COVID-19. Read about how shipping professionals are adapting to those changes.

National volumes and tender rejections have been roughly flat for the past week. There is no change in the DHL Supply Chain Pricing Power Index this week. Shippers remain in dominant pricing power position.