Volumes now only 11% off all-time high, but capacity has been slow to react (with video)
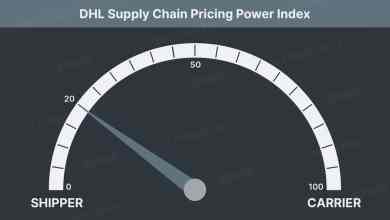
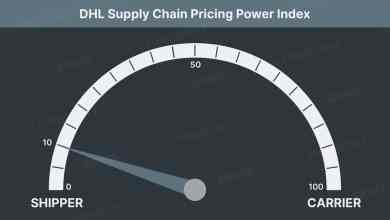
Carriers gained another 5 points of pricing power this week. This marks 6 weeks of power gains, but shippers remain in control.
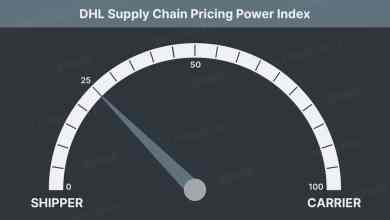
The carriers gained pricing power this week on the back of surging volumes. Capacity remains loose although tightening each of the past five weeks.
This week’s DHL Supply Chain Pricing Power Index: 25 (Shippers) Last week’s DHL Supply Chain Pricing Power Index: 20 (Shippers) Three-month DHL Supply Chain Pricing Power Index Outlook: 50 (Balanced) The DHL Supply Chain Pricing Power Index uses the analytics and data contained in FreightWaves SONAR to analyze the market and estimate the negotiating power […]
What’s been happening in the trucking sector over the last week. They talk about the tightening capacity in Los Angeles and Southern California, consumer spending, and auto sales.
This week the carriers gain some pricing power on the back of surging volumes. Tender rejections are beginning to show signs of life and spot rates are up in most markets.
Zach Strickland and J.P. Hampstead discuss the latest changes in the freight spot market.
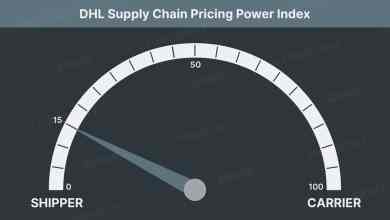
The DHL Supply Chain Pricing Power index moved up for the first time since the volume surge in March. The index now sits at 15, which is still positions the shippers comfortably in bid negotiations.
The DHL Supply Chain Pricing Power Index fell another 5 points this week to its lowest total in series history. Volumes are beginning to come back to life, but capacity remains historically loose and spot rates are extremely low.
Dooner and The Dude are talking about the conflict between truckers and brokers as they battle for dollars in a bottoming spot market.
Zach Strickland and JP Hampstead discuss volumes flattening this week and whether the freight market has hit a bottom. They also discuss earnings from trucking companies before and after COVID-19.
On today’s episode of the podcast we are talking all about pricing and how to avoid devaluing your services plus the broker vs trucker debate.
JP Hampstead and Zach Strickland discuss the current freight climate. Contracted truckload volumes are still going down, but the pace of the decline has slowed.
Declining reefer volumes and how tender rejections have dropped to 6.82%. They also discuss the impact of COVID-19 on the maritime market.
Workers at an Amazon warehouse are protesting conditions while Instacart workers are walking off the job amid coronavirus concerns. Plus, truck drivers are scared, but still delivering and Americans learn the value of the supply chain.
This week in trucking spot rates
While this may be the peak pricing power for the carriers for this freight cycle, the carriers gain another 10 points in the DHL Supply Chain Pricing Power Index this week.
Tender rejections are often a leading indicator of spot rates and thus contract rates at a lag.
Relaxing of driver work restrictions provides breathing room to handle volume surge.
The continuation of panic buying and restocking has swung the DHL Supply Chain Pricing Power Index violently to the upside. Carriers are now in dominant pricing power position for the first time since we began this series in September.
Zach Strickland and JP Hampstead discuss the possibility of e-commerce growth, spending in the service sector, and more. While the effects are yet to be determined, drivers are still out on the road delivering goods throughout the country.