

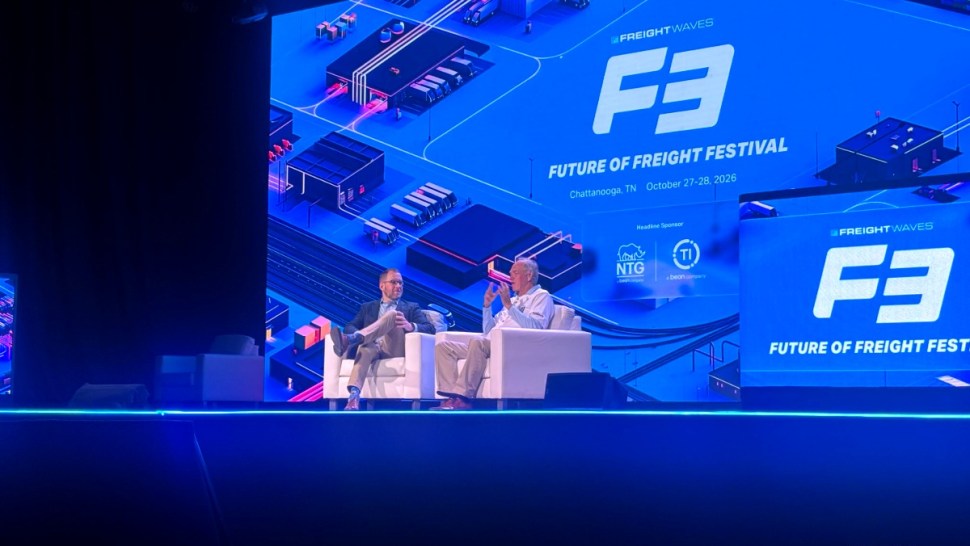
For the better part of eight months the price of diesel has climbed to levels that gasoline has not come close to matching, and for a carrier whose single largest variable cost is the fuel in the tank, that split is not a curiosity but a direct hit to the bottom line, which is why a recent F3 conversation with Patrick De Haan, the GasBuddy analyst who has tracked pump prices since 2009, is worth carriers understanding in full, because the force driving diesel to records has far less to do with the price of oil than almost anyone at the counter assumes.
De Haan, whose firm tracks gasoline and diesel at roughly 150,000 stations across the United States and Canada and has been helping motorists find lower prices for 26 years, called this the single most volatile stretch he has seen, and not because of one dramatic spike. Volatility normally arrives with a hurricane or a geopolitical flare-up and fades in a week or two. This has run since March, cooling in June and July, roaring back in August and September, and never really settling. What makes it different from the last big run-up, though, is that diesel and gasoline have completely decoupled, and the reasons expose how little the fuel most truckers buy actually tracks the headlines about crude.
A Record For Diesel, Not For Gas
The numbers tell the story of the divergence. De Haan noted that diesel blew past its 2022 record of 5.81 dollars a gallon, touched around 6.50 a few weeks before the event, and had eased only slightly to about 6.35. Gasoline, by contrast, remains roughly 70 cents below its own 2022 high. In the last comparable episode, the post-pandemic inflation of 2022, gasoline and diesel both set records together and moved more or less in tandem. This time the two fuels have pulled apart so sharply that Americans are discovering in real time something they rarely have to think about, which is that gasoline, diesel, jet fuel, and crude oil are different products with different economics, and that a barrel of oil is close to worthless until a refinery turns it into something usable.
That last point is the hinge of De Haan’s entire explanation. Everyone watches the price of crude, but crude you cannot refine does you no good, and the real story of the past year is a loss of refining capacity rather than a shortage of oil in the ground.
Why Refining Is The Whole Game
Not all crude is alike, and that is where diesel gets squeezed. De Haan compared it to the oil aisle at an auto parts store, where there is no single weight or grade. Refineries run different blends, from the light grades to the heavier crude that Canada, Venezuela, Iran, and Russia tend to produce, and heavier input yields more heavy product such as diesel. That matters because the countries sitting at the center of this year’s disruptions are heavy-crude players. De Haan put Iran at roughly 55 percent heavy production, noted the year’s long debate over hard-to-refine Venezuelan barrels, and stressed that a refinery generally cannot simply swap one type of crude for another. When the heavy barrels or the plants that process them come under pressure, diesel feels it first.
The structural backdrop makes the squeeze worse. Diesel has run above gasoline for about two decades, a gap that widened after the ultra-low-sulfur diesel specification took hold around 2006. And the United States is no longer the world’s largest refiner, having been overtaken by China in the last year. De Haan flagged China as an underappreciated wild card, because it has throttled some of its refining output to protect its own crude access and strategic reserves, pulling capacity out of a global market that is already short.
The Russia And Ukraine Shock
Layered on top of those slow-moving forces is a fast one. De Haan traced the exponential jump in diesel since July to Russia pulling back on diesel exports, a serious problem given that Russia produces about 10 percent of the world’s diesel. The cause is the Ukrainian drone campaign against Russian refineries, which began last October but has grown far more effective as drone technology advanced over the past year, degrading Russia’s refining sector to the point of domestic fuel rationing and leaving less supply to export. Earlier in the year the Strait of Hormuz and tensions involving Iran were already lifting crude, so the market now carries both pressures at once, a crude-price factor and a refining-capacity factor stacked together. The oil disruption moves the base price, but the refining losses are what sent diesel specifically into record territory.
How The Pump Price Actually Gets Built
De Haan then walked the chain from the trading screen to the truck stop, and the mechanics explain why two carriers hundreds of miles apart can pay wildly different prices on the same day. The foundation for diesel across North America is the NYMEX ultra-low-sulfur diesel contract, essentially a delivered New York Harbor price for diesel on a barge with no taxes attached. From that foundation, regional refining balances take over, and the spread between markets can run 40 to 60 cents a gallon depending on whether you are fueling in New York, Michigan, Florida, Texas, or California.
Geography and infrastructure drive those gaps. The Colonial Pipeline, which De Haan likened to an aorta running in a crescent from the Houston area up through the mid-Atlantic to New York, means wholesale markets along its path price off the Gulf Coast. The Gulf Coast holds the most refining capacity in the country and is usually one of the cheapest places to buy fuel, which is why parts of the lower and mid-Atlantic that tap directly into that pipeline can be surprisingly cheap. But that same export-capable coast can swing to a premium when Europe is scrambling for diesel it can no longer get from Russia. The West Coast runs expensive because California policy has narrowed refining capacity and taxes are high, and even the Great Lakes saw diesel jump recently on localized refining trouble, since those plants lean on Western Canadian crude.
The Volatility Carriers Feel, And The Surcharge That Lags It
The piece most relevant to a trucking operation is how fast wholesale prices now move. The wholesale level, known in the industry as the rack, historically reset once at the end of the day, around five or six o’clock. In this market De Haan said there have been stretches, particularly March and April, when the rack moved intraday, and the difference between filling a tank truck at 5:55 and 6:05 could be 50, 60, 70, even 80 cents a gallon at wholesale. That gets passed down the chain unevenly, because retail stations tend to lag by one to three days on the way up and stay sticky on the way down, and their underground tanks turn over faster than most people think, on average every two to four days and far more often at high-volume truck stops. The idea that a station is selling fuel it priced ten days ago is simply wrong.
This is exactly where the fuel surcharge mechanism strains. Most surcharge programs are pegged to the Department of Energy’s weekly national average on-highway diesel price, a single number published once a week. In a market where the rack can swing most of a dollar in ten minutes and regional spreads run half a dollar or more, a weekly national average cannot keep pace. A carrier running the expensive lanes De Haan described, the West Coast, the Great Lakes during a refining hiccup, or a Gulf Coast gone to export premium, can be paying well above the index that sets the surcharge, and because the index lags the spike and the recovery arrives slowly, the gap between what a truck pays at the island and what the surcharge gives back is real money that comes straight out of margin. The lesson is not to ignore the surcharge but to know that in a decoupled, refining-driven market it recovers less of the true cost than it did when fuels moved together.
What It Means Going Forward
De Haan was measured about blame. Oil companies, he argued, are price takers rather than price makers, and the proof is that back in January and February, before any of this broke, crude sat at 50 to 60 dollars a barrel and producers were not thriving. Convenience stores, where retail margins have run unusually high lately, are riding the same volatility and increasingly make their money on everything other than fuel. The uncomfortable macro note he left on was that the forecasts heading into 2026 had widely predicted a glut of crude, and that expectation ended abruptly on March 1, with no quick return to a calm, well-supplied market in sight. For carriers, the takeaway is that diesel is now driven by a different and more fragile set of levers than the oil price everyone watches, and planning fuel cost around the headline price of crude is planning around the wrong number.
Why It Matters
Diesel has separated from both gasoline and crude oil and set records on the strength of lost global refining capacity, a Russian export pullback, and policy and geography that most fuel buyers never see, which means the mental model of watching oil prices to predict diesel no longer works and the fuel surcharge pegged to a lagging weekly average no longer fully protects a carrier’s margin. For anyone whose costs live and die with the pump, the move is to track diesel on its own terms, understand the regional and refining forces actually setting the price, and treat the gap between real fuel cost and surcharge recovery as a number to manage rather than assume away.
This article is based on an F3 conversation with Patrick De Haan, head of petroleum analysis at GasBuddy. Price figures, dates, and market characterizations are as presented by the speaker at the event. Fuel surcharge mechanics reflect standard industry practice tied to the U.S. Department of Energy weekly diesel price index.
F3: Future of Freight Festival
Industry-defining keynotes, rapid-fire technology demos, and industry leaders networking in experiences across Chattanooga - plus the inaugural F3 Awards Dinner featuring the FreightTech and Shipper of Choice reveals.
Industry-defining keynotes, rapid-fire technology demos, and industry leaders networking in experiences across Chattanooga - plus the inaugural F3 Awards Dinner featuring the FreightTech and Shipper of Choice reveals.
The Signal at Chattanooga Choo Choo • Chattanooga, TN Register Now