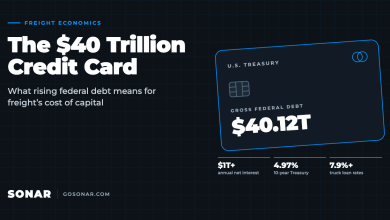
How National Debt Affects Freight Costs and Financing
U.S. debt topped $40 trillion and interest now exceeds $1 trillion a year. Here’s how rising borrowing costs hit truck financing, carriers and warehouses.
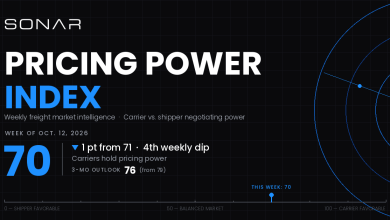
The SONAR Pricing Power Index fell to 70 this week as intermodal contract rates and ocean bookings softened. Truckload rejections held near 13.9%.
SONAR’s Container Atlas shows new booking volumes plummeting over 35% from their Aug. 1 peak, a key indicator that U.S. import demand is rapidly deteriorating. (Photo: Jim Allen/FreightWaves)
Ocean carriers are steadily losing pricing power on the trans-Pacific as China to U.S. demand peaks for the second half of 2023.
U.S. import demand is likely peaking and could soon begin a steady decline toward a “new” bottom in the back half of 2023.
Softening demand in an excess of vessel capacity is putting tremendous downwards pressure on ocean container spot rates.
An unprecedented level of caution among importers likely to cause further declines in import volumes.
Further downside risks to the U.S. economy are increasing the odds of a further decline in containerized import volumes.
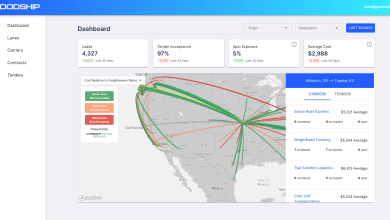
Market data will enhance multiplayer experience for shippers and carriers collaborating on GoodShip.
FreightWaves founder and CEO Craig Fuller provides insight into the state of trucking contract rates.
The West Coast ocean container volume drop is here and will continue for months to come.