The ‘ingenious strategy’ behind most truckers’ least favorite week of the year: International Roadcheck

truck fallen over

International Roadcheck Week is hardly the sexiest topic in trucking, but it is a darn-tootin’ important one. Inspectors in the U.S. and Canada halt tens of thousands of trucks for vehicle inspections for a few days every summer or early fall. They remove thousands of trucks and drivers from the road; in 2021, 16.5% of inspected vehicles were put out of service along with 5.3% of drivers.

It’s uncommon for truck drivers to actually get their vehicles inspected at random during most of the year. To avoid International Roadcheck Week, many truckers simply don’t drive during that period of time — which, presumably, means more unsafe vehicles and drivers on the road outside of the inspection blitz. It’s a question that ate at Andrew Balthrop, a research associate at the University of Arkansas Sam M. Walton College of Business. 

Around 5% fewer one-person trucking companies are active during International Roadcheck Week. But Balthrop and his fellow researcher, Alex Scott of the University of Tennessee, found a major upside to the inspection blitz — even with all the folks who avoid it. According to their working paper published in March 2021, vehicles are safer a month before and after the inspection period. There’s a 1.8% reduction of vehicle violations, according to Balthrop and Scott’s analysis. Surprise inspection blitzes don’t result in the same uptick of compliance. 

I caught up with Balthrop about his research last week at FreightWaves’ Future of Supply Chain conference, and we chatted again on the phone this week about his findings on International Roadcheck Week.

Enjoy a bonus MODES and a lightly edited transcription of our phone interview: 

FREIGHTWAVES: For our readers who are not aware of what Roadcheck Week actually is, can you explain a little bit about what it and why it is important to drivers and companies?

BALTHROP: “The International Roadcheck is part of an alliance between the inspectors in Canada and the ones in Mexico and the U.S. to have a unified framework for making sure trucks are safe to operate. That should make it easier to go across borders when you have this kind of unified structure.

“In the U.S., one of these CVSA inspection blitzes is the International Roadcheck that happens for three days in the summer. Usually it’s a Tuesday, Wednesday and Thursday. And usually it’s the first week in June.

“And in it, they focus on Level One inspections, the North American Standard Inspection where they inspect the driver records, the hours of service, the licensure and I believe medical records as well. Then they inspect the truck. It’s an in-depth inspection where the inspector will actually crawl under the truck to look at various things. And these inspections, from the data that I’ve seen, take about a half an hour on average.

“During the Roadcheck Week, they’ll do about 60,000 inspections, so 20,000 a day. They’re going to pull over a lot of trucks, and this can cause a little bit of congestion at the weigh stations and the roadside inspections localities as the inspectors are doing these inspections.”

Roadcheck Week doesn’t catch all truck drivers, but it has a long-lasting benefit to safety

FREIGHTWAVES: So, can most drivers kind of expect to be pulled over? How likely is that?

BALTHROP: “There’s 1 million or 3 million trucks on the road, somewhere around there on any given day. With 20,000 inspections, most drivers still will not get inspected, but there’s going to be a higher proportion of drivers inspected. 

“You’re more likely to get inspected on these days. If you don’t have a recent inspection on your record, or if you have a bad recent inspection on your record, you’re more likely to be pulled over on these days.”

FREIGHTWAVES: Your research focused on that it’s just unusual that this inspection is announced, that it’s planned. We were talking before about how normally, if you’re trying to assure quality or compliance, you would not announce an inspection in advance. It would be more of a surprise-type situation. 

Can you walk us through why that’s so unusual, or what’s the rationale that you see behind announcing it in advance?

BALTHROP: “It is unusual, and on the surface, it doesn’t make much sense, but it turns out to be kind of an ingenious strategy. So I’ll walk through it here. 

“Over the course of a year, there’ll be 2 million inspections of 3 or 4 million trucks out there. The average rate of inspections is pretty low. It’s not uncommon for truckers to go years without having an inspection. With this low inspection intensity, the FMCSA has sort of a problem of, how does it get anybody to abide by the regulations?

“I’m a jaded economist, and I don’t worry or consider too much ethics and morality and all that kind of stuff. It comes down to incentives for drivers to follow these inspections. The incentives do guide behavior. So, how could the FMCSA incentivize drivers to follow these regulations more closely and adhere to the standards?

“They do this by announcing the blitz. This does two things. On one side, it allows everybody to prepare in advance. There’s a bunch of anecdotal evidence out there that people do prepare for these blitzes in advance. They will have their trucks inspected beforehand for any problems. They’ll time maintenance and upkeep in advance to make sure that their vehicles are in order. “They’ll be a little bit more cognizant of the driver-side regulations. One thing we notice in our study is that hours-of-service violations really drop during these extensions, because people see them coming. They don’t fudge the books in any way.”

Owner-operators can evade Roadcheck Week. Big carriers, not so much.

BALTHROP: “The issue with the announcement, on the flip side, is that it allows people to just dodge the inspection entirely. For a long time, people have talked about how owner-operators and smaller carriers time their vacations for this particular time. They could do this for a couple reasons. To avoid the hassle is a nice way to put it, but it also allows you to be noncompliant to avoid the high-intensity inspections.

“You have this balance here that on one side you get the behavior you want with people complying with regulations. That’s the behavior the FMCSA wants. But on the flip side, you get a bunch of people that are kind of outright dodging inspections.

“When you compare these two things on balance, the policy is actually pretty effective because you get a lot of people focused on maintaining their trucks and obeying the rules during that particular week. Especially with the vehicle maintenance stuff, that lasts a long time. 

“In our research, we saw that vehicle violations, a month before and up to a month afterwards, is when you still notice your vehicle violations. That trucks are kind of better maintained around these blitzes.

“The ingenious aspect of it is that the FMCSA, by concentrating their inspection resources all at one time and announcing it, they’re making it clear that they’re serious about enforcing these regulations and everybody prepares for it. For the number of inspections that are happening, you get fewer tickets than you would have otherwise expected.

“The FMCSA, they’re putting people through a little bit of a hassle, but they’re not having to write a bunch of tickets to get people to comply. They’re not really punishing a whole bunch of people because, by making this apparent that this is going to happen, people comply and the FMCSA gets what they want essentially without having to come down on carriers too hard.”

A convenient time for a vacation, indeed

FREIGHTWAVES: OK, interesting. And how does this pattern of shutting down, how does that compare for an owner-operator versus a driver for a big fleet?

BALTHROP: “If you’re a motor carrier with thousands of power units, you can’t just pack up and not do business on a particular day. They just don’t have that option. So they get inspected at a higher intensity, and you see the larger carriers kind of more focused on making sure that they’re prepared for these inspections. With so many inspections, the larger carriers are going to be inspected at higher rates. You can really damage your reputation if your equipment isn’t in order on this particular day. 

“Versus the smaller carriers, especially if you’re talking about a single-vehicle fleet, an owner-operator type, it is not that difficult to just not work for those three days. And so you see a lot about that. 

“In terms of what the roadway composition looks like, if we look at inspection data and relative to a typical day with the usual inspections, on these Roadcheck days, you have about 5% fewer owner-operators on the road than you otherwise would expect.”

FREIGHTWAVES: Wow. And when you say owner-operators, you also mean just like fleets with just —

BALTHROP: “One-vehicle fleets.”

FREIGHTWAVES: OK, that’s interesting.

BALTHROP: “You know, you see a little bit of effect with the smaller fleets, below six vehicles, but it basically disappears by the time you get to a hundred vehicles.

“This effect is being driven by smaller carriers staying off the road in terms of avoidance. You see this goes also how you would expect; it’s also older vehicles that stay off the road. This is correlated with carrier size. The larger carriers use newer vehicles and owner-operators tend to use some of the older vehicles. But it’s particularly the older vehicles that are off the road.

“This makes intuitive sense. Older vehicles are more costly to keep compliant. Maintenance is more costly, and they’ve been around longer so there’s time for more stuff to have broken essentially.

How a truck driver gets stopped for inspection

FREIGHTWAVES: Can you explain a little bit more, the idea of having this inspection history and why it would benefit a larger or small carrier?

BALTHROP: “Getting flagged for inspection is sort of random, but not totally. If somebody notices something obviously wrong with your truck, that’s ground for a more in-depth inspection. Or if you get pulled over for some other reason, this can be grounds for inspection of some type. 

“But there’s also the inspection selection service. The computer program that is random, that it randomly flags people in for inspection, but it’s based on your inspection history.

“So if your firm hasn’t been inspected recently, or if your carrier doesn’t have a very dense inspection history, you’ll be more likely to trigger that system to pull you in and have you inspected. If you have a dense inspection history, you’re less likely to get inspected.”

FREIGHTWAVES: So how do you get pulled over for inspection? As a person who only drives a passenger car, my main interaction with being pulled over is, I’m driving down the freeway or wherever, and I get stopped by the police. How does it work for a truck driver? How does getting pulled over or inspected work in that way?

BALTHROP: “The law is that you cannot pass a weigh station without pulling in and getting weighed. At that point they may flag you to be inspected. Now, in the past decade or two, there’s been a bunch of electronic devices that are installed in cabs. You may have heard of PrePass or Drivewise. This allows you to pass weigh stations. 

“I don’t have data on how many trucks have the in-cab devices. But from a trucking perspective, they’re so convenient that you don’t have to stop every time you cross a state line. I think the vast, overwhelming majority of trucks have some sort of one of these electronic devices. The DOT inspectors at these roadside inspection points have a dial they can twist essentially about how many people they want to inspect. 

“So during the roadcheck inspection week, they’ll crank that dial all the way up and pull everybody over. And if they get too backed up, they might crank it back down a little bit and so on.”

FREIGHTWAVES: OK, interesting. It reminds me of a highly sophisticated E‑ZPass.

A $10 million-plus expense to trucking companies every year … but it’s worth it if just one fatal crash is avoided

FREIGHTWAVES: Zooming out, when we hear about large truck crashes, something like a vehicle maintenance issue is not really the most sexy explanation. But just looking at the FMCSA data, in 29% of all truck crashes, a major factor is brake problems. So it seems like a lot of the truck crashes on the road are caused by vehicle maintenance, versus something like the driver using illegal drugs or some other sort of more dramatic explanation. Can you speak a little bit to why this sort of vehicle maintenance is important for safety in preventing large crashes?

BALTHROP: “We did a little bit of a back-of-the-envelope cost benefit analysis of this. Let me try and make sure I remember it clearly, but we have it in the paper that the cost of this on one side is that you have the compliance costs the firms are undertaking, and then you have to add to that the delay costs from doing this, and then the cost of the inspection itself, having to pay federal inspectors to do this.

“On the benefit side, it reduces crashes. So when we add up, just looking at the cost of what an inspection is, we don’t have a good idea of how to measure the compliance cost. It’d be fun to measure the delay cost, but I don’t have good enough price data on that to get at that cost. 

“But if you look at what the cost of an inspection is, it is something like $100 or $120 is what you would pay to have one of these inspections done privately. A lot of people do this in the run-up to inspections, and have it done privately so that you can fix whatever the problems are and be sure that you would pass the FMCSA inspection.

“With that $120 figure, if you aggregate that up to 60,000 inspections or whatever, and you take that in comparison, I’m going to give you a bad figure here, it’s on the order of $10 million. That is about the value of a statistical human life. Looking at this economically, it’s worthwhile if it saves one human life. If you identify just one faulty brake system that would’ve resulted in an accident, you’re getting some value out of the program. 

“When you add those other costs in there, we’re going to need to save a couple of lives, but in terms of cost benefit analysis with this kind of stuff, we’re usually looking at orders of magnitude differences in cost and benefits to say something for sure. 

“If you can save just a couple lives, this program will pay for itself.”

Time to start inspecting in the winter

FREIGHTWAVES: Then one last question: Is there any rationale for this program happening in the summer? 

BALTHROP: “I think part of it is that for the inspectors this gets much harder and much more miserable to do in winter conditions.”

FREIGHTWAVES: That makes sense.

BALTHROP: “Inspectors are less productive. One of the things that we talk about in the paper, that they have in addition to the International Roadcheck, is that they have Brake Week where they focus a little bit more on brake inspections. You have Operation Safe Driver a little bit later on in the summer, usually in September, where it’s a little bit more focused on passenger vehicles and how they drive around these trucks.

“But there’s not one in the winter time. There’s an unannounced brake check that usually happens in May, a surprise inspection that’s just one day. But you’re right in pointing out that it might be worthwhile having one of these in the wintertime. You have this periodic high-intensity inspection that kind of incentivizes everybody to be compliant through the summer. 

“But there’s nothing in the winter, so that’s an area. But if I was managing the FMCSA, that would be one of the first questions I ask, ‘Why don’t we have one of these in the wintertime?’”

FREIGHTWAVES: That makes sense. Maybe they can do it in the South or something. Maybe a Miami January inspection … 

That’s it for this special bonus MODES. Subscribe here if you’re not already receiving MODES in your inbox every Thursday. Email the reporter at rpremack@www.freightwaves.com with your own tales on International Roadcheck Week or any other trucking topics. 
Why the Northeast is quietly running out of diesel

The nozzle of a diesel fuel pump is inserted into the tank of a commercial truck as its driver looks on the bankground.

The East Coast of the U.S. is reporting its lowest seasonal diesel inventory on record. And some trucking companies appear spooked.

The East Coast typically stores around 62 million barrels of diesel during the month of May, according to Department of Energy data. But as of last Friday, that region of the U.S. is reporting under 52 million barrels. 

The sharp increase of diesel prices has been a major stressor in America’s $800 billion trucking industry since the beginning of 2022. According to DOE figures, the price per gallon of diesel has reached record highs — a whopping $5.62 per gallon. It’s even higher on the East Coast at $5.90, up 63% from the beginning of this year. 

When relief is coming isn’t yet clear, and experts say higher prices are the only way to attract more diesel into the Northeast.

“I wish I had some good news for the Northeast, but it’s bedlam,” Tom Kloza, global head of energy analysis at OPIS, told FreightWaves. 

2022 has seen record-setting diesel prices. (SONAR)

Everyday Americans don’t fill up their cars with diesel, but the fuel powers our nation’s agriculture, industrial and transportation networks. More expensive diesel means the price of everything is liable to increase. Trucks, trains, barges and the like consumed about 122 million gallons of diesel per day in 2020. 

Patrick DeHaan, a vice president of communications at fuel price site GasBuddy, reported that retail truck stops are hauling fuel from the Great Lakes to the Northeast, calling it “extraordinary.” We’ve also seen anecdotal reports from truck drivers posting company memos:

Pilot Flying J and Love’s, two of America’s largest truck stops, told the Wall Street Journal yesterday that they were not planning to restrict diesel purchases, but were monitoring low diesel inventory.

Not unlike every other supply chain crunch we’ve seen in the past few years, the cause of the Northeast’s diesel shortage is multifaceted. A yearslong degradation of refineries is rubbing against the Gulf Coast preferring to ship its oil to Europe and Latin America.

Here’s a breakdown:

1. The East Coast has lost half of its refineries. 

As Bloomberg’s Javier Blas wrote on May 4 (emphasis ours): 

In the past 15 years, the number of refineries on the U.S. East Coast has halved to just seven. The closures have reduced the region’s oil processing capacity to just 818,000 barrels per day, down from 1.64 million barrels per day in 2009. Regional oil demand, however, is stronger.

Rory Johnston, a managing director at Toronto-based research firm Price Street and writer of the newsletter Commodity Context, told FreightWaves that refining is a “thankless industry,” with intense regulations that have limited the opening of new refineries. The Great Recession of 2008 led to several East Coast refineries shuttering, but there have been more recent shutdowns too. One major Philadelphia refinery shuttered in 2019 after a giant fire (and it already had declared bankruptcy), and another refinery in Newfoundland shut down in 2020.

2. It’s a financial risk to bring diesel to the Northeast.

The Northeast has increasingly relied on diesel from the Gulf region. Much of that diesel travels to the Northeast through the famous and much-adored Colonial Pipeline. You may remember the 5,500-mile pipeline from last year, when a ransomware attack shuttered it for nearly a week!  

It takes 18 days for oil to travel on the Colonial Pipeline from its source in Houston to New York City (or, more specifically, Linden, New Jersey), Kloza said.

That’s a long enough time to prioritize Colonial pipelines financially risky for traders — or, as Kloza said, “incredibly dangerous” — thanks to a concept called “backwardation.”

Backwardation refers to the market condition in which the spot price of a commodity like diesel is higher than its futures price. It’s only gotten stronger over time in the diesel market, Kloza said. So, a company could send off a shipment of diesel and find that it dropped by $1 per gallon in the time the diesel traveled from the Gulf Coast to New York — er, New Jersey. That could mean hundreds of thousands or more in lost profits, so traders often avoid such a fate.

“We’re not in an era where there are any U.S. refiners or big U.S. oil companies who would ‘take one for the team’ and bring cargo in where it’s needed,” Kloza said. 

The desperation is showing in New England and the mid-Atlantic regions. New England diesel retail prices are up 75% from the beginning of 2022, per DOE data. In the mid-Atlantic, diesel is up 67%. 

It’s not worth the risk, even amid ultra-high prices. As FreightWaves’ Kingston reported last week, the spread between a gallon of diesel in the Gulf Coast and its New York harbor price is usually a few cents. Last week, that swung up to 66 cents.

But that uptick still isn’t justifying moving oil to the Northeast — particularly when traders can make so much more money selling diesel abroad. 

3. Of course, we can blame COVID and the crisis in Ukraine. 

The catalyst for this diesel shortage, of course, is the ongoing conflict in Ukraine — particularly Europe’s desperation for diesel after weaning off Russian molecules. 

As CNBC reported in March, Europe is a net importer of diesel. Europe consumed some 6.8 million barrels of diesel each day in 2019; Russia exported some 600,000 barrels per day of that. Today, Europe has only eliminated one-third of its Russian diesel, so prices are expected to continue to climb amid that transition. Latin America, too, has been clammoring for U.S. diesel.

The Gulf Coast has been happy to provide such diesel, amid “insane” prices for diesel abroad, said Johnston. Waterborne exports of diesel from the U.S. Gulf Coast hit record highs last month, according to oil analytics firm Vortexa. (The records only date back to 2016.)

Naturally, COVID is also to blame for the Northeast’s run on diesel. Those refineries still retained on the East Coast scaled back during the pandemic due to staffing issues. It takes six months to a year to reignite refineries that were previously shuttered, Kloza said.

The ‘everything shortage’ endures

It’s been a tale as old as, well, last year. An industry is quietly hampered by supply issues for years, or even decades, and COVID pulls back the curtains on its unsteady foundation. It’s particularly jarring for commodities we never thought about before, like shipping containers or pallets, but that quietly underpinned our livelihood all along. 

Recall the Great Lumber Shortage of 2020? Big Lumber had unusually low stockpiles of wood by the summer of 2020, thanks to a vicious 2019 in the lumber industry shuttering sawmills and the spring of 2020 sparking staffing issues. (There was also a nasty beetle infestation.) Those in lumber expected the pandemic to slow the economy, not ignite online shopping, construction and housing mania. It meant lumber went from around $350 per thousand board feet pre-pandemic to a crushing $1,515 by the spring of 2021. The lumber price roller coaster persists today.  

In diesel, there’s no beetle infestation, but there are plenty of other headaches. It all means higher fuel prices on the East Coast, particularly the Northeast, to lure molecules from the Gulf Coast. And, down the line, probably more expensive stuff for you. 

Do you work in the trucking industry? Do you want to say that you hate or love MODES? Are you simply wanting to chitchat? Email the author at rpremack@www.freightwaves.com, and don’t forget to subscribe to MODES.

Updated on May 13 with the latest comments from truck stops.

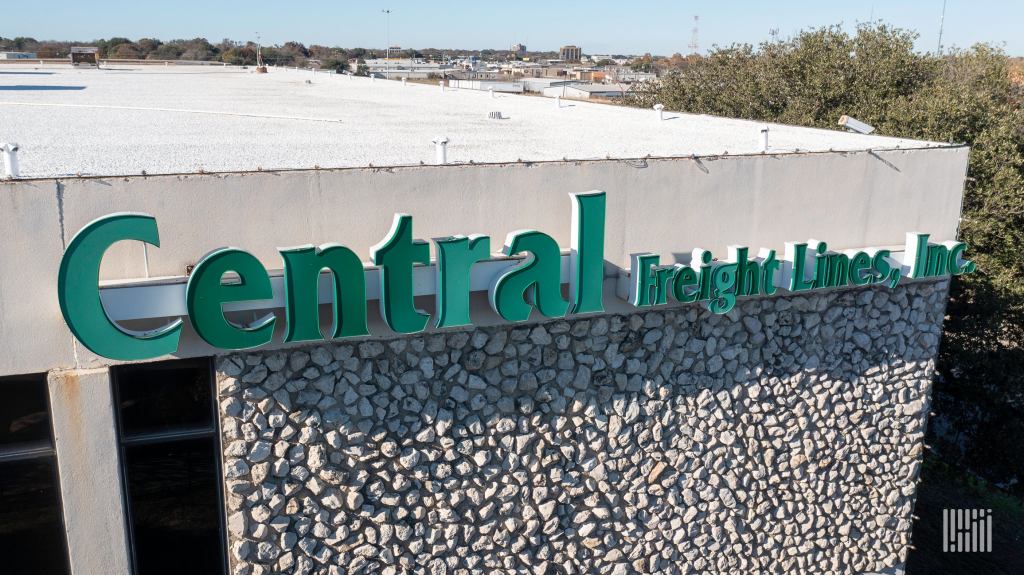
Exclusive: Central Freight Lines to shut down after 96 years

Nearly, 2,100 employees will be laid off right before Christmas. Central Freight Lines is the largest trucking company to close since Celadon ceased operations in 2019.


Waco, Texas-based Central Freight Lines has notified drivers, employees and customers that the less-than-truckload carrier plans to wind down operations on Monday after 96 years, the company’s president told FreightWaves on Saturday.

“It’s just horrible,” said CFL President Bruce Kalem.

A source close to CFL told FreightWaves that CFL had “too much debt and too many unpaid bills” to continue operating, despite exploring all available options to keep its doors open.

Kalem agreed.

“Years of operating losses and struggles for many years sapped our liquidity, and we had no other place to go at this point,” Kalem told FreightWaves. “Nobody is going to make money on this closing, nobody.” 

Central Freight will cease picking up new shipments effective Monday and expects to deliver substantially all freight in its system by Dec. 20, according to a company statement.

A source familiar with the company said he is unsure whether CFL will file Chapter 7 or “liquidate outside of bankruptcy,” but that the LTL carrier has no plans to reorganize.

The company reshuffled its executive team nearly a year ago in an effort to stay afloat, including adding the company’s owner, Jerry Moyes, as CFL’s interim president and chief executive officer. Moyes remained CEO after Kalem was elevated to president in July.

“I think it was surprising that there wasn’t a buyer for the entire company, but buyers were interested in certain pieces but not in the whole thing,” the source, who didn’t want to be identified, told FreightWaves. “Part of it could have been that just the network was so expansive that there was too much overlap with some of the buyers that they didn’t need locations or employees in the places where they already had strong operations.”

Third-party logistics provider GlobalTranz notified its customers that it had removed CFL as “a blanket and CSP carrier option immediately, to prevent any new bookings,” multiple sources told FreightWaves on Saturday.

CFL, which has over 2,100 employees, including 1,325 drivers, and 1,600 power units, is in discussions with “key customers and vendors and expects sufficient liquidity to complete deliveries over the next week in an orderly manner,” a CFL spokesperson said. Approximately 820 employees are based at the company headquarters in Waco.

Despite diligent efforts, CFL “was unable to gain commitments to fund ongoing operations, find a buyer of the entire business or fund a Chapter 11 reorganization,” another source familiar with the company told FreightWaves.

Kalem said the company had 65 terminals prior to its decision to shutter operations. 

FreightWaves received a tip from a source nearly two weeks ago that CFL wasn’t renewing its East Coast terminal leases but was unable to confirm the information with CFL executives. 

Another source told FreightWaves that some of the LTL carrier’s West Coast terminals had been sold recently, but that no reason was given for the transactions.

At that time, Kalem said the company was “working to find alternatives” and couldn’t speak because of nondisclosure agreements. He said executives at CFL, including Moyes, were trying to do everything to “save the company.”

“Jerry [Moyes] pumped a lot of money into the company, but it just wasn’t enough,” Kalem said.

Kalem said he’s aware that a large carrier is interested in hiring many of CFL’s drivers but isn’t able to name names at this point. 

“Central Freight is in negotiations to sell a substantial portion of its equipment,” the company said in a statement. “Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area.”

As of late Saturday night, Kalem said fuel cards are working and drivers will be paid for freight they’ve hauled for the LTL carrier until all freight is delivered by the Dec. 20 target date.

“I’m going to work feverishly with the time I have left to get these good people jobs — I owe it to them,” Kalem told FreightWaves. “We are going to pay our drivers — that’s why we had to close it like we’re doing now. We are going to deliver all of the freight that’s in our system by next week, and we believe we can do that.”

During the outset of the pandemic, Central Freight Lines was one of four trucking-related companies that received the maximum award of $10 million through the U.S. Small Business Administration’s Paycheck Protection Program (PPP). This occurred around the time that CFL drivers and employees were forced to take pay cuts, a move that didn’t go over well with drivers.

“It all went to payroll,” Kalem said about the PPP funds. “Yes, our employees and drivers did take a pay cut over the past few years, and we gave most of it back, even raised pay over the past several months, but it just wasn’t enough to attract drivers.”

FreightWaves staffers Todd Maiden, Timothy Dooner and JP Hampstead contributed to this report.


Watch: Central Freight Lines’ impact on the LTL market


FreightWaves CEO and founder Craig Fuller reacts to the Central Freight Lines news:

“With Central struggling for many years and unable to reach profitability, it makes sense that they would want to liquidate while equipment and real estate are fetching record prices.”


Central Freight Lines statement

Here is the statement given by Central Freight Lines to FreightWaves late Saturday after reports surfaced of its impending closure:

“We make this announcement with a heavy heart and extreme regret that the Company cannot continue after nearly 100 years in operation. We would like to thank our outstanding workforce for persevering and for professionally completing the wind-down while supporting each other. Additionally, we thank our customers, vendors, equipment providers, and other stakeholders for their loyalty and support.

“The Company explored all available options to keep operations going. However, operating losses sapped all remaining sources of liquidity, and the Company’s liabilities far exceed its assets, all of which are subject to liens in favor of multiple creditors. Despite diligent efforts, the Company was unable to gain commitments to fund ongoing operations, find a buyer of the entire business, or fund a Chapter 11 reorganization. Given its limited remaining resources, the Company concluded that the best alternative was a safe and orderly wind-down. As we complete the wind-down process, our primary goal will be to offer the smoothest possible transition for all stakeholders while maximizing the amount available to apply toward the Company’s obligations.

“Central Freight is in negotiations to sell a substantial portion of its equipment. Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area. Discussions are ongoing and no purchase of assets or offer of employment is guaranteed.”


Brief history of Central Freight Lines

1925Founded in Waco, Texas, by Woody Callan Sr.
1927Institutes regular routes in Texas between Dallas, Fort Worth and Austin.
1938Dallas facility opens as world’s largest freight facility.
1991Receives 48-state interstate operating authority, expands into Oklahoma.
1993Joins Roadway Regional Group and begins service in Louisiana.
1994Expands into Colorado, Kansas, Missouri, Illinois and Mississippi.
1995Consolidation of Central, Coles, Spartan and Viking Freight Systems into Viking Freight Inc. is announced. Central’s Waco corporate HQ starts closure.
1996Becomes the Southwestern Division of Viking Freight Inc.
1997Investment group led by senior Central management purchases assets of former CFL from Viking Freight and reopens as a new Central Freight Lines.
1999Expands into California and Nevada.
2009CFL Network provides service to Idaho, Utah, Minnesota and Wisconsin.
2013Acquires Circle Delivery of Tennessee.
2014Acquires DTI, a Georgia LTL carrier.
2017Acquires Wilson; new division created with an increase of 80 terminals.
2020Wins Carrier of the Year from GlobalTranz.
Acquires Volunteer Express Inc. of Dresden, Tennessee.
Source: Central Freight Lines

Warehouse cramming is about to begin — Freightonomics

nVision Global, is a leading Global Freight Audit, Supply Chain Management Services company offering enterprise-wide supply chain solutions. With over 4,000 global business “Partners”, nVision Global not only provides prompt, accurate Freight Audit Solutions, but also providing industry-leading Supply Chain Information Management solutions and services necessary to help its clients maximize efficiencies within their supply chain. To learn more, visit www.nvisionglobal.com

Warehouse space is at a premium right now and with peak season right around the corner, shippers are starting to scramble for space. 

Zach Strickland and Anthony Smith look into what shippers are doing to prepare for the end-of-year crunch. They welcome Zac Rogers from Colorado State University to the show to talk through the industry tightness. 

The three also talk about the latest Logistics Managers Index results and what they mean for the fourth quarter of 2021. 

You can find more Freightonomics episodes and recaps for all our live podcasts here.

Seasonality pushing rejections and rates higher ahead of the Fourth

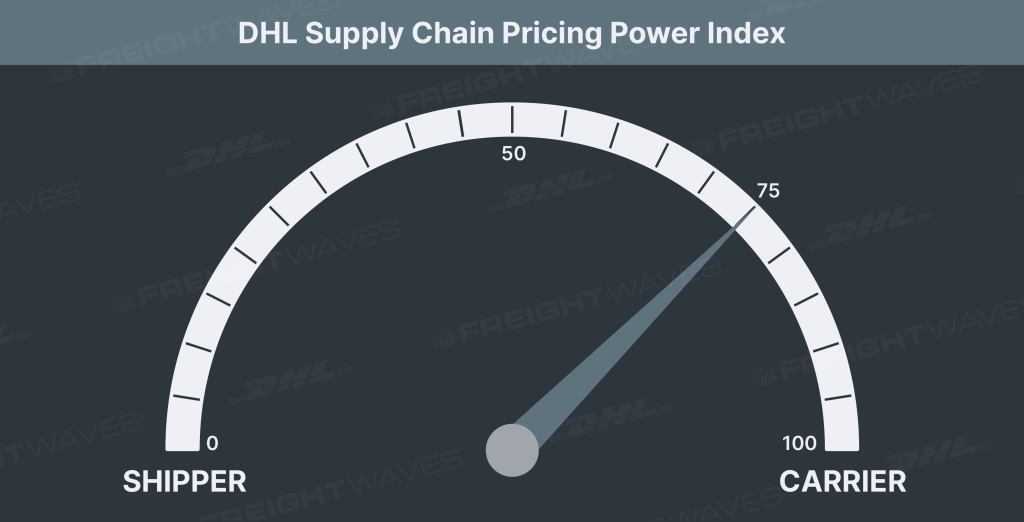
This week’s DHL Supply Chain Pricing Power Index: 75 (Carriers)

Last week’s DHL Supply Chain Pricing Power Index: 70 (Carriers) 

Three-month DHL Supply Chain Pricing Power Index Outlook: 70 (Carriers)

The DHL Supply Chain Pricing Power Index uses the analytics and data in FreightWaves SONAR to analyze the market and estimate the negotiating power for rates between shippers and carriers. 

The Pricing Power Index is based on the following indicators:

Load volumes: Absolute levels positive for carriers, momentum neutral

The Outbound Tender Volume Index at 15,980 is nominally higher now than basically at any point in the past 12 months with the exception of the week prior to Thanksgiving/Black Friday last year. OTVI captures all electronic tenders, including rejected ones, so when accounting for the rejection rate, we can get an even more accurate look at volumes. 

OTVI rose through the back half of May into the national holiday and has risen even further since. Throughout the back half of May and into the middle of June, tender rejections declined substantially. Meaning, current volume throughput is actually understated when comparing OTVI now to OTVI in November 2020. After adjusting for rejected tenders, the accepted outbound tender volume index is just 2.2% below the 2020 peak in November. At that time, OTVI surged towards 17,000, but the rejection rate moved in-kind towards its natural ceiling of 28%. So, the total accepted freight tenders in mid-June is comparable to the peakiest of peak seasons in 2020. Incredible. 

However, since the middle of June, tender rejections have begun increasing again heading into Independence Day, a time when many drivers spend time off the road with their families. The move higher in OTVI this week has been driven primarily by higher rejection rates, rather than higher freight demand. 

Over the past month, the drivers of freight volumes have continued to be imports and from just about every port. The west coast continues to provide seemingly non-stop container ships, while Houston, New Orleans, Miami and Savannah are seeing very strong throughput as well. 

It is van volumes that are driving freight markets higher right now. The Reefer Outbound Tender Volume index has tumbled 25% since its all-time high in the weeks after the polar vortex in February. Since Memorial Day, ROTVI has fallen another 10.5%. This is likely a factor of declining grocery demand, but I would expect the trend to reverse course in the near future as summer festivities accelerate. 

Dry van volumes pushed higher in the back half of May and into June while reefer volumes have declined significantly. 

SONAR: VOTVI.USA (Blue); ROTVI.USA (Green)

The congestion at our nation’s ports has spread from Los Angeles and Long Beach to Oakland, California. The California coastline is a parking lot of container ships, most of which are full to the brim with imports, awaiting berth. As detailed in the economic section, there are some signs that the reversion is underway with Americans paring back spending on pandemic superstar categories in favor of airlines, lodging and entertainment. But spending remains strong despite the moderation, and low inventory levels offset much of the decline that will occur from slowing demand. Real inventories are 3% higher now than pre-pandemic, but real sales growth is far outpacing inventory growth, leading to the lowest inventory-to-sales ratio in decades. 

On the manufacturing side, the ISM Manufacturing PMI expanded in May after declining in April. We’ve been in expansionary territory for 12 consecutive months. New orders, production, imports/exports and employment are all growing. The major issues should come as no surprise: Deliveries are slowing, backlogs are growing and inventories are too low. 

In all, there are many, many catalysts to keep freight demand strong for the foreseeable future. Americans are traveling and spending on services at a high clip, but the high savings rate is enabling it to occur without a massive detriment to goods spending. 

SONAR: OTVI.USA (2021 – Blue; 2020 – Green; 2019 – Orange; 2018 –  Purple)

Tender rejections: Absolute level and momentum positive for carriers

After declining steadily from mid-March to mid-May, the Outbound Tender Reject Index has reversed course heading into Independence Day. This is typical for a national holiday as carriers selectively choose loads to bring drivers closer to home. OTRI now sits above 25% for the first time in June. 

One of our newest indices in SONAR gives us the ability to compare markets on as close to an apples-to-apples basis as possible. FreightWaves’ Carrier Trend Market Score indices are divided into two perspectives – shipper/broker and carrier. The scores are positioned on a scale from 1-100 and have values measuring van and refrigerated (reefer) capacity. The higher values represent more favorable trends for whichever perspective. For instance, a value near the high-end of the range would suggest very favorable conditions for carriers in our carrier capacity trend score index. 

For the past several weeks, capacity disparities have been driven by import volumes. The markets with the tightest carrier capacity coincide with the nation’s busiest ports. Ontario, California, Savannah, Georgia, and Atlanta all have carrier capacity trend market scores of 100. 

SONAR: Capacity Trend Market Score (Carriers – VAN)

By mode. Reefer rejection rates tumbled from it’s all-time high in March to under 35% in mid-June before popping higher over the past two weeks. Reefer rejections are still quite high from a historical standpoint at 38%, but are significantly lower than just three months ago when reefer carriers were rejecting half of all electronically tendered loads. 

SONAR: VOTRI.USA (Blue); ROTRI.USA (Orange)

Dry van tenders make up the majority of all tenders, so the van rejection rate mirrors the aggregate index closely. Van rejections have surged from ~23% to ~26% over the past two weeks. 

Yes, one-in-four loads being rejected is not ideal, but it’s better than 30%. I am unaware of any meaningful signals that capacity is being added at a rate that would change my outlook. With so many catalysts for demand, and many constraints on drivers including the Drug & Alcohol Clearinghouse, driver training school closures and continued government unemployment benefits, the outlook is tight throughout this year and into 2022. That’s not to say we won’t see improvement as consumers revert to pre-pandemic spending habits and drivers enter or reenter the market. But I’m not expecting any quick reversal of this environment; there are simply too many catalysts driving volume and suppressing capacity. 

SONAR: OTRI.USA (2020/21 – Blue; 2020 – Green; 2019 – Orange)

Freight rates: Absolute level and momentum positive for carriers

Throughout June, spot rates have moderated while contract rates have pushed higher. The Truckstop.com dry van rate per mile (incl. fuel) has fallen from $3.21 to $3.11 since the beginning of June, while FreightWaves van contract rates have risen from $2.50 to $2.59/mile, exclusive of fuel. 

I still believe the Truckstop.com dry van national average will not retest the post-vortex surge pricing that brought spot rates up to an all-time high of $3.30. But, there aren’t many catalysts to bring spot rates down anytime soon either. Demand is unwavering with continued strong consumer goods demand, humming industrial recovery and a potentially cooling, yet still sizzling, hot housing market. And carriers can’t fill enough trucks to keep up with demand. 

Prior to the seasonal movements we’re seeing in tender rejections, routing guides generally had been improving through Q2. We should continue to see a convergence between spot and contract rates, but spot rates will remain historically very elevated throughout the summer as demand simply outstrips capacity. 

SONAR: TSTOPVRPM.USA (Blue); VCRPM1.USA (Green)  

Economic stats: Momentum and absolute level neutral

Several economic releases this week are worth noting.

Weekly jobless claims were released Thursday and give us one of the best close-to-real-time indicators of the overall economy.  This week, the data was again very promising as the labor market continues on a bumpy but trajectorially stable recovery path. 

First-time filings totaled 411,000 for the week ended June 19, a slight decrease from the previous total of 418,000 but worse than the 380,000 Dow Jones estimate, the Labor Department reported Thursday. Initial claims have held above 400,000 for consecutive weeks after falling to a pandemic low of 374,000 three weeks ago. As things stand, the current level of initial claims is about double where it was prior to the Covid-19 pandemic. 

The good news on the jobs front is that continuing claims are on the decline, falling to 3.39 million, a drop of 144,000. That number runs a week behind the headline claims total.

Initial jobless claims (weekly in May 2020-May 2021)

At the time of writing, the newest weekly data for the week ending May 29 had not been updated in SONAR. This week, claims fell from 405,000 to 385,000. 

SONAR: IJC.USA

Consumer. Turning to consumer spending, as measured by Bank of America weekly card (both debit and credit) spending data, total card spending (TCS) in the latest week accelerated to 22% over 2019. This is the first time in June that TCS has topped 20% over 2019, but spending has been running up 16-19% consistently on a two-year comp for months. For contect, the average pre-pandemic two-year growth rate was about 8% (from 2012 to 2019). 

The Bank of America team highlighted service spending in the nation’s two largest state economies, California and New York, which are now fully reopened. Spending at restaurants is now well above 2019 in both states, and the team believes there is more capacity for spending to accelerate in the states that were slower to reopen given pent-up demand. 

There was also a notable acceleration in spending on clothing this week, according to Bank of America. It could be a reversal from some softening in the early weeks of June, or an indication of people refreshing wardrobes ahead of a return to work, more travel and vacations. One tepid statement for freight markets from this week;s report: Leisure spending is on the rise and durable goods spending is flatlining.  

FreightWaves’ Flatbed Outbound Tender Reject Index, both a measure of relative demand and capacity, moves directionally with the ISM PMI. 

SONAR: ISM.PMI (Blue); FOTRI.USA (Green) 

Manufacturing. Over the past two weeks, regional manufacturing surveys have reported generally positive readings amid logistical challenges. The New York Fed’s Empire State business conditions index declined 6.9 points to 17.4 in June, retreating from strong readings the past two months. The Empire State Index is a diffusion index with a baseline of zero; any reading above zero indicates improving or expansionary conditions. 

Delivery times lengthened to a new record during the month, new orders and shipments fell, and inventories entered negative territory. The supply chain and transportation challenges are as visible upstream as downstream, but overall the manufacturing sector is handling. Growth continued throughout the second quarter in both the Empire State and Philly Fed indices. 

The Philadelphia Federal Reserve’s business activity index edged lower to a still robust 30.7 in June from 31.5 in the prior month. Unlike NY, the pace of shipments growth accelerated in the Philly region during June. The employment subcomponent rose to a very healthy 30.7 from 19.3 last month, the regional bank said. 

Record-long lead times, wide-scale shortages of critical basic materials, rising commodities prices and difficulties in transporting products are continuing to affect all segments of the manufacturing economy, but demand remains strong. 

For more information on the FreightWaves Freight Intel Group, please contact Kevin Hill at khill@www.freightwaves.com or Andrew Cox at acox@www.freightwaves.com.

Check out the newest episodes of our podcast, Great Quarter, Guys, here.

Project44 acquires ClearMetal to strengthen predictive tools

Project44, a leader in real-time visibility of the global supply chain, announced on Thursday it has acquired ClearMetal, a San Francisco-based supply chain planning software company that focuses on international freight visibility, predictive planning and overall customer experience. The terms of the acquisition were not disclosed.

ClearMetal, founded by top software engineers and data scientists from Stanford, Google and other Silicon Valley elites, has created a “continuous delivery experience” that leverages proprietary machine learning algorithms that can forecast supply chain disruptions. 

In an interview, Jason Duboe, chief growth officer at project44, explained that bringing in ClearMetal’s elite team is essential for the company’s future predictive solutions.

“Their team construct is fundamentally different. When you look at their data science, machine learning and computer science background, they are best in class,” he said. “Applying the team to solve really interesting challenges, starting with highly predictive ETA and deeper exception management to create more predictive analytics is really a key component here.”

Project44 recently acquired Ocean Insights to gain global supply chain vessel visibility and has announced it has expanded its truckload tracking services within Asia. Bringing on this new team of engineers will allow the company to capitalize on strong predictive tools, strengthening the supply chain of its customers.

“We’re going to be expanding deeper into Asia, and from a port perspective, getting data much earlier than competitors,” explained Duboe. “Our freight forwarder integrations will give us much deeper visibility from an end-to-end perspective in these regions.”

Along with the acquired skills the ClearMetal team will bring to project44, it brings a large book of customers, including large CPGs, retailers, manufacturers, distributors and chemical companies. These advanced use cases will strengthen the predictive planning tools, and project44 continues to expand into different customer markets.

“What we gain from ClearMetal is a holistic platform for anybody that joins the platform in the future,” said Duboe. “They have large customers with incredibly demanding and advanced use cases. So when it comes to order and inventory, functionality, supplier onboarding, and moving upstream into those processes, we can capture exceptions earlier on.”

Click here for more articles by Grace Sharkey.

Related Articles:

Project44 expands real-time visibility into China

Project44 reels in Ocean Insights in ‘largest acquisition in visibility space’

‘Project44’s vision has always been global’

Borderlands Mexico: Truckers secure 29 agreements on highway safety after nationwide strike

Borderlands Mexico is a weekly rundown of developments in the world of United States-Mexico cross-border trucking and trade. This week in Borderlands Mexico: Truckers secure 29 agreements on highway safety after nationwide strike; MISUMI Americas expands Mexico operations with new 45,000-square-foot facility; and Prime Fuel Solutions expands Texas fleet, targets neighboring states.

Truckers secure 29 agreements on highway safety after nationwide strike

Mexico’s federal government and trucking industry representatives have advanced 29 agreements aimed at combating cargo theft, improving highway security and addressing deteriorating infrastructure.

The agreements arrive nearly a month after nationwide trucker protests disrupted freight transportation across 19 states.

The deals emerged from six working groups involving 10 government authorities and representatives of the National Chamber of Freight Transportation (CANACAR), the Honorable Mexican Alliance of Transport Organizations (HAMOTAC), the Mexican-American Federation of Transporters (FEMATRAC) and the Integrating Organization of Conventional Rights (INDECO).

The organizations, supported by Mexico’s Confederation of National Chambers of Commerce, Services and Tourism (CONCANACO SERVYTUR), announced the progress Wednesday, during a news conference in Mexico City.

The negotiations focus on persistent problems affecting Mexico’s trucking industry, including cargo theft, extortion, highway maintenance, excessive towing charges, regulatory requirements and the safety of commercial truck drivers.

The discussions follow an Oct. 26-27 nationwide trucking strike that prompted demonstrations and highway blockades across major freight corridors.

Mexico’s Interior Ministry reported demonstrations at 38 locations across 19 states, involving 691 vehicles and 858 participants.

The protests highlighted concerns about highway crime and rising transportation costs, particularly along routes connecting Mexico’s industrial centers to U.S. border crossings.

Highway security and cargo theft remain top priorities

One of the central components of the negotiations involves improving coordination among Mexico’s Interior Ministry (SEGOB), the Ministry of Security and Citizen Protection (SSPC), the National Guard and state authorities.

The agreements call for establishing direct communication channels between transportation companies and law enforcement agencies to report criminal activity and respond to security incidents.

Authorities and trucking representatives also agreed to work toward standardizing procedures used by prosecutors, including efforts to accelerate the release of recovered trucks following cargo theft investigations.

Other measures include identifying unauthorized highway checkpoints and strengthening enforcement against devices used to jam GPS tracking signals.

The initiatives are intended to improve the government’s ability to prevent, investigate and prosecute crimes affecting freight transportation companies and their drivers.

According to figures presented during the news conference on Wednesday by Mexican transportation publication T21, Mexico recorded 6,211 cargo transportation robberies from January through September 2026.

CANACAR also reported 145 additional incidents during October.

Carlos García Álvarez, national president of HAMOTAC, expressed frustration that highway crimes have continued despite meetings with federal authorities.

Trucking groups identify 62 highways needing repairs

Infrastructure improvements represent another major component of the negotiations.

The trucking organizations submitted an assessment to Mexico’s Ministry of Infrastructure, Communications and Transportation (SICT) identifying 62 highway segments requiring priority maintenance and repairs.

The assessment is intended to help federal authorities identify roads for inclusion in future construction and maintenance programs.

Industry representatives also reported progress toward reclassifying approximately 11,000 kilometers, or 6,835 miles, of Mexico’s highway network.

The proposed changes cover 40 segments across 102 highways, with publication in Mexico’s Official Gazette expected by December.

Adalberto Gutiérrez Muñoz, national president of INDECO, criticized deteriorating highway conditions and the high tolls paid by commercial carriers.

He also called for improvements to highway access points that could be exploited by criminal organizations.

According to CANACAR, freight transportation companies contributed more than $3.6 billion, representing approximately 56% of toll highway revenue in 2025.

Government targets towing abuses and regulatory costs

Another significant agreement involves the planned December launch of SICT’s computerized towing service registration system, known as SIRSE.

The platform is designed to improve transparency in towing, vehicle recovery and impound services while reducing excessive charges and abusive practices.

Trucking representatives have repeatedly complained about towing costs and the difficulties associated with recovering commercial vehicles following accidents or law enforcement investigations.

The organizations also submitted an assessment of federal, state and municipal regulatory requirements to Mexico’s Digital Transformation and Telecommunications Agency.

The review could lead to a unified digital record for trucking companies and a single-window system intended to simplify administrative procedures.

Additional discussions include proposed tax incentives for private investment in secure truck parking facilities and driver rest areas.

Industry representatives are also seeking clarification of forthcoming labor regulations governing electronic work-hour records, including how driving, waiting, loading, unloading and rest periods will be classified.

MISUMI Americas expands Mexico operations with new 45,000-square-foot facility 

MISUMI Americas has opened a new 45,000-square-foot manufacturing and fulfillment facility in Monterrey, Mexico, more than quadrupling its previous footprint as the company expands its capabilities to serve the country’s growing industrial sector.

The Oakland, California-based supplier of mechanical components and assemblies announced the expansion Nov. 16, saying the new facility adds in-house manufacturing and fulfillment of mechanical assemblies while strengthening its network of local manufacturing partners.

Since establishing its Mexico center of excellence in the Monterrey region in 2023, MISUMI Americas has expanded its Mexican manufacturing partner network by more than 250%, according to a news release.

The company’s Mexico operations support customers in aerospace, medical technology, semiconductors, robotics, automotive and energy. Its manufacturing capabilities include CNC machining, sheet metal fabrication, injection molding, extrusions and castings.

“Demand in Mexico has grown, and this facility is how we keep pace,” Dave Evans, president and CEO of MISUMI Americas, said in a statement. “Bringing assembly in-house and growing our manufacturing partner network gives customers more ways to get their parts and assemblies from one team.”

Prime Fuel Solutions expands Texas fleet, targets neighboring states

Abilene, Texas-based Prime Fuel Solutions is expanding its fuel delivery fleet and extending operations into neighboring states as it works toward establishing a nationwide fuel logistics network.

The company, which provides on-site fueling services for construction, industrial and other mission-critical projects, announced the expansion on Wednesday, along with the launch of a new website designed to streamline customer access to its services.

Prime Fuel Solutions said it is adding trucks and drivers to meet growing demand for scheduled and emergency fuel deliveries. The company provides diesel, gasoline, diesel exhaust fluid (DEF) and propane, along with bulk fuel storage, tank rentals and on-site fuel management.

Prime Fuel Solutions also offers 24-hour emergency fueling and delivery reporting. Its new website, primefuelsolutions.com, allows contractors to request quotes and access emergency fueling services.

The company, a sister business of Prime Equipment Solutions, serves construction, heavy civil, industrial and mission-critical projects.

The company did not disclose the number of vehicles added to its fleet, the investment involved or which neighboring states it plans to enter.

Why it matters: The negotiations could reduce cargo theft risks and costly disruptions along critical freight corridors connecting Mexican manufacturers with U.S. markets.

Shippers’ backup plan is getting more expensive

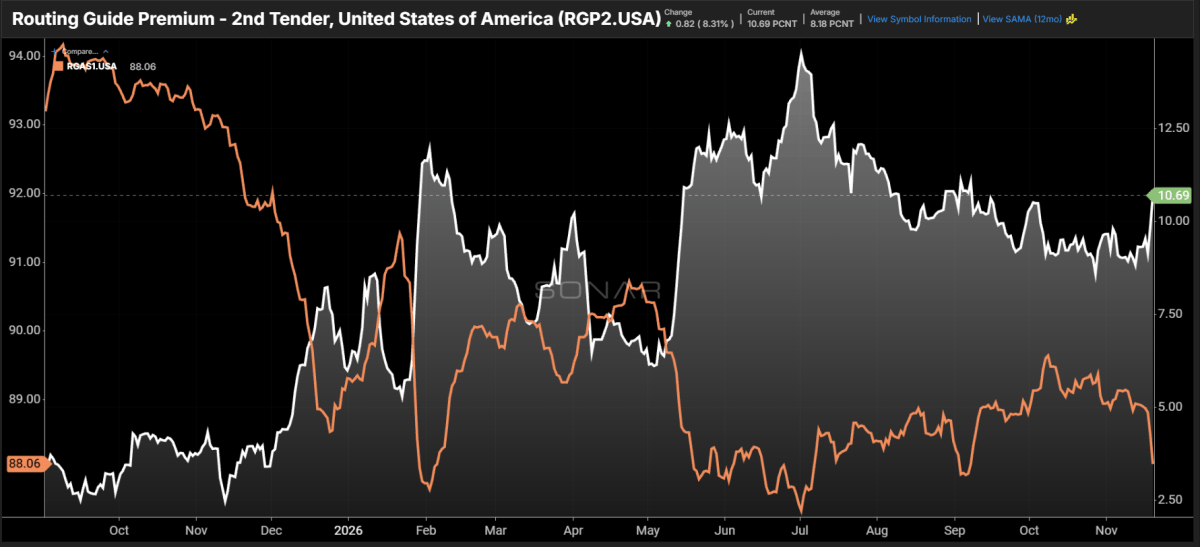
Chart of the Week: Routing Guide Premium, 2nd Tender, Routing Guide Acceptance Share for the first tender – USA  SONAR: RGP2.USA, RGAS1.USA

The price of a rejected tender jumped this week. SONAR’s Routing Guide Premium for the 2nd tender (RGP2) climbed to 10.69% on Thursday, up 1.87 percentage points from 8.82% a week earlier and its highest reading since September. Meanwhile, the Routing Guide Acceptance Share for the 1st, or primary, tender (RGAS1) slid to 88.06%, down 88 basis points in a week and its lowest level since September.

Put simply, fewer loads are sticking with the primary carrier, and backup carriers are charging more to take them. Both moves landed in the run-up to Thanksgiving, when holiday freight typically starts to squeeze truckload capacity.

The routing guide premium measures the difference in cost between the primary carrier and the carriers further down a shipper’s routing guide. It is an all-in rate difference that includes fuel and accessorial charges.

Premiums move inversely to tender acceptance, and they tend to move slowly until they don’t. Sharp changes around holidays and market disruptions can blow up shippers’ contingency budgets.

Heading into this holiday period, shippers’ routing guides put the cost of a primary acceptance failure at around 8.8%. In about a week, that premium has jumped nearly 2 percentage points, and it will probably go higher. A year ago, a primary acceptance failure cost around 4%, and that premium expanded to around 8% by Christmas.

This rapid expansion in cost is a critical detail that many transportation managers miss when selecting providers and building routing guides. Secondary carriers typically feel the same capacity pressure as primary carriers. Because they are not a top priority for the shipper, the shipper is not a top priority for them. When the whole market is under pressure and spot rates are climbing, a carrier has little reason to haul freight below market rates for business it won’t keep once the market stabilizes.

Some of the increase comes from contract-plus pricing, in which the shipper adds an amount on top of the standard contract rate for the primary carrier. This keeps the shipper from having to turn to the spot market or ask a carrier unfamiliar with its freight to go out of its way, at a much higher cost to serve.

This premium does not show up directly in spot rates because the freight is not technically spot freight. Contract tenders have much longer lead times than spot loads, currently around 3.7 days versus roughly a single day. That often makes the contract market a leading indicator of market disruption.

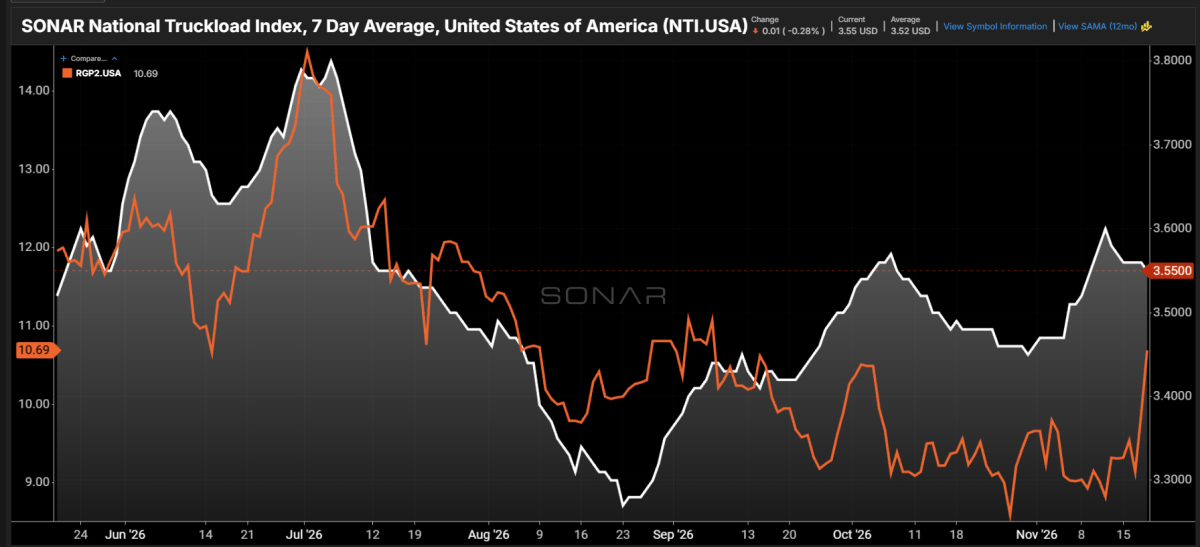
As of Thursday, Nov. 19, shippers were already feeling the pain of deteriorating carrier compliance, even though spot rates, as measured by the National Truckload Index (NTI), were flat to slightly lower week over week. When spot rates rise quickly, the spot market can also pull capacity away from contract freight.

The main lesson from this chart is that shippers’ contingency carriers are not a given when the market turns volatile. The market sets the cost of service in those periods, but that cost should still be a discussion point in bid negotiations, because the relationship has to go beyond the paper. Carriers can’t be expected to ignore the market for a shipper that values their service only when it needs a backup.

About the Chart of the Week

The FreightWaves Chart of the Week is a chart selection from SONAR that provides an interesting data point to describe the state of the freight markets. A chart is chosen from thousands of potential charts on SONAR to help participants visualize the freight market in real time. Each week a Market Expert will post a chart, along with commentary, live on the front page. After that, the Chart of the Week will be archived on FreightWaves.com for future reference.

SONAR aggregates data from hundreds of sources, presenting the data in charts and maps and providing commentary on what freight market experts want to know about the industry in real time.

The FreightWaves data science and product teams are releasing new datasets each week and enhancing the client experience.

To request a SONAR demo, click here.

Tentative union deal averts strike at Port of LA-Long Beach

The Pacific Maritime Association and International Longshore and Warehouse Union Local 26 have reached a tentative contract agreement covering about 250 watchmen at the ports of Los Angeles and Long Beach, averting an immediate strike threat at the busiest U.S. trade gateway.

The agreement, under federal mediation, remains subject to ratification by Local 26 members. The existing contract will be extended while that process proceeds, the PMA said.

In its announcement, the employers’ association thanked the Federal Mediation and Conciliation Service, the U.S. Department of Labor and Local 26’s bargaining committee for their work. It said the agreement would provide greater certainty for the ports, cargo owners, supply-chain workers and the regional and national economies.

No terms or timeline for ratification were disclosed.

The tentative settlement follows more than a year of bargaining. The previous contract expired in July 2025, and subsequent extensions allowed negotiations to continue. The latest deadline had been set for 12:01 a.m. Nov. 21, raising the prospect of a walkout if the parties failed to reach a deal or agree to another extension.

Union members had authorized a strike in late October. Federally mediated negotiations resumed Friday after an earlier bargaining session ended without a breakthrough.

Before the settlement, PMA said its offer included a $3,200 one-time bonus and wage increases that would lift average annual earnings for full-time watchmen from more than $170,000 to $198,000. The employers’ proposal also included continued fully employer-paid healthcare for active workers and retirees and higher pension benefits.

FreightWaves has reached out to Local 26 for comment.

Local 26’s watchmen provide security at six container terminals across the two ports. Their duties include controlling terminal-gate access, conducting security patrols and reporting safety issues.

There were concerns that cargo operations would be disrupted if other union workers honored watchmen picket lines.

PMA has said Local 26 represents roughly 2% of ILWU workers at the two ports.

Why it matters: The agreement reduces the immediate risk of a labor disruption at the nation’s busiest container port complex, where interruptions could affect cargo owners and businesses throughout the supply chain.

Read more articles by Stuart Chirls here.

Read more:

Zim Q3 profit surges to $830 million as freight rates jump 55%

Ship pilot indicted after fatal Houston collision linked to cellphone distraction

LA-Long Beach port strike risk grows as employers say ILWU talks stalled

Maersk and Hapag-Lloyd restore Asia-Europe Suez routes as U.S. shippers watch capacity and costs

Red Sea overcapacity looms as ocean container spot rates still 50% above year-ago 

DHL Express makes customs clearance easier for small cross-border shippers

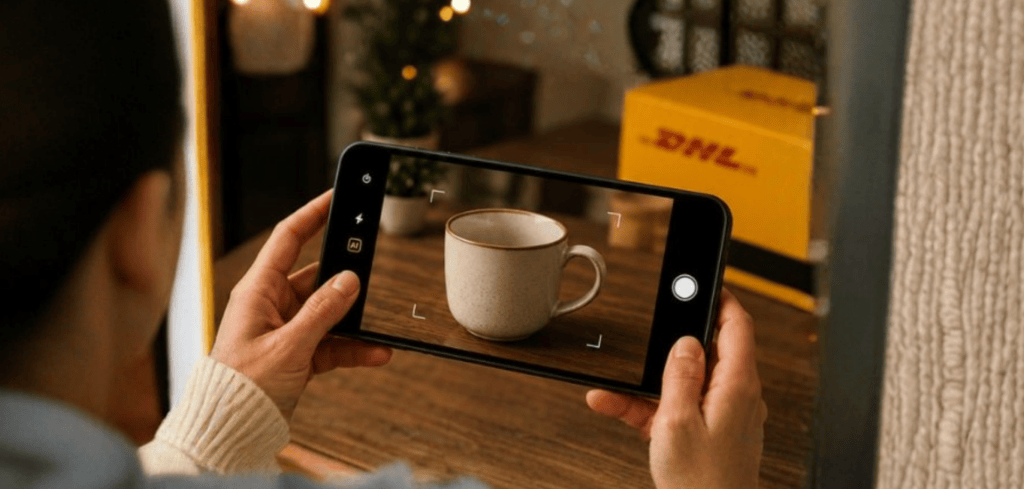
An individual uses a smartphone to take a picture of a product.

Small businesses shipping goods to overseas customers are the primary beneficiaries of a new AI-powered tool developed by DHL Express that simplifies product classification required on customs declarations and ensures descriptions are accurate.

The parcel and freight transportation company said last week that its smart identification capability is now available in the United States and a handful of other countries in the Americas.

The launch marks the first time AI-powered item identification has been integrated at scale into a live, customer-facing international express booking process, according to DHL Express.

Other freight management firms are also offering ways to ease customs compliance burdens for customers. Flexport, for example, this year added an AI classification tool to its customs software suite that generates a suggested tariff code. FedEx and UPS have digital trade tools designed to help customers review tariff code classifications and other document requirements, and accurately include duty calculations at checkout from online stores, but they don’t use AI to essentially replace a complex task the way DHL does with photo identification. 

Every item in a package needs an adequate description on the customs form so customs authorities can assess duties, check compliance and clear goods. Shippers are required to state what the item is, what it is made of and its intended purpose. 

Inaccurate or incomplete item descriptions are a common cause of customs delays and shipment holds. The new capability uses advanced computer vision to analyze a customer-generated photo of an item and instantly generate a structured, customs-compliant description, with the goal of improving data quality and reducing the potential for customs delays.

“For many businesses, one of the most challenging parts of international shipping is simply describing what they are sending to meet regulatory requirements,” said Greg Hewitt, CEO, DHL Express U.S., in a news release. “With AI-powered item identification, we’re taking the guesswork out of that process. Customers can simply take a photo and get a customs-compliant description in seconds, making it easier to get shipments right from the start and move them across borders with greater speed and confidence.”

The capability is particularly valuable for small and medium-sized enterprises , which represent approximately 86% of DHL Express customers in the U.S. Unlike larger companies that may have dedicated customs and trade compliance specialists, smaller businesses often have fewer resources to navigate complex international shipping requirements. As more SMEs explore international markets, the need for simple, intuitive tools to help them get shipments right from the start continues to grow. The number of small businesses in the U.S. using DHL Express for exports has increased 6% year over year, underscoring the opportunity to make international shipping more accessible.

The capability is particularly relevant as U.S. businesses expand trade with China, Hong Kong, Canada and Australia, and across growing sectors including e-commerce, manufacturing, automotive and fashion.

DHL said using the capability is simple. Customers photograph an item with a standard smartphone or connected device, and the AI system identifies the object and generates a structured description within seconds. Customers can review, edit or override the suggested description before submitting their shipment. No DHL Express account is required.

The U.S. is one of 10 markets in the Americas where the capability is now live, joining Brazil, Canada, Chile, Colombia, Costa Rica, Ecuador, Guatemala, Mexico and Peru.

The launch is part of ongoing investments by DHL in digital technologies aimed at facilitating international shipping tasks. DHL said the new capability will be rolled out to more markets in 2027. 

The DHL Group generated revenues of approximately 82.9 billion euros, equivalent to $91 billion in 2025. During the third quarter, DHL’s revenue increased 12.6% year over year to $25.4 billion. 

DHL calls out air cargo contribution to 16% Q3 profit gain

J.B. Hunt broker liability case proceeding after split decision

The brokerage arm of J.B. Hunt won one and lost one in an Arizona federal court Thursday in what now is shaping up to be one of the key cases on broker liability as the industry moves to a new legal landscape following the decision in Montgomery vs. Caribe Transport II.

The U.S. District Court for Arizona accepted one J.B. Hunt request for summary judgment in the case of Crystal Gee et. al. vs. J.B. Hunt et. al. But it rejected another. 

Plaintiff Crystal Gee is the guardian of the children who were injured in the crash and left without their parents in the fatal crash that is the subject of the lawsuit.

The tragedy that led to the lawsuit occurred in October 2023. A truck driven by Shokhijakhon Bekmuradov, an employee driver of carrier Borderlanders Inc., crossed into the lane of oncoming traffic on U.S. Route 160, a two-lane highway.  However, according to the recap by Judge Stephen McNamee, Bekmuradov did not immediately return to his normal lane. 

A car heading the other way and carrying Gregory Cox, his partner Lindsey Watson, and their three children came around a corner. That car collided headon with Bekmuradov’s truck. Cox and Watson were killed and the three children were seriously injured, according to the recap. 

The load was being shipped by medical equipment supplier Lincare which had hired J.B. Hunt’s brokerage arm to move its products. It was going from Denver to Phoenix, according to the recap. (The price of the load: $1,350). Borderlanders booked the load off the J.B. Hunt online broker’s platform.

Two requests for dismissal

J.B. Hunt requested summary judgment in its favor on two grounds. It sought a dismissal on the plaintiffs’ charge that it was vicariously liable for the driver’s actions and that Bekmuradov was a “statutory employee” of J.B. Hunt. It also sought dismissal on the plaintiffs’ charge that J.B. Hunt’s hiring of Borderlanders was negligent.

The carrier/intermodal/brokerage giant was successful on the first request. But it was not successful on the second request, and the case will go forward.

J.B. Hunt (NASDAQ: JBHT) declined comment on the case, citing the ongoing litigation.

The original defense put up by J.B. Hunt originally relied on the Federal Aviation Administration Authorization Act (F4A) and its prohibition against state action that might impact a “price, route or service.” In its initial response in the case, which the plaintiffs had first filed in March 2024, J.B. Hunt also said it could not be brought into the action as a broker because the safety exception to F4A, which does allow state action on safety-related incidents if they are “with respect to motor vehicles,” didn’t include brokers.

But that defense died with the ruling in Montgomery, forcing J.B. Hunt to find different approaches. 

Where J.B. Hunt failed in its argument, allowing the case to proceed, is Judge McNamee’s ruling that the plaintiffs “have presented sufficient evidence in which a rational jury could find that J.B. Hunt knew, or should have known, of the safety risks associated in selecting Borderlanders to transport the Load.”

The plaintiffs had argued that Borderlanders had a problematic past.  In an earlier filing, it said the carrier had a “history of hiring inexperienced and incompetent drivers that put the motoring public at risk of catastrophic injury or death.” They said J.B. Hunt should have known that when it hired Borderlanders.

Borderlanders is not part of the action before the Arizona federal court. According to the judge’s decision, the carrier has settled with the plaintiffs and an action against Bekmuradov was dismissed voluntarily with prejudice, ending the case.

That fact is part of the J.B. Hunt argument against the negligent hiring claim. “J.B. Hunt contends that there remains no underlying tort claim against Borderlanders so Plaintiffs cannot prove an essential element of their negligent hiring claim against J.B. Hunt,” Judge McNamee writes in his summary. 

Carrier’s safety record

J.B. Hunt, according to the judge, has said the plaintiffs have not provided evidence that Borderlanders had a checkered past. But the judge didn’t accept that. 

“Plaintiffs cite evidence that J.B. Hunt never reviewed Borderlanders’ publicly available accident and crash history, and FMCSA safety scores, safety assessment alerts, and inspection violation history before selecting Borderlanders,” the judge writes. 

And he agreed. “There remain factual disputes regarding Plaintiffs’ negligent hiring claim against J.B. Hunt, therefore, the Court denies J.B. Hunt’s Motion on this claim,” Judge McNamee wrote.

What the court accepted

On the J.B. Hunt request for summary judgment that was granted by the court, the company’s argument, according to the judge’s filing, is that it was “not liable under the federal leasing regulations because there was no lease between J.B. Hunt and Borderlanders.”

The court agreed with that view. “In this case, it is undisputed that Borderlanders transported the Load under its own authority using its own equipment and driver,” the judge wrote. “Based on the undisputed material facts, J.B. Hunt did not lease equipment to Borderlanders. Thus, there is no lease, and the federal leasing regulations are inapplicable.”

Those regulations that might have held J.B. Hunt vicariously liable “apply only if there is a valid lease,” according to the decision.

View from an outsider

Gregory Reed, a partner at the law firm of Hanson Bridgett and head of its transportation practice, said in an email to FreightWaves that J.B. Hunt’s arguments were “common refrains in the broker and logistics industry.” But he also described them as “unavailing.”

Reed summed up J.B. Hunt’s arguments. 

One, according to Reed, was that “Borderlanders remained a FMCSA-authorized (albeit unrated) carrier thus brokers should be free to use such carriers insulated from negligence.”

That goes to the heart of what numerous industry officials have argued in the wake of Montgomery: brokers lack guidelines on what steps they need to take to protect themselves against negligent hiring claims in a lawsuit. 

That was particularly stark in the recent Texas nuclear verdict against C.H. Robinson, where it was hit with a more than $600 million verdict despite the carrier it hired in the 2021 wreck that led to three deaths had a Satisfactory rating from FMCSA.

That question of what constitutes sufficient vetting is not as clear in the J.B. Hunt case, since Borderlanders, according to numerous references in the lawsuit’s various briefs, did not have a stellar safety record. 

Reed said the second argument by J.B. Hunt was that “Borderlanders’ safety and performance record was insufficient to provide JB Hunt notice because negative incidents were few compared to the carrier’s number of drivers and volume of loads.”

With enough of J.B. Hunt’s arguments rejected that the case will proceed, a jury may be the next step to take up the issue.

“Both (J.B. Hunt) arguments go to the duty of care a company like JB Hunt is required to exercise based on what it should have known, and their failure at this stage in the case demonstrates that courts may be unlikely to take these cases out of the hands of the jury to determine reasonableness,” Reed said.

More articles by John Kingston

SCOTUS action revives shipper/receiver liability post-Montgomery

Denial of funds to NY over non domiciled CDLs overturned: appellate court

DOL sticks with independent contractor proposal, trucking applauds

Groundtruth launches AI platform to automate freight billing with J.B. Hunt partnership

Groundtruth, a startup developed through J.B. Hunt Transport Services’ venture-building partnership with Vantora, launched an artificial intelligence platform designed to automate freight billing validation and reduce invoice discrepancies across the transportation industry, the companies announced on Monday, Nov. 16.

Founded in 2024, Groundtruth is a Nashville-based startup with fewer than 50 employees led by CEO Alex Rustioni. The company is an independent business spun out of the venture studio operated by J.B. Hunt and Vantora, formerly UP.Labs. J.B. Hunt has served as a collaborative design partner for the past two years, while Groundtruth received funding from UP.Partners, according to a company spokesperson.

The platform is designed to reconcile information spread across different systems, including commercial agreements, shipment records, emails and operational documents. It is aimed at carriers, freight brokers and freight forwarders.

The launch comes as transportation companies continue to work through the back-office challenges associated with manual invoice processing. A December 2025 survey FreightWaves conducted with OTR Solutions found that 54% of freight brokerages described their accounts payable processes as mostly automated, but only 2% reported full automation. On the accounts receivable side, just 2% reported full automation, while 43% said their processes remained partially automated with numerous manual steps.

Invoice discrepancies are also a concern for shippers. A 2026 survey of less-than-truckload shipping professionals conducted by MyCarrier, a provider of LTL shipping software, and research firm Mastio & Company found that 67% of respondents identified disputing carrier overcharges as the most difficult or time-consuming part of their freight audit and payment process. Nearly 20% said manually comparing freight bills with bills of lading was their biggest challenge.

Groundtruth is intended to address the validation process before an invoice reaches a customer, rather than focusing on payment processing itself. The platform brings together information from transportation and finance systems, contracts and customer communications to check whether an invoice reflects the agreed terms.

Fuel surcharges are one example of the charges that require verification. Carriers typically calculate them using a contractually agreed surcharge schedule tied to the U.S. Department of Energy’s weekly average diesel price. Applying the wrong weekly price or an incorrect surcharge schedule can result in a billing discrepancy.

“When it finds an exception, it shows the customer experience team the evidence behind it. A person with context on that customer’s rates and agreements can then review it and decide whether to make a correction,” Rustioni said.

Groundtruth is close to 100% deployed across J.B. Hunt’s internal departments and is already being used daily.

The platform is also commercially available to other carriers, brokers and freight forwarders, though the company did not identify any external customers or disclose how many invoices it has processed.

Groundtruth uses a cost-to-serve pricing model, charging customers a few dollars for each invoice the platform impacts, according to a company spokesperson. The company said the model delivers a fourfold to sixfold return for customers but did not provide supporting calculations or disclose how many invoices it has processed.

Groundtruth is the second startup announced through J.B. Hunt’s partnership with Vantora, The first, Overroute, launched in July with an AI-powered freight execution platform. Billing was among the problems J.B. Hunt and Vantora weighed early on, including reducing billing complexity, before they chose load execution for Overroute.

The partnership is focused on developing startups to address operational challenges in transportation and other essential industries. Groundtruth’s launch extends that effort into freight finance and back-office operations.

Why this matters:

Freight billing errors and manual invoice reconciliation can create administrative costs, delay payments and lead to disputes between carriers, brokers and shippers. As transportation companies look to automate back-office operations, tools that validate charges against contracts, shipment records and fuel surcharge schedules could reduce manual work and improve billing accuracy.

Trucking Rejection Rates: Why Holiday Shipping Gets SPICY

FreightWaves SONAR data reveals early signals of a tightening market ahead of Thanksgiving. Historically, this period sees a slight increase in tender rejection rates. This year, expect a significant jump potentially pushing rates over 14% as low inventory levels drive last-minute shipping demands. Coupled with potential port strikes, capacity could become extremely constrained in certain regions.

Truckload tender rejection rates jumped back toward 13% in the days leading up to Thanksgiving, and Zach Strickland of SONAR is forecasting a further climb to roughly 14% over the following week as holiday capacity pressures intensify. The move matters for carriers, brokers, and shippers because rejection rates signal how much pricing power carriers hold — and how difficult it will be to cover loads at contracted rates.

Strickland said demand signals, as measured by the tender volume index, remain underwhelming heading into the holiday. That is not unusual. “We call it peak season because capacity gets tighter,” he said. “You lose a lot of drivers, they get boundaried around 500 miles, and the larger fleets — you’ve got to convince these guys to get on the road during the holidays when they want to be home with their family. So a premium comes with that.”

“So spot rates start to take off. So the tender volume index in white there, it really never gets going until like a few days in front of Thanksgiving. And that’s really a lot of tenders that are getting pushed out for after the break.” — Zach Strickland

Two compounding factors could push rejection rates and spot rates higher than seasonal norms. Strickland noted that inventory levels heading into the holiday are not as robust as typical, raising the risk of last-minute shipping activity. A potential port strike was also cited as a source of shipper anxiety over freight positioning, though Strickland said a resolved strike would likely produce only a modest bump — with more meaningful rate movement expected closer to Christmas.

On the spot rate side, Strickland was more emphatic about upside risk. The van spot rate index, along with refrigerated and flatbed rates, have already seen some elevation this month. Diesel prices are declining, so fuel is not the driver. “This is not a fuel-related situation,” Strickland said. “We’re seeing actual elevation and already elevated rates on all three modes.” He added that ad hoc and transactional freight hitting the spot market in the coming weeks makes a downward trend unlikely — and noteworthy if it occurs.

Regionally, the weighted rejection index — which accounts for volume — is flashing week-over-week increases in the Midwestern corridor including Iowa, Kansas, and Topeka, as well as Phoenix and Gulf Coast markets such as New Orleans and Mobile. Because these are lower-volume markets, the blue signal on the weighted rejection index map carries outsized significance for capacity availability.

The Pacific Northwest is another area to watch. Strickland pointed to heavy freight inflows at the ports of Seattle and Tacoma from shippers diverting cargo to avoid Los Angeles congestion, combined with atmospheric rivers hitting the West Coast and snow in the Rockies and Cascades. Low freight density in mountain and prairie regions makes loads harder to cover, adding to rate pressure in those lanes. Temperature-controlled freight rounds out the concern, with refrigerated rates elevated on the West Coast even as the reefer market’s true seasonal peak typically arrives in January.

  • Tender rejection rates climbed back toward 13% ahead of Thanksgiving and are forecast to reach roughly 14% the following week.
  • Spot rates are already elevated across van, refrigerated, and flatbed modes, with the increase driven by capacity tightening rather than fuel costs.
  • Pacific Northwest ports, mountain corridors, and low-volume Gulf Coast and Midwest markets are the regional hotspots to monitor for capacity constraints.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Q3 Shipping Costs Down 3.3% – Where Did The Savings Go?

Carrier rates fell last quarter, but operators barely felt the savings. Eric Lemus from Deposco breaks down the unexpected disconnect in Q3 shipping costs. A shift to heavier packages, faster service, and residential deliveries meant higher per-package costs, offsetting carrier rate reductions. Learn why operators focused on customer satisfaction and how these trends will impact Q4 peak season with potential stockouts and increased overall shipping expenses.

Carrier rates dropped 3.3% per package in the third quarter, but operators captured just 0.6% of that reduction in actual savings, according to Commerce Signal data analyzed by DePascos. The gap stems not from contract rate negotiations but from a fundamental shift in what shippers actually put in the mail stream — heavier boxes, premium service levels, and a greater share of residential stops.

“What we saw in Q3 was heavier packages, faster service levels, and more residential deliveries,” said Eric Lemus, vice president of strategy and analytics at Deposco. He added that sub-5-pound package costs did decline, but volume surged in the 11-to-20-pound weight tier, wiping out much of that relief. Consumers driving the mix shift appear to be consolidating orders to chase volume-based discounts, putting more of the same products into each shipment.

Despite soft consumer sentiment readings, gross merchandise value growth closed Q3 up 11.7%. Lemus argued that survey-based sentiment measures have diverged from observed spending behavior for roughly two years and urged operators to anchor forecasts to actual order volumes rather than sentiment indices.

“Don’t rely 100% on those consumer sentiment surveys. Look at your actual order volumes, look at your actual demand, and make a decision going forward based on that to forecast your business because there’s noise — there can be noise in the data around consumer sentiment surveys,” Lemus said.

Inventory management adds another layer of risk heading into peak. Brands entered the season carrying roughly 94 days of inventory while third-party logistics providers held only 91 days. Lemus said that gap, combined with accelerating sales velocity, makes stockouts a central risk for Cyber Week and the broader Q4 period. Restocking picked up in the final two weeks of September, but Lemus believes operators ordered too late to fully cover Q4 demand.

The 3-day inventory advantage brands hold over 3PLs matters most for geographic positioning. Brands relying on 3PL partners for geographic diversity risk holding stock in the wrong locations, forcing them to pay elevated expedited-service rates to fulfill orders across longer zones. “You have one facility that’s a stockout and you have an order in that geographic location, but to fulfill the order … operators [are] paying higher service delivery rates,” Lemus said, predicting that dynamic will compress profit margins even if revenue growth remains strong.

Looking ahead to Q4, Deposco is tracking four primary signals: fewer new orders paired with slightly larger basket sizes; rising peak shipping costs relative to Q3; continued fuel-surcharge volatility that is shifting on nearly a daily basis; and inventory drawdowns driven by sales velocity. On the carrier side, Lemus recommended operators deploy at least two to three carriers to offset rate pressure, noting that alternative carriers outside the major four are increasingly fulfilling orders as shippers diversify.

Overall, Lemus said indicators point toward a solid but not outsized fourth quarter. He attributed lean inventory levels to higher interest rates making capital-intensive stock less attractive rather than to any expectation of weaker demand — a distinction he said operators should weigh carefully as the holiday selling season accelerates.

  • Q3 carrier rates fell 3.3% per package, but shipment mix shifts — heavier weights, faster services, more residential stops — left operators with only 0.6% in realized savings.
  • Sales GMV grew 11.7% in Q3 despite weak consumer sentiment surveys, underscoring a two-year divergence between observed spending and survey-based indicators.
  • Brands held 94 days of inventory vs. 91 for 3PLs entering peak, raising stockout risk and likely pushing Q4 shipping costs higher as operators pay premium rates to fulfill mislocated stock.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Industrial Demand Is Broadening. So Is Competition for Space

For much of the past few years, industrial tenants had the luxury of time. Options were plentiful, negotiations dragged and “let’s see what else is out there” was a viable strategy. That window is narrowing.

In a recent market update conversation with Thomas Wasson, Brandon Page, executive vice president and head of leasing and customer solutions at Link Logistics, described a market where demand is building, competition for space is returning and the criteria that decide a lease are shifting. Link Logistics is one of the largest owners and operators of last-mile industrial real estate in North America, with nearly 500 million square feet across the U.S. and Canada. Page oversees portfolio leasing strategy and works closely with its largest customers, which gives him a front-row view of what occupiers want.

For carriers, 3PLs, shippers and anyone else whose network depends on where buildings sit and how they perform, his read is worth a close look.

Demand Is Broadening

Page said demand has built steadily for months. “I would say demand has consistently accelerated throughout the year,” he said, adding that the momentum began toward the end of last year and has continued.

He sorted the drivers into tiers. The most dominant is the AI data center ecosystem, which generates activity during construction and again during ongoing maintenance, alongside advanced manufacturing and reshoring investments that are starting to come online. “We want to own the buildings that are adjacent to [the data centers] to help support those facilities,”Page said.

The second tier is the bread-and-butter freight demand: e-commerce and omnichannel distribution, which follows the consumer and the push toward same-day and next-day delivery. Third-party logistics providers, historically Link Logistics’ largest occupiers, continue to move steadily. Page also pointed to cold storage and to defense and aerospace as specialty segments with new momentum, citing a recently announced Anduril investment likely to affect markets such as Baltimore.

Fast Movers Win

Even as demand builds, Page said tenant decision-making is still deliberate. Customers and their brokers take time to understand a facility and all of its costs. But the dynamics are changing. “We are starting to see situations where we have multiple customers and prospects going after the same building,” he said, noting it’s something Link Logistics saw regularly during COVID.

The implication for occupiers is clear. “Those that are moving quicker are having better success than those that are sort of paralysis by analysis,” Page said.

That message extends to the brokers who represent those tenants. The market remains fairly balanced, he said, but there are more tailwinds than headwinds for landlords heading into year-end than a year ago. Brokers need to prepare clients for rents that will change as markets tighten. “The days of having five or 10 options in a market are gone, and they may have one or two,” he said.

Data Centers Move From Footnote to Force

A couple of years ago, data center-related leasing was a very small part of Link Logistics’ activity. Now it’s a meaningful share. “15% of Link’s new leasing activity over the past year is tied to data centers,” Page said.

He offered a rule of thumb for the scale of the spillover. “Each gigawatt of data center capacity generates roughly 2 million feet,” he said. “We actually think in some cases it’s closer to 2.5 million feet of associated demand.”

Just as important for landlords is how long that demand lasts. Page said 80% of data center-driven demand is long term, with tenants that help stand up facilities and then stay on for ongoing maintenance. The other 20% sign two- to three-year leases focused on setup. “Which is a good tailwind as well for industrial,” he said.

Balancing Scale and Proximity

Two trends in building size can look contradictory but reflect the same goal of efficiency. For large users, Page described “a clear trend of consolidating those 200,000 to 400,000 square foot buildings,” sometimes folding two or three of them into a single facility of about 1 million square feet. Running three buildings means three sets of capital investment and management teams, he said, “just three times the work.” Class A buildings, with their cubic efficiency, tend to lease first.

For last-mile and omnichannel users, the equation flips toward proximity. Link Logistics’ portfolio is largely multi-tenant infill space close to customers, and in those cases, Page said, location can matter more than state-of-the-art specs. “You can’t beat location and access,” he said. Big retail customers are working to get as close to consumers as possible, sometimes delivering in as little as 30 minutes. Whether an order ships from a store or a warehouse, he said, the answer is increasingly “all the above.”

3PLs play a particular role in this environment. Page called them “the fastest way to stand up or modify your national supply chain network,” with less capital tied up than a company standing up its own facility. Large national 3PLs can reposition their portfolios as client needs change.

The New First Question: How Much Power?

If one shift stood out from Link Logistics’ customer advisory council, a roughly 15-member group of the heads of real estate at some of its largest occupiers, it was power. Page said the traditional priority list once ran labor, transportation costs, then rent. Today, “clearly power is the number one driver.”

The numbers show why. A 400,000-square-foot building once came with a 2,000-amp panel. “The new baseline is roughly 4,000 amps,” Page said. Tenants may not use it all on day one, but they’re planning for fleet electrification, extensive material handling and robotics.

The key, he said, is that tenants don’t necessarily need the power immediately. “They don’t necessarily need to have power today, but they need to have a path to power.” They want to know how much capacity is possible and how long it will take to get there, whether six, 12 or 18 months, so they can use other facilities in their network to compensate in the meantime.

Page said some searches now open with the question before any other building attribute is discussed. “‘How much power does it have?’ is line item one,” he said. Square footage and location follow.

Automation: Talked About More Than Deployed

For all the attention on warehouse robotics, Page offered a reality check. “Less than 5% of our facilities actually have automation in there,” he said. Only a handful of Fortune 100 companies can afford the infrastructure and also have the volume to justify it. Costs are falling and systems are becoming more modular, but “it’s still very cost prohibitive for many customers at this point.”

Perception of utilization varies, too. One customer may call a 40-foot-clear building full when product is floor-stacked, while another operating multiple levels of material handling may call itself 90% utilized. It depends, Page said, on the business, the throughput and the technology investment.

Deal Flags: Credit, Term and Flexibility

Asked about red and green flags in closing a deal, Page started with a short rule. “Credit’s king,” he said. A building’s value is tied to the underlying credit and the quality of the rent stream, and short terms on a building that takes significant time to stand up are another warning sign. On the positive side, he points to good-credit tenants investing real capital in a facility, which signals it’s a key part of their network and likely to stay.

For tenants, especially smaller companies where rent is a bigger share of total cost, Page cautioned against focusing only on the face rate. They should ask what capital improvements may be needed and whether the owner can accommodate change. An owner with 50 buildings in a market can offer more room to grow or relocate than one with a single facility. “Make sure you’re partnering with somebody that’s flexible,” he said.

The growth of smaller e-commerce brands and shifts such as the Amazon–UPS breakup on small parcels may also create openings for local and regional 3PLs, Page said.

What to Watch Next

Looking out six to 12 months, Page flagged two open questions. The first is data centers: the election outcome may change sentiment in certain markets, and it remains to be seen how investment from large data center companies plays out. The second is the consumer. Warehouse occupiers aren’t as exposed to interest rates as homebuyers are, he noted, so employment and the underlying health of the economy matter most. When people are employed, they buy more, and Link Logistics’ customers take more space to deliver it efficiently.

That dynamic, Page said, becomes a flywheel as one retailer’s gains force others to follow, “a race to speed,” in his words, that means “you just have to be in a lot more locations and as close to the customers you possibly can get.”

For freight and logistics leaders, the takeaway is practical. Evaluate sites earlier, ask about power first and be ready to decide faster, because the other tenant may already be touring the building.

Mexico tightens trucking oversight with new digital compliance rules

Mexico has introduced new requirements for commercial trucking companies seeking voluntary federal certification.

The new program places greater emphasis on digital monitoring, vehicle weight compliance and internal operational controls as the country works to strengthen highway safety and regulatory oversight.

The Ministry of Infrastructure, Communications and Transportation (SICT) published the new requirements Thursday, Nov. 19, in Mexico’s Official Gazette of the Federation. The notice took effect Friday, Nov. 20.

The framework establishes procedures for trucking companies to obtain approval under a self-regulation program known as Autorregulación (Permisionario Responsable con el Cumplimiento de la Norma), or Responsible Permittee for Compliance with the Standard.

The program operates under Mexico’s NOM-012-SCT-2-2017 regulation, which governs maximum vehicle weights and dimensions on federally regulated highways.

Although participation is voluntary, companies seeking certification must demonstrate that they have implemented internal systems capable of ensuring compliance with federal transportation requirements.

The initiative represents a shift toward recognizing carriers that can document their own compliance practices rather than relying exclusively on government inspections.

According to the SICT, the objective is to improve highway safety, reduce operational risks and make vehicle inspection and verification procedures more efficient.

The program applies to federally permitted general freight carriers and private freight transportation operations.

Digital monitoring becomes central to compliance

One of the program’s most significant elements is the emphasis on electronic documentation and internal monitoring systems.

According to an executive guide issued by Mexico’s National Association of Private Transport (ANTP), participating companies must maintain a permanent digital system capable of recording shipment information in real time and making those records available to federal transportation authorities.

Carriers can qualify through two principal compliance mechanisms: using their own weighing equipment to verify cargo weights or implementing standardized loading procedures that consistently meet federal weight and dimension limits.

Companies may also combine both approaches.

The requirements place greater responsibility on carriers to verify that trucks meet applicable limits before entering federal highways.

For larger trucking fleets, this could mean integrating weighing systems, dispatch operations, shipment documentation and compliance reporting into existing fleet management platforms.

For smaller carriers, however, adopting and maintaining the necessary technology and administrative processes could create additional expenses.

The SICT notice also authorizes federal authorities to recognize weighing results generated by carriers’ own scales or by operators demonstrating consistent loading procedures.

How trucking companies can obtain certification

The SICT’s General Directorate of Federal Motor Transport (DGAF) will oversee the approval process through its Executive Directorate of Supervision.

According to the ANTP’s guidance, applicants must complete a five-stage process involving documentation, regulatory review and verification.

Companies must first assemble the required application documents and submit them to the DGAF. The agency then reviews the documentation and conducts an inspection visit before the applicant presents the required guarantee and receives final approval.

Approved carriers will receive official identification for participating vehicles.

The ANTP said certification and the corresponding vehicle identification will remain valid for three years, subject to continued compliance.

Vehicles participating in the program must display their license plate numbers in the prescribed manner and carry an official certification identifier.

Carriers must also maintain updated information concerning their vehicles, operating permits, business addresses and changes to their loading or compliance procedures.

The program’s requirements and application procedures are available through the DGAF’s official self-regulation portal.

Random inspections and penalties remain in place

Despite the program’s emphasis on voluntary compliance, Mexican authorities will retain the ability to inspect participating trucks.

The SICT said inspections may be conducted at fixed weight and dimension verification centers or through electronic monitoring devices deployed by federal authorities.

Carriers that violate applicable weight, dimension or safety requirements remain subject to penalties under Mexico’s federal transportation laws.

According to the ANTP, exceeding weight or dimension limits more than three times within a year, measured from the first violation, can result in revocation of certification.

Other violations of the program’s operating guidelines may also lead to revocation.

What the changes mean for Mexico’s trucking industry

The new framework could have significant implications for Mexico’s commercial trucking industry, particularly as carriers face growing pressure to improve safety, operating efficiency and supply chain visibility.

Companies with established fleet management technology, weighing infrastructure and compliance departments may be better positioned to obtain certification.

Those operators could benefit from greater predictability in vehicle verification processes and potentially fewer administrative delays associated with demonstrating compliance.

Smaller carriers and independent operators, meanwhile, may face greater challenges meeting the program’s digital documentation and procedural requirements.

The framework could also encourage greater investment in fleet management software, electronic shipment records, weighing technology and standardized loading systems.

For shippers, the certification program could provide an additional way to evaluate carriers’ operational controls and commitment to regulatory compliance.

The initiative also comes as Mexico’s trucking industry faces broader challenges involving highway security, operating costs and government enforcement.

Why it matters: Mexico’s transportation ministry’s expanded trucking compliance framework program could accelerate the adoption of digital compliance systems across the country’s trucking industry while creating new operational and administrative demands for carriers.