Crosswinds threaten soft landing
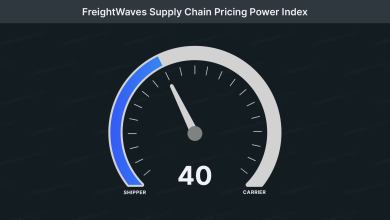
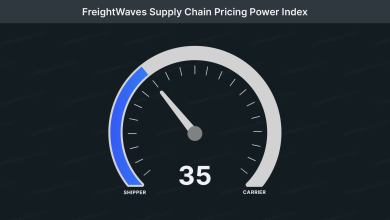
The sustained imbalance between supply and demand has yet to be corrected, such that only an unprecedented tidal wave of demand could satisfy the current amount of capacity in the national freight economy.
Pace of carrier exits needs to speed up to achieve economic balance in the truckload sector, according to RXO Chief Strategy Officer Jared Weisfeld.
Removing future threats to demand, the refrigerated truckload sector supports the thesis that the truckload market has hit a floor.
There are some positive signs that the freight market has cleared most of the post-pandemic rubble, but full recovery is still a ways off.
Falling spot rates, falling contract rates and falling revenues create rising stress and blood pressure in truckload operations teams.
Strangely enough, tender volumes are abiding by seasonal trends. The first quarter of 2022 was unusually active as shippers tried to get ahead of disruptions to capacity, which historically tightens in the spring.
With the inflation-squeezed consumer running through their discretionary budgets, freight demand is in a precarious state.
Consumers’ appetite for discretionary spending has been usurped in favor of squirreling away income into personal savings.
Volumes have continued their recovery from the winter holiday season with a surge in pent-up freight demand unleashed into the market. Naturally, since last week’s data was affected by holiday noise, the Outbound Tender Volume Index (OTVI) faces some absurdly easy comps on a weekly basis. Even still, accepted tender volumes remain below their levels of 2021 and ’22 for the time being.
For all intents and purposes, the month of December has only three weeks of freight activity, as the final week from Christmas to New Year’s is effectively null. In years prior, freight demand has fallen throughout the month before bottoming out in that final week. So far, December looks to be following seasonal trends, which is to say that, while shippers’ activity is winding down, this movement is not alarming by itself. Rather, the gap in freight demand between 2022 and ’21 (or even ’20) is the main symptom of current ailments.
Contrary to popular opinion, December is not a peak season for freight. True, the freight that needs to be moved in this month typically has greater urgency than usual, which does put upward pressure on carrier rates. But peak truckload volumes are largely influenced by maritime imports, which historically peak between July and September.
Historically, November is the month in which maritime imports begin to move inland for their final push before the holiday shopping season. Yet such imports were lost at sea this year, failing to materialize during ocean shippers’ peak season. This one-two punch of weakened import volumes and overstocked retail inventories means that carriers are left with fewer opportunities to source freight.
A rail strike could lift spot truckload prices and support a market that’s been soft, sources said. But should a strike continue, expect congestion and higher costs.
Historically, November is the month in which maritime imports begin to move inland for their final push before the holiday shopping season. Yet such imports were lost at sea this year, failing to materialize during ocean shippers’ peak season. This one-two punch of weakened import volumes and overstocked retail inventories means that carriers are left with fewer opportunities to source freight.
Since the pandemic started, many shippers found their existing contracts unable to ensure carrier compliance. Supply and demand were especially volatile, and so spot rates, which are more sensitive to changing market conditions, handily outpaced contract rates.
Trucking executives are hopeful the first half of 2023 brings a cycle recovery.
Since the pandemic started, many shippers found their existing contracts unable to ensure carrier compliance. Supply and demand were especially volatile, and so spot rates, which are more sensitive to changing market conditions, handily outpaced contract rates.