The ‘ingenious strategy’ behind most truckers’ least favorite week of the year: International Roadcheck

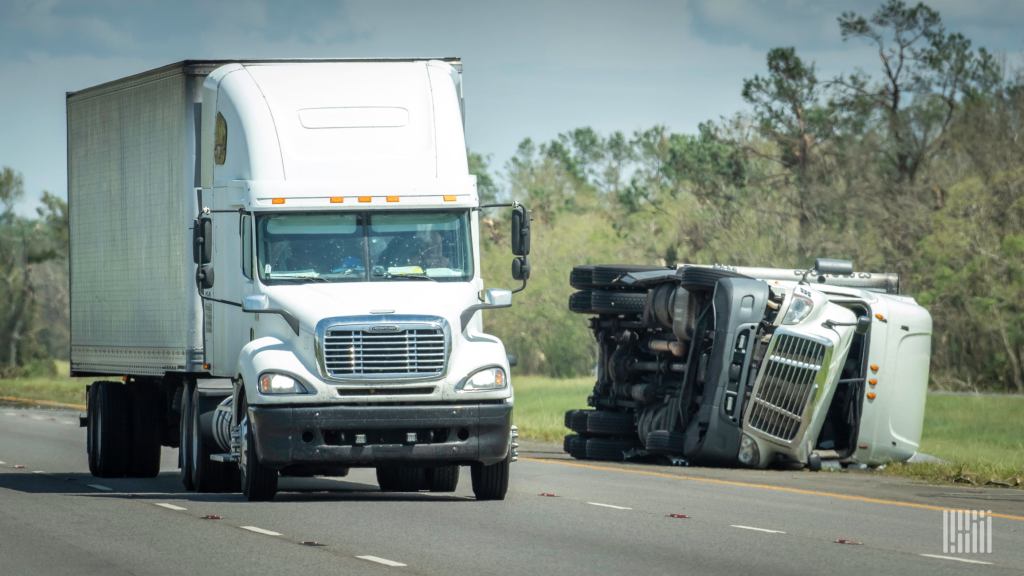
truck fallen over

International Roadcheck Week is hardly the sexiest topic in trucking, but it is a darn-tootin’ important one. Inspectors in the U.S. and Canada halt tens of thousands of trucks for vehicle inspections for a few days every summer or early fall. They remove thousands of trucks and drivers from the road; in 2021, 16.5% of inspected vehicles were put out of service along with 5.3% of drivers.

It’s uncommon for truck drivers to actually get their vehicles inspected at random during most of the year. To avoid International Roadcheck Week, many truckers simply don’t drive during that period of time — which, presumably, means more unsafe vehicles and drivers on the road outside of the inspection blitz. It’s a question that ate at Andrew Balthrop, a research associate at the University of Arkansas Sam M. Walton College of Business. 

Around 5% fewer one-person trucking companies are active during International Roadcheck Week. But Balthrop and his fellow researcher, Alex Scott of the University of Tennessee, found a major upside to the inspection blitz — even with all the folks who avoid it. According to their working paper published in March 2021, vehicles are safer a month before and after the inspection period. There’s a 1.8% reduction of vehicle violations, according to Balthrop and Scott’s analysis. Surprise inspection blitzes don’t result in the same uptick of compliance. 

I caught up with Balthrop about his research last week at FreightWaves’ Future of Supply Chain conference, and we chatted again on the phone this week about his findings on International Roadcheck Week.

Enjoy a bonus MODES and a lightly edited transcription of our phone interview: 

FREIGHTWAVES: For our readers who are not aware of what Roadcheck Week actually is, can you explain a little bit about what it and why it is important to drivers and companies?

BALTHROP: “The International Roadcheck is part of an alliance between the inspectors in Canada and the ones in Mexico and the U.S. to have a unified framework for making sure trucks are safe to operate. That should make it easier to go across borders when you have this kind of unified structure.

“In the U.S., one of these CVSA inspection blitzes is the International Roadcheck that happens for three days in the summer. Usually it’s a Tuesday, Wednesday and Thursday. And usually it’s the first week in June.

“And in it, they focus on Level One inspections, the North American Standard Inspection where they inspect the driver records, the hours of service, the licensure and I believe medical records as well. Then they inspect the truck. It’s an in-depth inspection where the inspector will actually crawl under the truck to look at various things. And these inspections, from the data that I’ve seen, take about a half an hour on average.

“During the Roadcheck Week, they’ll do about 60,000 inspections, so 20,000 a day. They’re going to pull over a lot of trucks, and this can cause a little bit of congestion at the weigh stations and the roadside inspections localities as the inspectors are doing these inspections.”

Roadcheck Week doesn’t catch all truck drivers, but it has a long-lasting benefit to safety

FREIGHTWAVES: So, can most drivers kind of expect to be pulled over? How likely is that?

BALTHROP: “There’s 1 million or 3 million trucks on the road, somewhere around there on any given day. With 20,000 inspections, most drivers still will not get inspected, but there’s going to be a higher proportion of drivers inspected. 

“You’re more likely to get inspected on these days. If you don’t have a recent inspection on your record, or if you have a bad recent inspection on your record, you’re more likely to be pulled over on these days.”

FREIGHTWAVES: Your research focused on that it’s just unusual that this inspection is announced, that it’s planned. We were talking before about how normally, if you’re trying to assure quality or compliance, you would not announce an inspection in advance. It would be more of a surprise-type situation. 

Can you walk us through why that’s so unusual, or what’s the rationale that you see behind announcing it in advance?

BALTHROP: “It is unusual, and on the surface, it doesn’t make much sense, but it turns out to be kind of an ingenious strategy. So I’ll walk through it here. 

“Over the course of a year, there’ll be 2 million inspections of 3 or 4 million trucks out there. The average rate of inspections is pretty low. It’s not uncommon for truckers to go years without having an inspection. With this low inspection intensity, the FMCSA has sort of a problem of, how does it get anybody to abide by the regulations?

“I’m a jaded economist, and I don’t worry or consider too much ethics and morality and all that kind of stuff. It comes down to incentives for drivers to follow these inspections. The incentives do guide behavior. So, how could the FMCSA incentivize drivers to follow these regulations more closely and adhere to the standards?

“They do this by announcing the blitz. This does two things. On one side, it allows everybody to prepare in advance. There’s a bunch of anecdotal evidence out there that people do prepare for these blitzes in advance. They will have their trucks inspected beforehand for any problems. They’ll time maintenance and upkeep in advance to make sure that their vehicles are in order. “They’ll be a little bit more cognizant of the driver-side regulations. One thing we notice in our study is that hours-of-service violations really drop during these extensions, because people see them coming. They don’t fudge the books in any way.”

Owner-operators can evade Roadcheck Week. Big carriers, not so much.

BALTHROP: “The issue with the announcement, on the flip side, is that it allows people to just dodge the inspection entirely. For a long time, people have talked about how owner-operators and smaller carriers time their vacations for this particular time. They could do this for a couple reasons. To avoid the hassle is a nice way to put it, but it also allows you to be noncompliant to avoid the high-intensity inspections.

“You have this balance here that on one side you get the behavior you want with people complying with regulations. That’s the behavior the FMCSA wants. But on the flip side, you get a bunch of people that are kind of outright dodging inspections.

“When you compare these two things on balance, the policy is actually pretty effective because you get a lot of people focused on maintaining their trucks and obeying the rules during that particular week. Especially with the vehicle maintenance stuff, that lasts a long time. 

“In our research, we saw that vehicle violations, a month before and up to a month afterwards, is when you still notice your vehicle violations. That trucks are kind of better maintained around these blitzes.

“The ingenious aspect of it is that the FMCSA, by concentrating their inspection resources all at one time and announcing it, they’re making it clear that they’re serious about enforcing these regulations and everybody prepares for it. For the number of inspections that are happening, you get fewer tickets than you would have otherwise expected.

“The FMCSA, they’re putting people through a little bit of a hassle, but they’re not having to write a bunch of tickets to get people to comply. They’re not really punishing a whole bunch of people because, by making this apparent that this is going to happen, people comply and the FMCSA gets what they want essentially without having to come down on carriers too hard.”

A convenient time for a vacation, indeed

FREIGHTWAVES: OK, interesting. And how does this pattern of shutting down, how does that compare for an owner-operator versus a driver for a big fleet?

BALTHROP: “If you’re a motor carrier with thousands of power units, you can’t just pack up and not do business on a particular day. They just don’t have that option. So they get inspected at a higher intensity, and you see the larger carriers kind of more focused on making sure that they’re prepared for these inspections. With so many inspections, the larger carriers are going to be inspected at higher rates. You can really damage your reputation if your equipment isn’t in order on this particular day. 

“Versus the smaller carriers, especially if you’re talking about a single-vehicle fleet, an owner-operator type, it is not that difficult to just not work for those three days. And so you see a lot about that. 

“In terms of what the roadway composition looks like, if we look at inspection data and relative to a typical day with the usual inspections, on these Roadcheck days, you have about 5% fewer owner-operators on the road than you otherwise would expect.”

FREIGHTWAVES: Wow. And when you say owner-operators, you also mean just like fleets with just —

BALTHROP: “One-vehicle fleets.”

FREIGHTWAVES: OK, that’s interesting.

BALTHROP: “You know, you see a little bit of effect with the smaller fleets, below six vehicles, but it basically disappears by the time you get to a hundred vehicles.

“This effect is being driven by smaller carriers staying off the road in terms of avoidance. You see this goes also how you would expect; it’s also older vehicles that stay off the road. This is correlated with carrier size. The larger carriers use newer vehicles and owner-operators tend to use some of the older vehicles. But it’s particularly the older vehicles that are off the road.

“This makes intuitive sense. Older vehicles are more costly to keep compliant. Maintenance is more costly, and they’ve been around longer so there’s time for more stuff to have broken essentially.

How a truck driver gets stopped for inspection

FREIGHTWAVES: Can you explain a little bit more, the idea of having this inspection history and why it would benefit a larger or small carrier?

BALTHROP: “Getting flagged for inspection is sort of random, but not totally. If somebody notices something obviously wrong with your truck, that’s ground for a more in-depth inspection. Or if you get pulled over for some other reason, this can be grounds for inspection of some type. 

“But there’s also the inspection selection service. The computer program that is random, that it randomly flags people in for inspection, but it’s based on your inspection history.

“So if your firm hasn’t been inspected recently, or if your carrier doesn’t have a very dense inspection history, you’ll be more likely to trigger that system to pull you in and have you inspected. If you have a dense inspection history, you’re less likely to get inspected.”

FREIGHTWAVES: So how do you get pulled over for inspection? As a person who only drives a passenger car, my main interaction with being pulled over is, I’m driving down the freeway or wherever, and I get stopped by the police. How does it work for a truck driver? How does getting pulled over or inspected work in that way?

BALTHROP: “The law is that you cannot pass a weigh station without pulling in and getting weighed. At that point they may flag you to be inspected. Now, in the past decade or two, there’s been a bunch of electronic devices that are installed in cabs. You may have heard of PrePass or Drivewise. This allows you to pass weigh stations. 

“I don’t have data on how many trucks have the in-cab devices. But from a trucking perspective, they’re so convenient that you don’t have to stop every time you cross a state line. I think the vast, overwhelming majority of trucks have some sort of one of these electronic devices. The DOT inspectors at these roadside inspection points have a dial they can twist essentially about how many people they want to inspect. 

“So during the roadcheck inspection week, they’ll crank that dial all the way up and pull everybody over. And if they get too backed up, they might crank it back down a little bit and so on.”

FREIGHTWAVES: OK, interesting. It reminds me of a highly sophisticated E‑ZPass.

A $10 million-plus expense to trucking companies every year … but it’s worth it if just one fatal crash is avoided

FREIGHTWAVES: Zooming out, when we hear about large truck crashes, something like a vehicle maintenance issue is not really the most sexy explanation. But just looking at the FMCSA data, in 29% of all truck crashes, a major factor is brake problems. So it seems like a lot of the truck crashes on the road are caused by vehicle maintenance, versus something like the driver using illegal drugs or some other sort of more dramatic explanation. Can you speak a little bit to why this sort of vehicle maintenance is important for safety in preventing large crashes?

BALTHROP: “We did a little bit of a back-of-the-envelope cost benefit analysis of this. Let me try and make sure I remember it clearly, but we have it in the paper that the cost of this on one side is that you have the compliance costs the firms are undertaking, and then you have to add to that the delay costs from doing this, and then the cost of the inspection itself, having to pay federal inspectors to do this.

“On the benefit side, it reduces crashes. So when we add up, just looking at the cost of what an inspection is, we don’t have a good idea of how to measure the compliance cost. It’d be fun to measure the delay cost, but I don’t have good enough price data on that to get at that cost. 

“But if you look at what the cost of an inspection is, it is something like $100 or $120 is what you would pay to have one of these inspections done privately. A lot of people do this in the run-up to inspections, and have it done privately so that you can fix whatever the problems are and be sure that you would pass the FMCSA inspection.

“With that $120 figure, if you aggregate that up to 60,000 inspections or whatever, and you take that in comparison, I’m going to give you a bad figure here, it’s on the order of $10 million. That is about the value of a statistical human life. Looking at this economically, it’s worthwhile if it saves one human life. If you identify just one faulty brake system that would’ve resulted in an accident, you’re getting some value out of the program. 

“When you add those other costs in there, we’re going to need to save a couple of lives, but in terms of cost benefit analysis with this kind of stuff, we’re usually looking at orders of magnitude differences in cost and benefits to say something for sure. 

“If you can save just a couple lives, this program will pay for itself.”

Time to start inspecting in the winter

FREIGHTWAVES: Then one last question: Is there any rationale for this program happening in the summer? 

BALTHROP: “I think part of it is that for the inspectors this gets much harder and much more miserable to do in winter conditions.”

FREIGHTWAVES: That makes sense.

BALTHROP: “Inspectors are less productive. One of the things that we talk about in the paper, that they have in addition to the International Roadcheck, is that they have Brake Week where they focus a little bit more on brake inspections. You have Operation Safe Driver a little bit later on in the summer, usually in September, where it’s a little bit more focused on passenger vehicles and how they drive around these trucks.

“But there’s not one in the winter time. There’s an unannounced brake check that usually happens in May, a surprise inspection that’s just one day. But you’re right in pointing out that it might be worthwhile having one of these in the wintertime. You have this periodic high-intensity inspection that kind of incentivizes everybody to be compliant through the summer. 

“But there’s nothing in the winter, so that’s an area. But if I was managing the FMCSA, that would be one of the first questions I ask, ‘Why don’t we have one of these in the wintertime?’”

FREIGHTWAVES: That makes sense. Maybe they can do it in the South or something. Maybe a Miami January inspection … 

That’s it for this special bonus MODES. Subscribe here if you’re not already receiving MODES in your inbox every Thursday. Email the reporter at rpremack@www.freightwaves.com with your own tales on International Roadcheck Week or any other trucking topics. 
Why the Northeast is quietly running out of diesel

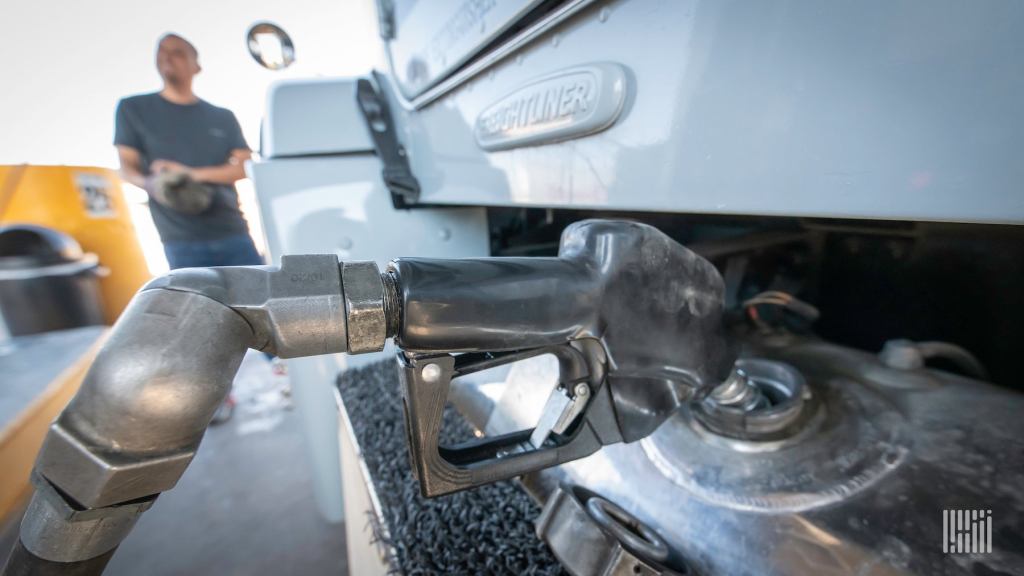
The nozzle of a diesel fuel pump is inserted into the tank of a commercial truck as its driver looks on the bankground.

The East Coast of the U.S. is reporting its lowest seasonal diesel inventory on record. And some trucking companies appear spooked.

The East Coast typically stores around 62 million barrels of diesel during the month of May, according to Department of Energy data. But as of last Friday, that region of the U.S. is reporting under 52 million barrels. 

The sharp increase of diesel prices has been a major stressor in America’s $800 billion trucking industry since the beginning of 2022. According to DOE figures, the price per gallon of diesel has reached record highs — a whopping $5.62 per gallon. It’s even higher on the East Coast at $5.90, up 63% from the beginning of this year. 

When relief is coming isn’t yet clear, and experts say higher prices are the only way to attract more diesel into the Northeast.

“I wish I had some good news for the Northeast, but it’s bedlam,” Tom Kloza, global head of energy analysis at OPIS, told FreightWaves. 

2022 has seen record-setting diesel prices. (SONAR)

Everyday Americans don’t fill up their cars with diesel, but the fuel powers our nation’s agriculture, industrial and transportation networks. More expensive diesel means the price of everything is liable to increase. Trucks, trains, barges and the like consumed about 122 million gallons of diesel per day in 2020. 

Patrick DeHaan, a vice president of communications at fuel price site GasBuddy, reported that retail truck stops are hauling fuel from the Great Lakes to the Northeast, calling it “extraordinary.” We’ve also seen anecdotal reports from truck drivers posting company memos:

Pilot Flying J and Love’s, two of America’s largest truck stops, told the Wall Street Journal yesterday that they were not planning to restrict diesel purchases, but were monitoring low diesel inventory.

Not unlike every other supply chain crunch we’ve seen in the past few years, the cause of the Northeast’s diesel shortage is multifaceted. A yearslong degradation of refineries is rubbing against the Gulf Coast preferring to ship its oil to Europe and Latin America.

Here’s a breakdown:

1. The East Coast has lost half of its refineries. 

As Bloomberg’s Javier Blas wrote on May 4 (emphasis ours): 

In the past 15 years, the number of refineries on the U.S. East Coast has halved to just seven. The closures have reduced the region’s oil processing capacity to just 818,000 barrels per day, down from 1.64 million barrels per day in 2009. Regional oil demand, however, is stronger.

Rory Johnston, a managing director at Toronto-based research firm Price Street and writer of the newsletter Commodity Context, told FreightWaves that refining is a “thankless industry,” with intense regulations that have limited the opening of new refineries. The Great Recession of 2008 led to several East Coast refineries shuttering, but there have been more recent shutdowns too. One major Philadelphia refinery shuttered in 2019 after a giant fire (and it already had declared bankruptcy), and another refinery in Newfoundland shut down in 2020.

2. It’s a financial risk to bring diesel to the Northeast.

The Northeast has increasingly relied on diesel from the Gulf region. Much of that diesel travels to the Northeast through the famous and much-adored Colonial Pipeline. You may remember the 5,500-mile pipeline from last year, when a ransomware attack shuttered it for nearly a week!  

It takes 18 days for oil to travel on the Colonial Pipeline from its source in Houston to New York City (or, more specifically, Linden, New Jersey), Kloza said.

That’s a long enough time to prioritize Colonial pipelines financially risky for traders — or, as Kloza said, “incredibly dangerous” — thanks to a concept called “backwardation.”

Backwardation refers to the market condition in which the spot price of a commodity like diesel is higher than its futures price. It’s only gotten stronger over time in the diesel market, Kloza said. So, a company could send off a shipment of diesel and find that it dropped by $1 per gallon in the time the diesel traveled from the Gulf Coast to New York — er, New Jersey. That could mean hundreds of thousands or more in lost profits, so traders often avoid such a fate.

“We’re not in an era where there are any U.S. refiners or big U.S. oil companies who would ‘take one for the team’ and bring cargo in where it’s needed,” Kloza said. 

The desperation is showing in New England and the mid-Atlantic regions. New England diesel retail prices are up 75% from the beginning of 2022, per DOE data. In the mid-Atlantic, diesel is up 67%. 

It’s not worth the risk, even amid ultra-high prices. As FreightWaves’ Kingston reported last week, the spread between a gallon of diesel in the Gulf Coast and its New York harbor price is usually a few cents. Last week, that swung up to 66 cents.

But that uptick still isn’t justifying moving oil to the Northeast — particularly when traders can make so much more money selling diesel abroad. 

3. Of course, we can blame COVID and the crisis in Ukraine. 

The catalyst for this diesel shortage, of course, is the ongoing conflict in Ukraine — particularly Europe’s desperation for diesel after weaning off Russian molecules. 

As CNBC reported in March, Europe is a net importer of diesel. Europe consumed some 6.8 million barrels of diesel each day in 2019; Russia exported some 600,000 barrels per day of that. Today, Europe has only eliminated one-third of its Russian diesel, so prices are expected to continue to climb amid that transition. Latin America, too, has been clammoring for U.S. diesel.

The Gulf Coast has been happy to provide such diesel, amid “insane” prices for diesel abroad, said Johnston. Waterborne exports of diesel from the U.S. Gulf Coast hit record highs last month, according to oil analytics firm Vortexa. (The records only date back to 2016.)

Naturally, COVID is also to blame for the Northeast’s run on diesel. Those refineries still retained on the East Coast scaled back during the pandemic due to staffing issues. It takes six months to a year to reignite refineries that were previously shuttered, Kloza said.

The ‘everything shortage’ endures

It’s been a tale as old as, well, last year. An industry is quietly hampered by supply issues for years, or even decades, and COVID pulls back the curtains on its unsteady foundation. It’s particularly jarring for commodities we never thought about before, like shipping containers or pallets, but that quietly underpinned our livelihood all along. 

Recall the Great Lumber Shortage of 2020? Big Lumber had unusually low stockpiles of wood by the summer of 2020, thanks to a vicious 2019 in the lumber industry shuttering sawmills and the spring of 2020 sparking staffing issues. (There was also a nasty beetle infestation.) Those in lumber expected the pandemic to slow the economy, not ignite online shopping, construction and housing mania. It meant lumber went from around $350 per thousand board feet pre-pandemic to a crushing $1,515 by the spring of 2021. The lumber price roller coaster persists today.  

In diesel, there’s no beetle infestation, but there are plenty of other headaches. It all means higher fuel prices on the East Coast, particularly the Northeast, to lure molecules from the Gulf Coast. And, down the line, probably more expensive stuff for you. 

Do you work in the trucking industry? Do you want to say that you hate or love MODES? Are you simply wanting to chitchat? Email the author at rpremack@www.freightwaves.com, and don’t forget to subscribe to MODES.

Updated on May 13 with the latest comments from truck stops.

Exclusive: Central Freight Lines to shut down after 96 years

Nearly, 2,100 employees will be laid off right before Christmas. Central Freight Lines is the largest trucking company to close since Celadon ceased operations in 2019.


Waco, Texas-based Central Freight Lines has notified drivers, employees and customers that the less-than-truckload carrier plans to wind down operations on Monday after 96 years, the company’s president told FreightWaves on Saturday.

“It’s just horrible,” said CFL President Bruce Kalem.

A source close to CFL told FreightWaves that CFL had “too much debt and too many unpaid bills” to continue operating, despite exploring all available options to keep its doors open.

Kalem agreed.

“Years of operating losses and struggles for many years sapped our liquidity, and we had no other place to go at this point,” Kalem told FreightWaves. “Nobody is going to make money on this closing, nobody.” 

Central Freight will cease picking up new shipments effective Monday and expects to deliver substantially all freight in its system by Dec. 20, according to a company statement.

A source familiar with the company said he is unsure whether CFL will file Chapter 7 or “liquidate outside of bankruptcy,” but that the LTL carrier has no plans to reorganize.

The company reshuffled its executive team nearly a year ago in an effort to stay afloat, including adding the company’s owner, Jerry Moyes, as CFL’s interim president and chief executive officer. Moyes remained CEO after Kalem was elevated to president in July.

“I think it was surprising that there wasn’t a buyer for the entire company, but buyers were interested in certain pieces but not in the whole thing,” the source, who didn’t want to be identified, told FreightWaves. “Part of it could have been that just the network was so expansive that there was too much overlap with some of the buyers that they didn’t need locations or employees in the places where they already had strong operations.”

Third-party logistics provider GlobalTranz notified its customers that it had removed CFL as “a blanket and CSP carrier option immediately, to prevent any new bookings,” multiple sources told FreightWaves on Saturday.

CFL, which has over 2,100 employees, including 1,325 drivers, and 1,600 power units, is in discussions with “key customers and vendors and expects sufficient liquidity to complete deliveries over the next week in an orderly manner,” a CFL spokesperson said. Approximately 820 employees are based at the company headquarters in Waco.

Despite diligent efforts, CFL “was unable to gain commitments to fund ongoing operations, find a buyer of the entire business or fund a Chapter 11 reorganization,” another source familiar with the company told FreightWaves.

Kalem said the company had 65 terminals prior to its decision to shutter operations. 

FreightWaves received a tip from a source nearly two weeks ago that CFL wasn’t renewing its East Coast terminal leases but was unable to confirm the information with CFL executives. 

Another source told FreightWaves that some of the LTL carrier’s West Coast terminals had been sold recently, but that no reason was given for the transactions.

At that time, Kalem said the company was “working to find alternatives” and couldn’t speak because of nondisclosure agreements. He said executives at CFL, including Moyes, were trying to do everything to “save the company.”

“Jerry [Moyes] pumped a lot of money into the company, but it just wasn’t enough,” Kalem said.

Kalem said he’s aware that a large carrier is interested in hiring many of CFL’s drivers but isn’t able to name names at this point. 

“Central Freight is in negotiations to sell a substantial portion of its equipment,” the company said in a statement. “Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area.”

As of late Saturday night, Kalem said fuel cards are working and drivers will be paid for freight they’ve hauled for the LTL carrier until all freight is delivered by the Dec. 20 target date.

“I’m going to work feverishly with the time I have left to get these good people jobs — I owe it to them,” Kalem told FreightWaves. “We are going to pay our drivers — that’s why we had to close it like we’re doing now. We are going to deliver all of the freight that’s in our system by next week, and we believe we can do that.”

During the outset of the pandemic, Central Freight Lines was one of four trucking-related companies that received the maximum award of $10 million through the U.S. Small Business Administration’s Paycheck Protection Program (PPP). This occurred around the time that CFL drivers and employees were forced to take pay cuts, a move that didn’t go over well with drivers.

“It all went to payroll,” Kalem said about the PPP funds. “Yes, our employees and drivers did take a pay cut over the past few years, and we gave most of it back, even raised pay over the past several months, but it just wasn’t enough to attract drivers.”

FreightWaves staffers Todd Maiden, Timothy Dooner and JP Hampstead contributed to this report.


Watch: Central Freight Lines’ impact on the LTL market


FreightWaves CEO and founder Craig Fuller reacts to the Central Freight Lines news:

“With Central struggling for many years and unable to reach profitability, it makes sense that they would want to liquidate while equipment and real estate are fetching record prices.”


Central Freight Lines statement

Here is the statement given by Central Freight Lines to FreightWaves late Saturday after reports surfaced of its impending closure:

“We make this announcement with a heavy heart and extreme regret that the Company cannot continue after nearly 100 years in operation. We would like to thank our outstanding workforce for persevering and for professionally completing the wind-down while supporting each other. Additionally, we thank our customers, vendors, equipment providers, and other stakeholders for their loyalty and support.

“The Company explored all available options to keep operations going. However, operating losses sapped all remaining sources of liquidity, and the Company’s liabilities far exceed its assets, all of which are subject to liens in favor of multiple creditors. Despite diligent efforts, the Company was unable to gain commitments to fund ongoing operations, find a buyer of the entire business, or fund a Chapter 11 reorganization. Given its limited remaining resources, the Company concluded that the best alternative was a safe and orderly wind-down. As we complete the wind-down process, our primary goal will be to offer the smoothest possible transition for all stakeholders while maximizing the amount available to apply toward the Company’s obligations.

“Central Freight is in negotiations to sell a substantial portion of its equipment. Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area. Discussions are ongoing and no purchase of assets or offer of employment is guaranteed.”


Brief history of Central Freight Lines

1925Founded in Waco, Texas, by Woody Callan Sr.
1927Institutes regular routes in Texas between Dallas, Fort Worth and Austin.
1938Dallas facility opens as world’s largest freight facility.
1991Receives 48-state interstate operating authority, expands into Oklahoma.
1993Joins Roadway Regional Group and begins service in Louisiana.
1994Expands into Colorado, Kansas, Missouri, Illinois and Mississippi.
1995Consolidation of Central, Coles, Spartan and Viking Freight Systems into Viking Freight Inc. is announced. Central’s Waco corporate HQ starts closure.
1996Becomes the Southwestern Division of Viking Freight Inc.
1997Investment group led by senior Central management purchases assets of former CFL from Viking Freight and reopens as a new Central Freight Lines.
1999Expands into California and Nevada.
2009CFL Network provides service to Idaho, Utah, Minnesota and Wisconsin.
2013Acquires Circle Delivery of Tennessee.
2014Acquires DTI, a Georgia LTL carrier.
2017Acquires Wilson; new division created with an increase of 80 terminals.
2020Wins Carrier of the Year from GlobalTranz.
Acquires Volunteer Express Inc. of Dresden, Tennessee.
Source: Central Freight Lines

Warehouse cramming is about to begin — Freightonomics

nVision Global, is a leading Global Freight Audit, Supply Chain Management Services company offering enterprise-wide supply chain solutions. With over 4,000 global business “Partners”, nVision Global not only provides prompt, accurate Freight Audit Solutions, but also providing industry-leading Supply Chain Information Management solutions and services necessary to help its clients maximize efficiencies within their supply chain. To learn more, visit www.nvisionglobal.com

Warehouse space is at a premium right now and with peak season right around the corner, shippers are starting to scramble for space. 

Zach Strickland and Anthony Smith look into what shippers are doing to prepare for the end-of-year crunch. They welcome Zac Rogers from Colorado State University to the show to talk through the industry tightness. 

The three also talk about the latest Logistics Managers Index results and what they mean for the fourth quarter of 2021. 

You can find more Freightonomics episodes and recaps for all our live podcasts here.

Seasonality pushing rejections and rates higher ahead of the Fourth

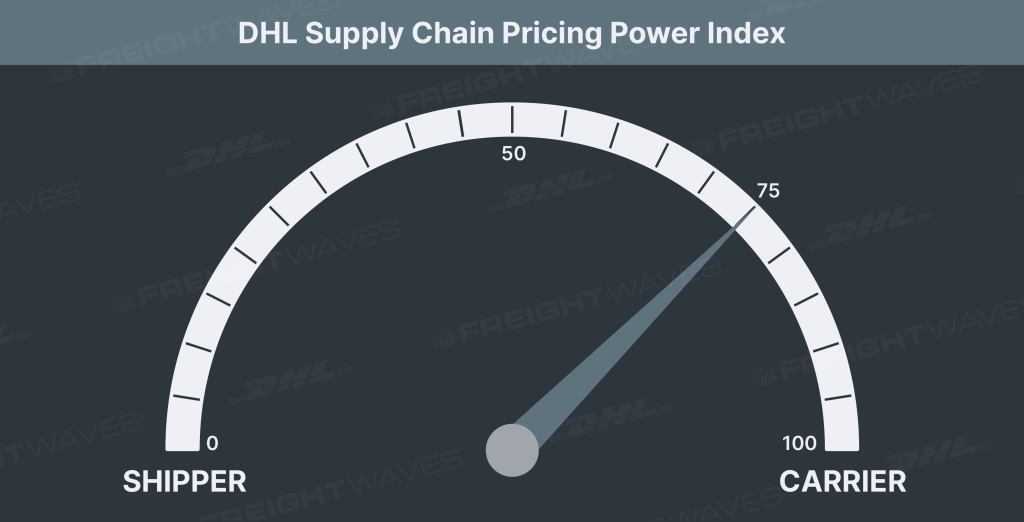
This week’s DHL Supply Chain Pricing Power Index: 75 (Carriers)

Last week’s DHL Supply Chain Pricing Power Index: 70 (Carriers) 

Three-month DHL Supply Chain Pricing Power Index Outlook: 70 (Carriers)

The DHL Supply Chain Pricing Power Index uses the analytics and data in FreightWaves SONAR to analyze the market and estimate the negotiating power for rates between shippers and carriers. 

The Pricing Power Index is based on the following indicators:

Load volumes: Absolute levels positive for carriers, momentum neutral

The Outbound Tender Volume Index at 15,980 is nominally higher now than basically at any point in the past 12 months with the exception of the week prior to Thanksgiving/Black Friday last year. OTVI captures all electronic tenders, including rejected ones, so when accounting for the rejection rate, we can get an even more accurate look at volumes. 

OTVI rose through the back half of May into the national holiday and has risen even further since. Throughout the back half of May and into the middle of June, tender rejections declined substantially. Meaning, current volume throughput is actually understated when comparing OTVI now to OTVI in November 2020. After adjusting for rejected tenders, the accepted outbound tender volume index is just 2.2% below the 2020 peak in November. At that time, OTVI surged towards 17,000, but the rejection rate moved in-kind towards its natural ceiling of 28%. So, the total accepted freight tenders in mid-June is comparable to the peakiest of peak seasons in 2020. Incredible. 

However, since the middle of June, tender rejections have begun increasing again heading into Independence Day, a time when many drivers spend time off the road with their families. The move higher in OTVI this week has been driven primarily by higher rejection rates, rather than higher freight demand. 

Over the past month, the drivers of freight volumes have continued to be imports and from just about every port. The west coast continues to provide seemingly non-stop container ships, while Houston, New Orleans, Miami and Savannah are seeing very strong throughput as well. 

It is van volumes that are driving freight markets higher right now. The Reefer Outbound Tender Volume index has tumbled 25% since its all-time high in the weeks after the polar vortex in February. Since Memorial Day, ROTVI has fallen another 10.5%. This is likely a factor of declining grocery demand, but I would expect the trend to reverse course in the near future as summer festivities accelerate. 

Dry van volumes pushed higher in the back half of May and into June while reefer volumes have declined significantly. 

SONAR: VOTVI.USA (Blue); ROTVI.USA (Green)

The congestion at our nation’s ports has spread from Los Angeles and Long Beach to Oakland, California. The California coastline is a parking lot of container ships, most of which are full to the brim with imports, awaiting berth. As detailed in the economic section, there are some signs that the reversion is underway with Americans paring back spending on pandemic superstar categories in favor of airlines, lodging and entertainment. But spending remains strong despite the moderation, and low inventory levels offset much of the decline that will occur from slowing demand. Real inventories are 3% higher now than pre-pandemic, but real sales growth is far outpacing inventory growth, leading to the lowest inventory-to-sales ratio in decades. 

On the manufacturing side, the ISM Manufacturing PMI expanded in May after declining in April. We’ve been in expansionary territory for 12 consecutive months. New orders, production, imports/exports and employment are all growing. The major issues should come as no surprise: Deliveries are slowing, backlogs are growing and inventories are too low. 

In all, there are many, many catalysts to keep freight demand strong for the foreseeable future. Americans are traveling and spending on services at a high clip, but the high savings rate is enabling it to occur without a massive detriment to goods spending. 

SONAR: OTVI.USA (2021 – Blue; 2020 – Green; 2019 – Orange; 2018 –  Purple)

Tender rejections: Absolute level and momentum positive for carriers

After declining steadily from mid-March to mid-May, the Outbound Tender Reject Index has reversed course heading into Independence Day. This is typical for a national holiday as carriers selectively choose loads to bring drivers closer to home. OTRI now sits above 25% for the first time in June. 

One of our newest indices in SONAR gives us the ability to compare markets on as close to an apples-to-apples basis as possible. FreightWaves’ Carrier Trend Market Score indices are divided into two perspectives – shipper/broker and carrier. The scores are positioned on a scale from 1-100 and have values measuring van and refrigerated (reefer) capacity. The higher values represent more favorable trends for whichever perspective. For instance, a value near the high-end of the range would suggest very favorable conditions for carriers in our carrier capacity trend score index. 

For the past several weeks, capacity disparities have been driven by import volumes. The markets with the tightest carrier capacity coincide with the nation’s busiest ports. Ontario, California, Savannah, Georgia, and Atlanta all have carrier capacity trend market scores of 100. 

SONAR: Capacity Trend Market Score (Carriers – VAN)

By mode. Reefer rejection rates tumbled from it’s all-time high in March to under 35% in mid-June before popping higher over the past two weeks. Reefer rejections are still quite high from a historical standpoint at 38%, but are significantly lower than just three months ago when reefer carriers were rejecting half of all electronically tendered loads. 

SONAR: VOTRI.USA (Blue); ROTRI.USA (Orange)

Dry van tenders make up the majority of all tenders, so the van rejection rate mirrors the aggregate index closely. Van rejections have surged from ~23% to ~26% over the past two weeks. 

Yes, one-in-four loads being rejected is not ideal, but it’s better than 30%. I am unaware of any meaningful signals that capacity is being added at a rate that would change my outlook. With so many catalysts for demand, and many constraints on drivers including the Drug & Alcohol Clearinghouse, driver training school closures and continued government unemployment benefits, the outlook is tight throughout this year and into 2022. That’s not to say we won’t see improvement as consumers revert to pre-pandemic spending habits and drivers enter or reenter the market. But I’m not expecting any quick reversal of this environment; there are simply too many catalysts driving volume and suppressing capacity. 

SONAR: OTRI.USA (2020/21 – Blue; 2020 – Green; 2019 – Orange)

Freight rates: Absolute level and momentum positive for carriers

Throughout June, spot rates have moderated while contract rates have pushed higher. The Truckstop.com dry van rate per mile (incl. fuel) has fallen from $3.21 to $3.11 since the beginning of June, while FreightWaves van contract rates have risen from $2.50 to $2.59/mile, exclusive of fuel. 

I still believe the Truckstop.com dry van national average will not retest the post-vortex surge pricing that brought spot rates up to an all-time high of $3.30. But, there aren’t many catalysts to bring spot rates down anytime soon either. Demand is unwavering with continued strong consumer goods demand, humming industrial recovery and a potentially cooling, yet still sizzling, hot housing market. And carriers can’t fill enough trucks to keep up with demand. 

Prior to the seasonal movements we’re seeing in tender rejections, routing guides generally had been improving through Q2. We should continue to see a convergence between spot and contract rates, but spot rates will remain historically very elevated throughout the summer as demand simply outstrips capacity. 

SONAR: TSTOPVRPM.USA (Blue); VCRPM1.USA (Green)  

Economic stats: Momentum and absolute level neutral

Several economic releases this week are worth noting.

Weekly jobless claims were released Thursday and give us one of the best close-to-real-time indicators of the overall economy.  This week, the data was again very promising as the labor market continues on a bumpy but trajectorially stable recovery path. 

First-time filings totaled 411,000 for the week ended June 19, a slight decrease from the previous total of 418,000 but worse than the 380,000 Dow Jones estimate, the Labor Department reported Thursday. Initial claims have held above 400,000 for consecutive weeks after falling to a pandemic low of 374,000 three weeks ago. As things stand, the current level of initial claims is about double where it was prior to the Covid-19 pandemic. 

The good news on the jobs front is that continuing claims are on the decline, falling to 3.39 million, a drop of 144,000. That number runs a week behind the headline claims total.

Initial jobless claims (weekly in May 2020-May 2021)

At the time of writing, the newest weekly data for the week ending May 29 had not been updated in SONAR. This week, claims fell from 405,000 to 385,000. 

SONAR: IJC.USA

Consumer. Turning to consumer spending, as measured by Bank of America weekly card (both debit and credit) spending data, total card spending (TCS) in the latest week accelerated to 22% over 2019. This is the first time in June that TCS has topped 20% over 2019, but spending has been running up 16-19% consistently on a two-year comp for months. For contect, the average pre-pandemic two-year growth rate was about 8% (from 2012 to 2019). 

The Bank of America team highlighted service spending in the nation’s two largest state economies, California and New York, which are now fully reopened. Spending at restaurants is now well above 2019 in both states, and the team believes there is more capacity for spending to accelerate in the states that were slower to reopen given pent-up demand. 

There was also a notable acceleration in spending on clothing this week, according to Bank of America. It could be a reversal from some softening in the early weeks of June, or an indication of people refreshing wardrobes ahead of a return to work, more travel and vacations. One tepid statement for freight markets from this week;s report: Leisure spending is on the rise and durable goods spending is flatlining.  

FreightWaves’ Flatbed Outbound Tender Reject Index, both a measure of relative demand and capacity, moves directionally with the ISM PMI. 

SONAR: ISM.PMI (Blue); FOTRI.USA (Green) 

Manufacturing. Over the past two weeks, regional manufacturing surveys have reported generally positive readings amid logistical challenges. The New York Fed’s Empire State business conditions index declined 6.9 points to 17.4 in June, retreating from strong readings the past two months. The Empire State Index is a diffusion index with a baseline of zero; any reading above zero indicates improving or expansionary conditions. 

Delivery times lengthened to a new record during the month, new orders and shipments fell, and inventories entered negative territory. The supply chain and transportation challenges are as visible upstream as downstream, but overall the manufacturing sector is handling. Growth continued throughout the second quarter in both the Empire State and Philly Fed indices. 

The Philadelphia Federal Reserve’s business activity index edged lower to a still robust 30.7 in June from 31.5 in the prior month. Unlike NY, the pace of shipments growth accelerated in the Philly region during June. The employment subcomponent rose to a very healthy 30.7 from 19.3 last month, the regional bank said. 

Record-long lead times, wide-scale shortages of critical basic materials, rising commodities prices and difficulties in transporting products are continuing to affect all segments of the manufacturing economy, but demand remains strong. 

For more information on the FreightWaves Freight Intel Group, please contact Kevin Hill at khill@www.freightwaves.com or Andrew Cox at acox@www.freightwaves.com.

Check out the newest episodes of our podcast, Great Quarter, Guys, here.

Project44 acquires ClearMetal to strengthen predictive tools

Project44, a leader in real-time visibility of the global supply chain, announced on Thursday it has acquired ClearMetal, a San Francisco-based supply chain planning software company that focuses on international freight visibility, predictive planning and overall customer experience. The terms of the acquisition were not disclosed.

ClearMetal, founded by top software engineers and data scientists from Stanford, Google and other Silicon Valley elites, has created a “continuous delivery experience” that leverages proprietary machine learning algorithms that can forecast supply chain disruptions. 

In an interview, Jason Duboe, chief growth officer at project44, explained that bringing in ClearMetal’s elite team is essential for the company’s future predictive solutions.

“Their team construct is fundamentally different. When you look at their data science, machine learning and computer science background, they are best in class,” he said. “Applying the team to solve really interesting challenges, starting with highly predictive ETA and deeper exception management to create more predictive analytics is really a key component here.”

Project44 recently acquired Ocean Insights to gain global supply chain vessel visibility and has announced it has expanded its truckload tracking services within Asia. Bringing on this new team of engineers will allow the company to capitalize on strong predictive tools, strengthening the supply chain of its customers.

“We’re going to be expanding deeper into Asia, and from a port perspective, getting data much earlier than competitors,” explained Duboe. “Our freight forwarder integrations will give us much deeper visibility from an end-to-end perspective in these regions.”

Along with the acquired skills the ClearMetal team will bring to project44, it brings a large book of customers, including large CPGs, retailers, manufacturers, distributors and chemical companies. These advanced use cases will strengthen the predictive planning tools, and project44 continues to expand into different customer markets.

“What we gain from ClearMetal is a holistic platform for anybody that joins the platform in the future,” said Duboe. “They have large customers with incredibly demanding and advanced use cases. So when it comes to order and inventory, functionality, supplier onboarding, and moving upstream into those processes, we can capture exceptions earlier on.”

Click here for more articles by Grace Sharkey.

Related Articles:

Project44 expands real-time visibility into China

Project44 reels in Ocean Insights in ‘largest acquisition in visibility space’

‘Project44’s vision has always been global’

Class 8 truck orders rise 18% in September as fleets turn to 2027 models 

North American Class 8 truck orders rose in September as fleets began shifting their attention to model-year 2027 equipment amid lingering uncertainty over emissions regulations and truck pricing.

Preliminary Class 8 net orders totaled 21,300 units in September, an 18% increase from August and 3% higher than the same month last year, according to FTR Transportation Intelligence.

While the month-over-month increase was smaller than the seasonal gain typically seen in September, FTR said underlying truck demand remained “fairly solid,” supported by fleet replacement needs, tight capacity and firmer freight rates.

Year-to-date Class 8 orders totaled 263,499 units through September, up 95% compared with the same period in 2025. Orders over the past 12 months totaled 351,244 units.

September also represented an important transition for the heavy-duty truck market as manufacturers shifted their order books toward model-year 2027 equipment.

FTR said the EPA 2027 nitrogen oxide emissions-related pre-buy has ended, while surcharge-free model-year 2026 engine production slots are essentially sold out. Some truck manufacturers may have closed their 2026 order books in early to mid-August before opening books for 2027 models, potentially pushing some deferred orders into September.

At the same time, truck and engine manufacturers are taking different approaches to complying with upcoming emissions requirements, including whether to use nonconformance penalties, or NCPs.

The uncertainty could have significant cost implications for fleets.

Dan Moyer, FTR senior analyst for commercial vehicles, said NCPs could result in an estimated $6,000 to $7,000 pass-through cost to fleets for a Class 8 truck, compared with an estimated $8,000 to $12,000 upcharge for an engine that fully complies with the new emissions requirements.

“Truck and engine manufacturers have announced varying strategies for handling the emissions transition, and some have not yet made their plans clear,” Moyer said in a news release.

“The final EPA rule could still materially alter the economics of these strategies. Higher NCPs would narrow the cost advantage of current-generation engines while lower NCPs would make that pathway more attractive. That major issue, along with other potential changes, could affect 2027 engine availability, fleet acquisition costs, and the mix of technologies ultimately selected.” 

Those decisions could ultimately affect engine availability, fleet acquisition costs and the types of engine technologies fleets select for 2027 trucks.

Pricing remains another question for the market. Manufacturers are opening model-year 2027 order books before EPA’s 2027 NOx regulation is finalized, meaning truck prices could change once the final rule is issued.

FTR said orders during the next month or two could remain near year-ago levels until fleets receive greater clarity on regulations and costs.

Why it matters: Truck demand remains relatively firm heading into the 2027 model year, but uncertainty over EPA emissions requirements and the cost of compliant engines could shape fleet purchasing decisions in the months ahead. 

More FreightWaves articles by Noi Mahoney:

C.H. Robinson Buys RXO: History’s Largest Brokerage Deal

C.H. Robinson’s acquisition of RXO marks the biggest truck brokerage merger in history. This monumental $5.8 billion deal, driven by the promise of $300 million in synergies, could redefine the competitive landscape for 3PLs. What does this mean for the future of freight and for other brokers in the industry?

C.H. Robinson announced Monday it will acquire RXO in a deal valued at approximately $5.8 billion in enterprise value, combining the No. 1 and No. 3 truck brokerages in the country. RXO shareholders will receive $17.25 per share in cash plus roughly 0.0909 shares of C.H. Robinson stock per RXO share, or they may elect an all-cash option valued at $30.25 per share. The transaction is the largest truck brokerage merger in history, dwarfing prior deals including RXO’s own acquisition of Coyote from UPS.

The headline driver of the deal is $300 million in projected run-rate cost synergies, which C.H. Robinson committed to achieving within two years. With C.H. Robinson’s trailing price-to-earnings ratio currently at 26, multiplying that multiple by the $300 million in synergies yields roughly $7.8 billion in implied value — more than the $5.8 billion enterprise price tag for RXO. “I think the bottom line is there’s no further than the $300 million,” said John Kingston. “You paid for the deal today.”

Expected synergies span technology, real estate, and overhead. C.H. Robinson plans to run acquired freight primarily through its existing Navisphere TMS and Lean AI platform, avoiding major incremental technology capital expenditure. Duplicate office footprints in cities where both companies maintain a presence — Chicago being a prime example given Coyote’s historical base there — represent a significant real-estate cost opportunity. Management also pointed to minimal customer overlap, with C.H. Robinson skewed toward small and medium-sized businesses while RXO has deeper ties to enterprise shippers, final-mile, and expedited freight.

“If you’re at a 3PL right now, the whole world has changed. And it’s so interesting because there was all this talk about consolidation — the small and medium brokers, they just probably can’t make it on their own in a post-Montgomery world. Well, this has nothing to do with small to medium brokers. These are 2 of the 3 biggest, and they got together.”

RXO’s financial trajectory made a sale increasingly logical. The company had posted ten consecutive quarters of net losses, and its stock had fallen below $11 as recently as last November before recovering into the $20s. Its all-time post-spinoff high was above $30. The $30.25 cash option represents a substantial premium to where RXO had been trading for much of the past year. By contrast, C.H. Robinson — under CEO Dave Bozeman, who came to the company from Amazon and Ford — has aggressively cut headcount and invested in AI and lean process improvements, disclosing its workforce figures every quarter in a way that allowed outside analysts to track efficiency gains in real time.

A key structural benefit for the combined company is credit quality. C.H. Robinson holds an investment-grade credit rating approximately two notches above the cutoff at both Moody’s and S&P, while RXO sits below investment grade at both agencies. Bozeman confirmed the companies consulted with ratings agencies before announcing the deal, and those agencies indicated the combined entity would maintain an investment-grade rating — preserving access to lower-cost debt and a broader institutional bond-buying pool that non-investment-grade issuers cannot tap.

RXO shares surged more than 16% in the days before the official announcement, a move that coincided with a short interest position equal to roughly 10% of the company’s float. The stock’s pre-announcement movement drew scrutiny, though Kingston noted that both management teams appeared to have kept the deal tightly held and that the run-up may have been partly driven by short sellers rushing to cover as prices moved. Kingston and his co-hosts said they expect Monday’s deal to accelerate broader brokerage consolidation, with mid-sized brokers now facing a market in which two of their three largest competitors have merged into a single platform.

  • C.H. Robinson is acquiring RXO for approximately $5.8 billion in enterprise value — the largest truck brokerage deal in history — with RXO shareholders receiving $30.25 per share in cash or a cash-and-stock mix.
  • The deal targets $300 million in run-rate cost synergies within two years; at C.H. Robinson’s trailing P/E of 26, that implies roughly $7.8 billion in value, exceeding the purchase price.
  • RXO had suffered ten consecutive quarters of net losses and a stock price that fell below $11 last November, while C.H. Robinson’s investment-grade credit rating — two notches above the cutoff — will be maintained post-merger according to ratings agency consultations.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Truckload Spot Rates Keep Rising, But Demand Isn’t… Why?

Truckload spot rates keep rising, but demand isn’t the real story. Accepted tender volumes are falling, rejection rates have cooled, and yet spot and contract rates are still moving up. In this market update, we break down the mixed truckload signals: softer tenders, higher fuel, tighter capacity, barriers to entry for new carriers, and why that combination could keep rates firm longer than many expected. #TruckloadMarket #SpotRates #FreightMarket

Dry van spot rates including fuel reached $3.55 per mile as of early October, up more than 10% from late August and roughly 50% above year-ago levels — yet the driver is not a surge in freight demand. Instead, rising diesel costs and structural capacity tightness are doing the heavy lifting, according to Julie Van de Kamp.

The fuel component is stark. The FreightWaves DTS diesel truck stop price hit $6.39 and has climbed steadily since July. In just the past month, diesel is up nearly 9.9% while all-in spot rates on the FreightWaves NTI index rose about 4.1%, suggesting fuel is the dominant near-term force on shipper-facing pricing.

Demand indicators are actually softening. Accepted tender volumes have fallen nearly 3% over the past week and are down about 9% since mid-September — though Van de Kamp noted that the mid-September baseline was inflated by a post-Labor Day bump. Tender volumes are also down 20% from their June peak. Year over year, accepted tender volumes are tracking below the prior three years.

“We are going to continue to see tighter markets based on available capacity, not necessarily based on demand,” said Van de Kamp.

Rejection rates tell a similar story of a market that is firm but not frenzied. Outright rejections peaked at 14.67% in mid-September before easing to about 13.79%, a level Van de Kamp characterized as still consistent with a healthy, non-loose market. Van de Kamp said new carrier operating authority filings are not a reliable signal of incoming capacity, arguing applicants are likely securing MC and DOT numbers now to age them for future use rather than putting trucks on the road immediately.

Structural barriers are limiting how quickly capacity can respond to rate signals. Fewer CDL schools, difficulty recruiting and retaining qualified drivers, and increasing regulatory burdens are raising the cost and complexity of adding trucks. Van de Kamp noted that large carriers are prioritizing yield and utilization over fleet growth, while smaller entrants face an increasingly difficult path to securing freight. “The barriers of entry for adding capacity have just continued to be increased and regulation is making that harder,” she said.

Contract rates are also moving higher. The van contract rate per mile initial reporting index — VCRPM1 — reached 270 on September 17th, its highest reading since 2022, when it stood at 269. Van de Kamp said rate increases in both the spot and contract markets are also being driven by shipper willingness to pay more for driver quality, safety performance, and fraud risk mitigation — factors that can push rates up independently of load volume. She expects spot rates to hold firm and likely continue rising into the months ahead.

  • Dry van spot rates hit $3.55/mile, up 10%+ since late August and ~50% year over year, with diesel up 9.9% in a month as the primary catalyst.
  • Tender volumes are down 20% from June’s peak and accepted tenders are below the prior three years, signaling demand is not driving the rate rally.
  • Van contract rates reached 270 on Sept. 17 — their highest level since 2022 — as structural capacity barriers, not demand, keep the market tight.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Is the Freight Market Finally Turning?

Webb Estes reveals record tonnage, thriving next-day business, and low driver turnover. He calls it a “Goldilocks market” for contracted carriers. Are you seeing similar success in your operations, or different trends? Let us know below.

Estes Express Lines recorded a 15% year-over-year tonnage increase last week, marking back-to-back record weeks for the LTL carrier, according to Webb Estes, who appeared on FreightWaves Today. The surge adds to a broader trend of supply-side freight growth that Estes said has translated into real hiring gains and improved load factors across the network.

The tonnage spike carried a modest asterisk: Wednesday fell at the end of the month rather than Tuesday as it did a year ago, creating favorable comparisons as shippers rushed to hit quarterly numbers. Even accounting for that calendar shift, Estes described the week as genuinely strong and consistent with predictions he made during a prior appearance on the program.

Breaking down where the volume is coming from, Estes pointed to manufacturing — particularly truck and automotive — alongside groceries and retail. He cited a Wall Street Journal report noting that consumers are continuing to spend despite inflation. The carrier’s next-day, regional business stood out as the fastest-growing segment, with Q3 next-day shipments up 13% year over year compared with 2.5% growth for the rest of its network. Estes attributed the regional outperformance partly to truckload capacity shrinkage pushing shorter-haul freight toward LTL.

“I really believe it comes down to our people. Our driver turnover for people that are within at least one year is at 7.5% right now … our dock worker turnover after one year is the lowest I’ve ever seen it at 11.5%,” said Webb Estes.

Those retention figures underpin a separate milestone: Mastio named Estes the best-value national LTL carrier for the fifth consecutive year, results the company learned the morning of the interview. Estes said low turnover means drivers and dock workers build lasting customer relationships — a structural advantage he believes is difficult for competitors to replicate. The carrier plans to announce pay raises and new benefits for its workforce within the next month.

On the broader market cycle, Estes was measured. He characterized demand as still in “the first inning,” with supply normalization — not a demand boom — driving most of the improvement to date. He flagged rising credit card debt and elevated diesel prices as risks to consumer staying power, while expressing optimism that a reshoring of U.S. manufacturing could create a freight multiplier effect down the road. His host noted that domestic manufacturing typically generates at least three times the freight of an equivalent import flow due to inbound parts and components.

Estes also announced a coming technology upgrade: shippers will soon be able to track freight moving on a live map, building on existing tools that already surface driver name, equipment details, stops-away count, and lane-level on-time performance at the quoting stage. “The visibility is not just for the answer in the moment, but also for them to know, hey, Estes has it,” he said.

  • Estes Express posted 15% year-over-year tonnage growth last week, its second consecutive record, driven by manufacturing, grocery, and retail freight.
  • Next-day regional shipments rose 13% year over year in Q3, far outpacing the carrier’s overall 2.5% volume growth as shorter hauls gain share from tightening truckload capacity.
  • Driver turnover stands at 7.5% and dock worker turnover at 11.5% for employees with at least one year of tenure — both records for the carrier — supporting a fifth straight Mastio best-value award.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

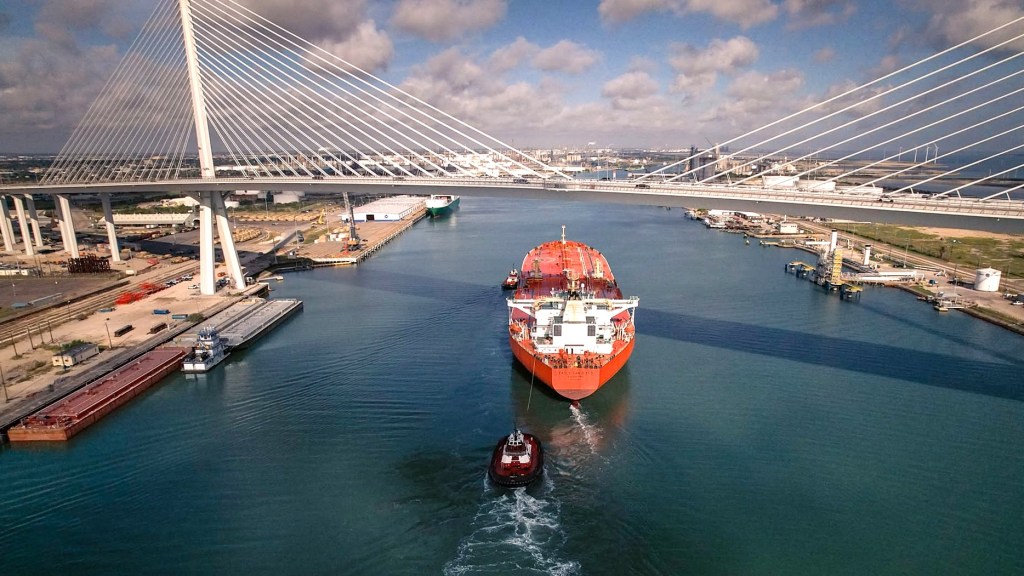
DP World plots US port comeback with Corpus Christi container terminal 

Global terminal operator DP World has taken another step toward returning to U.S. port operations two decades after a proposed takeover of terminals at several major American ports raised concerns over national security.

The Port of Corpus Christi, Texas, has signed a lease option agreement with Dubai-based DP World to develop a container terminal capable of eventually handling about 1 million twenty-foot equivalent units annually, according to a port official.

“We’ve signed a lease option agreement with DP World for a development … of a container terminal in the Port,” Jeffrey Pollack, chief strategy and sustainability officer for the Port of Corpus Christi Authority, told the American Journal of Transportation during the American Association of Port Authorities annual convention in New Orleans on Sept. 29.

Corpus Christi currently is not a container port, and Pollack said adding container operations would significantly diversify a cargo base heavily centered on energy.

Pollack said officials envision a relatively modest container operation by the standards of the largest U.S. gateways, with capacity ultimately topping out around 1 million TEUs annually.

DP World eyes return to US ports

The agreement represents a significant potential return to U.S. marine terminal operations for DP World.

The company, which is owned by the government of Dubai in the United Arab Emirates, became the center of a major political controversy in 2006 after its acquisition of British terminal operator P&O would have transferred P&O’s terminal leases and operations at several major U.S. ports to DP World. 

The deal triggered bipartisan opposition in Congress over national security concerns and ultimately led DP World to divest P&O’s U.S. port operations, according to the U.S. Senate Commerce Committee’s Feb. 28, 2006 hearing, “Security of Terminal Operations at U.S. Ports.” 

DP World ultimately announced in March 2006 that it would divest P&O’s U.S. operations after lawmakers moved to block the transaction. The controversy came despite the George W. Bush administration’s support for the transaction and its position that port security would remain under the responsibility of U.S. Customs and Border Protection and the Coast Guard.

The Corpus Christi project would mark DP World’s first U.S. container terminal development since that episode and its first container terminal development on the U.S. Gulf Coast.

DP World is one of the world’s largest terminal operators, handling roughly 10% of global container traffic through more than 60 ports and terminals.

Corpus Christi looks beyond energy

DP World and the Port of Corpus Christi first announced in June that they had entered exclusive negotiations for a long-term lease. Under the proposed development, DP World would design, build and operate the terminal.

At the time, the parties said negotiations would focus on terminal design, capacity planning and the project’s investment structure.

The project could significantly alter Corpus Christi’s position in Gulf Coast freight markets.

The port is one of the nation’s largest gateways by total tonnage but has historically focused on crude oil, liquefied natural gas, refined petroleum products, agricultural commodities and industrial cargo rather than containers.

More FreightWaves maritime coverage

Corpus Christi also recently acquired about 2,000 acres roughly 8 to 10 miles south of its Inner Harbor that port officials envision as an inland port supporting the proposed container terminal.

Pollack said the property can connect with all three Class I railroads serving the port and multiple interstate highway systems, potentially attracting manufacturing, warehousing and other import-export operations.

The container push comes as Corpus Christi continues posting record overall cargo volumes. Customers moved 110.3 million tons through the Corpus Christi Ship Channel during the first half of 2026, up 7.7% from the previous first-half record of 102.4 million tons set a year earlier.

Why it matters: The project at the Port of Corpus Christi, Texas, would bring DP World back into U.S. container terminal operations two decades after national security concerns in Congress derailed its acquisition of terminal operations at several major American ports.

More FreightWaves articles by Noi Mahoney:

STG Logistics announces new CEO, board members

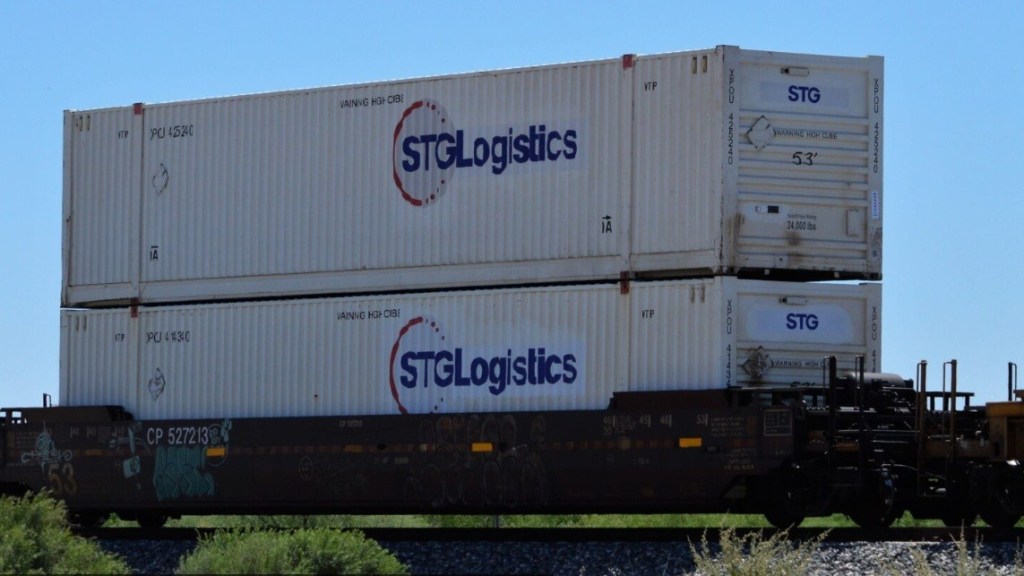
stg containers

STG Logistics announced Monday that Jack Holmes will take over as CEO effective immediately. He will succeed Geoff Anderman, who led the company through its most recent financial restructuring. The company also announced new interim leadership roles and board members.

Holmes was with UPS (NYSE: UPS) for 37 years, serving in various roles, including president and CEO of UPS Freight before retiring in 2016. He has served on various boards and in leadership roles at other transportation and logistics companies since. Holmes will also serve on STG’s board.

“The Board selected Holmes for the industry knowledge and operational expertise needed to build on the Company’s financial and operational progress, and to drive its continued growth,” a news release said.

The company also announced Clinton Smith as its interim chief financial officer, succeeding Tyler Holtgreven, and Cherie Schaible as interim general counsel. Smith has over 25 years of financial leadership experience, leading private-equity backed companies through restructurings and integrations.

Anderman was appointed CEO at STG in April 2025. He has been with the asset-based intermodal marketing company in a leadership position since 2017.

The news release credited Anderman and Holtgreven for successfully navigating a Chapter 11 restructuring, which reduced the company’s funded debt by 90%. Anderman will remain at STG as an adviser through the transition. Holtgreven will remain with the company through Nov. 1.

STG also appointed Gary Enzor as its chairman. Enzor has severed as a director on the boards of other transportation and logistics companies. He led Quality Distribution, North America’s largest liquid bulk chemical trucking network, from 2004 up to the 2021 sale of the business to CSX (NASDAQ: CSX).

“Jack has spent his entire career in this industry, from the loading dock to the CEO’s office, and he brings a rare combination of operational depth and experience building and scaling businesses,” Enzor said. “He is the right choice to lead STG as it accelerates growth and continues investing in the business.”

Other transportation and logistics executives—John Labrie, Joe Troy, Dave Ebbrecht and Darren Hawkins—were also named as STG directors. Hawkins led Yellow Corp., which ceased operations in July 2023. The new group joins existing director Tom Donohue.

STG entered a pre-packaged Chapter 11 agreement in January. Under the recapitalization plan, it reduced funded debt by nearly $1 billion and received $150 million in new capital from a group of investors, including Fortress, Fidelity and Invesco.

“On behalf of the Board, I want to thank Geoff and Tyler for their leadership through one of the most pivotal periods in the Company’s history,” Enzor said. “Thanks to their efforts, STG’s new leadership team inherits a strong foundation and real momentum, and we look forward to partnering closely with them to deliver on the significant opportunities ahead.”

Why it matters? STG Logistics’ successful emergence from Chapter 11 restructuring—backed by nearly $1 billion in debt reduction and $150 million in new capital—preserves critical market capacity and stability for the intermodal industry. Furthermore, the appointment of seasoned veterans ensures strong operational expertise, maintaining competitive options for shippers.

More FreightWaves articles by Todd Maiden:

UK parcel carrier Evri to enter US delivery market with acquisition 

A light-blue Evri delivery van.

Evri, the largest pure-play parcel delivery company in the United Kingdom following its merger with DHL eCommerce last year, has agreed to acquire Florida-based courier Cross Border Connect, which specializes in e-commerce delivery and returns between the U.K. and United States.

The acquisition strengthens Evri Group’s ability to support customers moving parcels between the UK, Europe by combining the company’s scale with Cross Border Connect’s technology and domestic U.S. delivery expertise, Evri said in a news release on Monday announcing the transaction. It also marks the latest step in Evri’s international growth strategy. 

Evri is gaining access to the U.S. market at a time UK-U.S. e-commerce is one of the fastest growing trade lanes in the world

In mid-2025, DHL eCommerce took a large minority stake in Evri and folded its operations into its partner to create a parcel delivery giant in the U.K. Evri currently moves more than one billion parcels and three billion business letters per year.

The same year, Evri also made a multi-million dollar acquisition for Coll-8, an Ireland-based customs clearance specialist giving it direct access into the Republic of Ireland and enabling broader EU cross-border trade.

CBC, based in Boca Raton, operates an asset-light network that uses a proprietary technology platform to manage pickup and customs clearance at six ports of entry and direct injection of packages at the carrier’s closest hub, allowing retailers and marketplaces to optimize parcel routing by cost, speed and service. Co-founder Chris Lentjes will remain as CEO, Evri said.

Why It Matters: The proliferation of last-mile delivery and cross-border logistics providers in recent years gives shippers more options, but analysts say the industry needs to eventually consolidate and sort out the strongest companies. And more parcel operators like Evri are looking to expand into other markets.

“This acquisition is an important step in the continued growth of Evri’s international business. Cross Border Connect brings deep expertise in the U.S. market, strong carrier relationships and innovative technology that enables customers to improve cross-border delivery speed and achieve cost reductions of up to 30%,” said Evri Chief Commercial Officer David Saenz. “Combined with CBC’s established network, integrated customs capabilities and Evri’s best-in-class air freight rates, customers will have even greater flexibility to make smarter shipping decisions and optimize their international delivery operations.”

Financial terms of the transaction were not disclosed.

Click here for more FreightWaves/American Shipper stories by Eric Kulisch.

Write to Eric Kulisch at ekulisch@freightwaves.com.

DHL eCommerce to merge with UK courier Evri

CMA CGM finalizes $1.4B acquisition of FedEx Supply Chain

FedEx and UPS highlight parcel security, risk management tools

UPDATE: C.H. Robinson acquisition of RXO may give a jolt to industry consolidation

In a move that may have been foreshadowed by strong upward stock movement Thursday and Friday, C.H. Robinson, the country’s biggest 3PL, is getting a lot bigger by acquiring RXO.

The transaction was announced Monday morning. 

RXO’s (NYSE: RXO) stock price had risen sharply Thursday and Friday, with it rising Friday by $2.02, a gain of 9.46% to $23.38. 

Under the terms of the deal, RXO shareholders will receive $17.25 per share in cash and 0.0856 shares of C.H. Robinson (NASDAQ: CHRW) for one share of RXO. According to the C.H. Robinson release on the transaction, given the closing C.H. Robinson price of $157.72 per share on Friday, that puts the value of each RXO share at $30.25 per share.

At approximately 7:20 a.m., after the deal was announced, C.H. Robinson’s shares in pre-market trading were down 4.89% to $150, a drop of $7.72, while RXO’s shares were up 21.86% to $28.49/share, a gain of $5.11. 

“The acquisition of RXO brings together two complementary networks and diversifies and strengthens C.H. Robinson’s multi-modal platform to accelerate its growth and increase its penetration across all modes and segments,” C.H. Robinson said in the prepared statement announcing the deal. “Combining both companies’ robust trucking brokerage and managed transportation businesses, along with C.H. Robinson’s global forwarding and RXO’s strengths in expedited and last mile, will create a more comprehensive offering for customers across a larger and denser network.”

This is a developing story,

More articles by John Kingston

FMCSA’s Elison: ‘weeks’ away from fixing Motus user experience

Daimler Truck: concerned about using cash to avoid new NoX rules

For transportation cybersecurity, AI isn’t helping fight..so far

ISEE partners with investor Holman on autonomous yard trucks

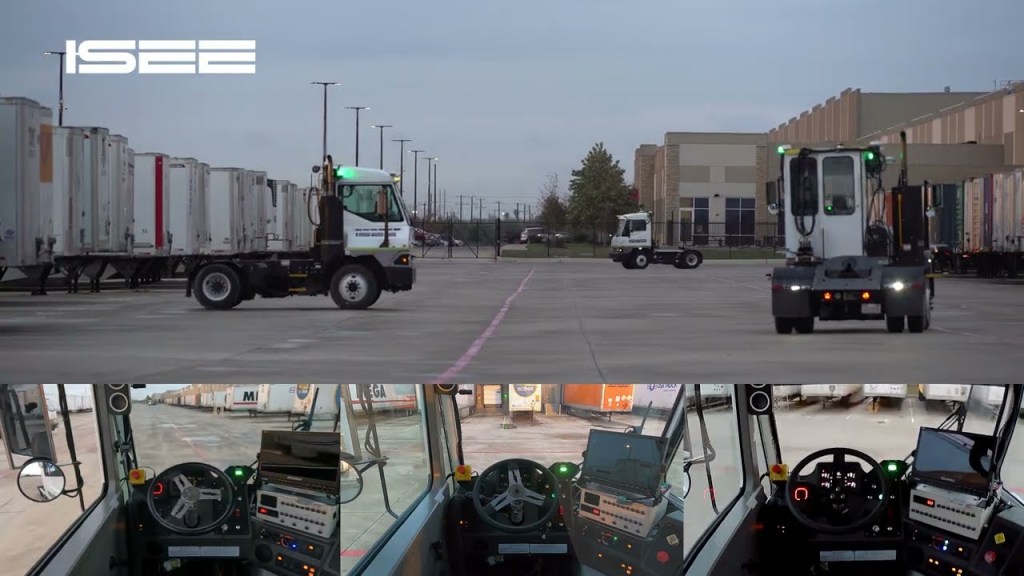
ISEE autonomous yard truck, which Holman will lease, retrofit and maintain under a new partnership

ISEE, a Cambridge, Mass.-based developer of autonomous yard trucks, announced a strategic partnership with Holman on Friday. Holman, which is also an investor in ISEE, will lease, retrofit and maintain the trucks that run ISEE’s autonomy system in North America.

Customers can put ISEE’s system on trucks they already own, on trucks leased from Holman or on autonomous-ready vehicles supplied by ISEE. Trucks will be retrofitted and integrated before delivery, with Holman’s financing and fleet management services behind them, according to ISEE’s announcement.

Debbie Yu, president and co-founder of ISEE, said customers don’t always have a fleet ready to automate.

“First of all, you have to figure out where to get the truck. Either buy it, or lease it, or rent it,” Yu said in an interview with FreightWaves. “Then we have to retrofit the truck with our autonomy kit, deploy to the customer site, do the maintenance, and run the yard.”

Most of that list involves no software at all.

Doing retrofits in-house would have meant hiring many more technicians, work Yu said falls outside ISEE’s expertise. Holman has done truck retrofitting for years and runs a nationwide network of shops and technicians alongside its leasing business, she said.

Holman launched Holman Robotics, a unit that pairs financing with lifecycle management for robotic equipment, in December 2025.

“By combining Holman’s robot fleet leasing and management infrastructure with ISEE’s autonomous technology, we can provide customers with a practical solution covering the full vehicle lifecycle,” said Joe Foster, Holman’s vice president of robotics, in a statement.

From pilots to fleets

ISEE did not need a large fleet or much retrofit capacity while it was running prototypes and pilots, Yu said. She described the company as now at an inflection point, with multiple F100 customers interested in deploying over thousands autonomous yard truck fleets with ISEE over the next couple of years. 

Retrofits and factory builds

Retrofits cover trucks already in service. New units come through OEMs, including terminal tractor maker TICO, which partnered with ISEE in April 2025.

“Not just retrofitting. We also need to do factory-built units through the TICO collaboration, starting from 2027,” Yu said.

That timing matches the 2027 serial production target FreightWaves reported in June. ISEE will also keep working with other yard truck OEMs on new diesel, alternative-fuel and electric models, according to the release.

Yu said retrofits let operators of yard trucks already working in customer yards automate sooner.

Demand is rising as manufacturing, data centers and infrastructure grow in the United States, Yu said, including from enterprise customers “that we never imagined before.”

“We believe it’s critical to actually align the partnership quickly,” she said.

Triumph Financial CEO on Freight Credit Risk

Freight credit risk in 2024 is the focus as Triumph Financial’s Aaron Graft joins FreightWaves to break down what he’s seeing. Graft, founder, vice chairman and CEO of Triumph Financial, talks through the freight finance backdrop, market pressure points and what carriers, brokers and shippers should be watching now. If you operate in trucking, payments, factoring or freight tech, this is a straight look at the risk picture from one of the biggest finance players in the space.

While much of the freight industry has characterized the brokerage model as under siege, data from Triumph Financial’s new Mile Marker report tells a more complex story. Brokers generating more than $100 million in annual revenue — those moving over 500,000 loads per year — grew their volume 15% year over year, a sign that enterprise shippers are consolidating routing guides toward larger intermediaries. But smaller brokers, those between $10 million and $50 million in annual revenue, grew their margin by 37% over the same period.

“The narrative out there in the marketplace is the brokerage model is under assault,” said Aaron Graft, CEO of Triumph Financial. “I understand why people are arriving at that generalization. I just do not think it is true.”

“Volume is vanity, profits are sanity. And so I think there’s going to be winners in multiple cohorts.”

Graft attributed smaller brokers’ margin gains to their positioning in the spot market on both sides of the transaction, particularly their relationships with small and medium-sized businesses. He argued that winning in freight is not defined solely by volume growth or landing enterprise shipper accounts, but by earning one’s cost of capital — something compliant operators are finally approaching for the first time in years.

On the carrier side, Graft said new carrier formation has stalled in a way he has not seen in previous upcycles. Drivers earning 70 cents a mile who, five years ago, would have obtained their own operating authority are instead staying put, deterred by heightened compliance requirements, insurance scrutiny, and the difficulty of getting freight tendered to new authorities in a post-litigation-risk environment. Graft referenced CDL enforcement, English language proficiency rules, and ELD compliance as compounding barriers. “I don’t know that it’s ever been harder” to launch a new carrier, he said. The absence of new carrier formation also means the traditional relief valve that would ease capacity tightness as demand rises is no longer functioning as it historically has.

Triumph Financial has seen carrier sign-ups in its factoring and payments network increase even as the broader market shed capacity. Graft theorized that much of the capacity that exited the system had been relying on broker quick pays, which carry lower onboarding requirements than full know-your-customer vetting at a factoring company. He noted that filling a single truck with diesel now costs roughly $2,000, and that carriers unable to access working capital to cover that purchase are sitting idle even when freight rates would cover their full operating costs.

Graft also addressed the immigration enforcement environment, expressing empathy for fully documented Latino drivers who are opting out of trucking due to fear of detention. He said fleets are losing compliant drivers over concerns that, in his words, amount to myths — but fears that are nonetheless real and disruptive. He characterized federal enforcement as operating with “a broadsword, not a precision scalpel,” cutting down needed targets but also creating collateral disruption to legal operators. Both Graft and the host agreed the effect reinforces the view that this freight cycle will run longer than prior ones, with fewer natural release valves available to restore capacity quickly.

  • Brokers over $100M in revenue grew load volume 15% year over year, while brokers between $10M–$50M grew margins 37%, per Triumph Financial’s Mile Marker report.
  • New carrier formation has stalled despite rising rates, as compliance requirements, insurance scrutiny, and freight-tendering barriers deter drivers from obtaining their own authority.
  • Triumph Financial reports rising carrier sign-ups in its factoring network, with Graft theorizing that exiting ‘shadow capacity’ had relied on lower-scrutiny broker quick pays rather than traditional factoring.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.