Weekly Market Update: So far, so February
So far this February has been what we would expect. Does the normally slow month have any surprises up its sleeves?
Volumes and capacity remain flat through the first week of February. Has the freight market weathered the slowest part of the year?
Freight volumes recover as January closes. The artic air freezes the Midwest as the Chicago market heats up.
Last week had the largest single day percentage drop in volume since March of 2018. Capacity remained stable as we ride out the winter doldrums.
Capacity is abundant even though volume is relatively strong. Carriers are having little trouble covering the available freight making it a shippers’ paradise in mid-January.
The New Year has started off with a surprising amount of volume in the freight market. So far, capacity has been available to handle it. The tariff deadline extension may be providing a second wind.
The freight market has softened significantly in the last few months, but it is not due to a drastic reduction in volume.
Volume continues to slide but there was little change in the market over the past seven days.
Capacity is readily available in most regions of the country. Los Angeles has finally cooled off as the tariff deadline gets extended.
Freight activity surged prior to Thanksgiving with help from Los Angeles volume. Drivers returned to the road this week, and carriers have figured out where to position their trucks to alleviate some tightness.
With the Thanksgiving holiday approaching, drivers are spending less time on the road and more time at home. This is shrinking the availability of capacity in the market.
The freight market remains slow in most parts of the country except for one. Will it spill into other regions?
The freight market is showing the first signs of turning in over a month. Is this the start of retail season?
The freight market continues to stabilize, but there should be a little fuel left in the tank for one more seasonal push before the holidays.
October of 2018 has been very different from the same month a year ago thus far. We have had 2 major hurricanes make landfall and the economy is still strong. So why does it seem so different?
SONAR’s signature index has a birthday; Ocean Network Express to lose $600M; oilfield service companies guide for tight margins in Q3; President Trump bails on coal industry incentives; pros and cons of blockchain in container shipping; spending 60,000 hours reverse-engineering a Tesla Model 3.
Truckload volume continues to decline to annual lows after the first week of October. Freight volume is redistributing out west as Michael hits the Southeast U.S.
The Dow Jones Industrial Average plummeted today, posting its biggest loss since May 29; meanwhile the S&P 500 is on a losing streak that hasn’t been matched in upwards of 2 years.
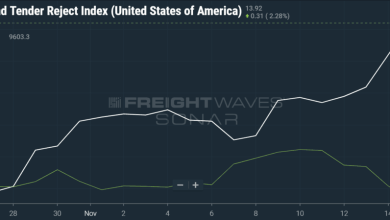
FreightWaves triples the lanes available for the tender rejection indices along with diesel price and volume data. Highly regarded Institute for Supply Management indices have also been added to deepen the macro-economic section.
October is traditionally a slower month than the 4 preceding it in terms of volume. This year it has happened as soon as the calendar turned. This seasonal swing does not mean it will be a quiet fourth quarter for everyone.