The ‘ingenious strategy’ behind most truckers’ least favorite week of the year: International Roadcheck

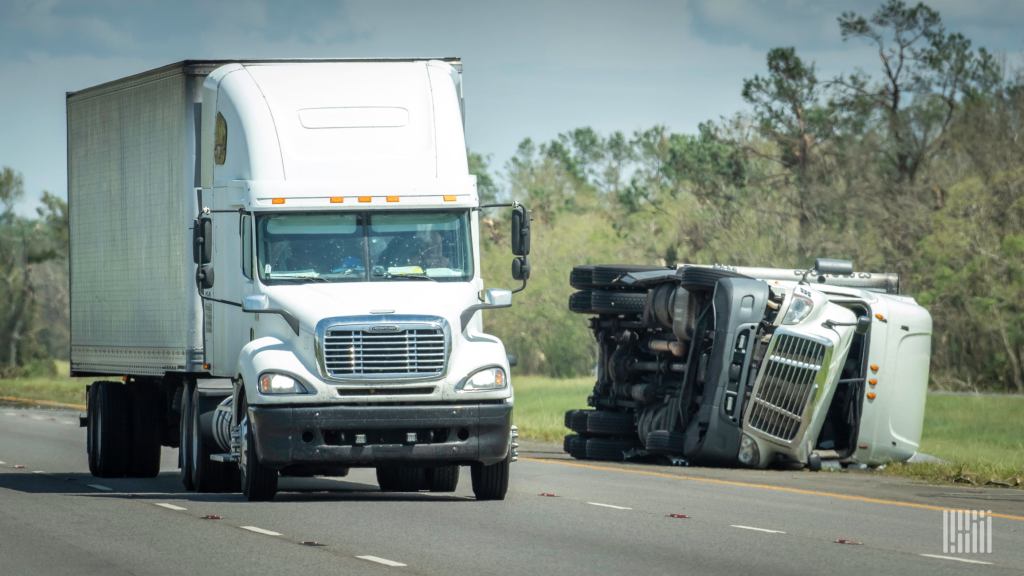
truck fallen over

International Roadcheck Week is hardly the sexiest topic in trucking, but it is a darn-tootin’ important one. Inspectors in the U.S. and Canada halt tens of thousands of trucks for vehicle inspections for a few days every summer or early fall. They remove thousands of trucks and drivers from the road; in 2021, 16.5% of inspected vehicles were put out of service along with 5.3% of drivers.

It’s uncommon for truck drivers to actually get their vehicles inspected at random during most of the year. To avoid International Roadcheck Week, many truckers simply don’t drive during that period of time — which, presumably, means more unsafe vehicles and drivers on the road outside of the inspection blitz. It’s a question that ate at Andrew Balthrop, a research associate at the University of Arkansas Sam M. Walton College of Business. 

Around 5% fewer one-person trucking companies are active during International Roadcheck Week. But Balthrop and his fellow researcher, Alex Scott of the University of Tennessee, found a major upside to the inspection blitz — even with all the folks who avoid it. According to their working paper published in March 2021, vehicles are safer a month before and after the inspection period. There’s a 1.8% reduction of vehicle violations, according to Balthrop and Scott’s analysis. Surprise inspection blitzes don’t result in the same uptick of compliance. 

I caught up with Balthrop about his research last week at FreightWaves’ Future of Supply Chain conference, and we chatted again on the phone this week about his findings on International Roadcheck Week.

Enjoy a bonus MODES and a lightly edited transcription of our phone interview: 

FREIGHTWAVES: For our readers who are not aware of what Roadcheck Week actually is, can you explain a little bit about what it and why it is important to drivers and companies?

BALTHROP: “The International Roadcheck is part of an alliance between the inspectors in Canada and the ones in Mexico and the U.S. to have a unified framework for making sure trucks are safe to operate. That should make it easier to go across borders when you have this kind of unified structure.

“In the U.S., one of these CVSA inspection blitzes is the International Roadcheck that happens for three days in the summer. Usually it’s a Tuesday, Wednesday and Thursday. And usually it’s the first week in June.

“And in it, they focus on Level One inspections, the North American Standard Inspection where they inspect the driver records, the hours of service, the licensure and I believe medical records as well. Then they inspect the truck. It’s an in-depth inspection where the inspector will actually crawl under the truck to look at various things. And these inspections, from the data that I’ve seen, take about a half an hour on average.

“During the Roadcheck Week, they’ll do about 60,000 inspections, so 20,000 a day. They’re going to pull over a lot of trucks, and this can cause a little bit of congestion at the weigh stations and the roadside inspections localities as the inspectors are doing these inspections.”

Roadcheck Week doesn’t catch all truck drivers, but it has a long-lasting benefit to safety

FREIGHTWAVES: So, can most drivers kind of expect to be pulled over? How likely is that?

BALTHROP: “There’s 1 million or 3 million trucks on the road, somewhere around there on any given day. With 20,000 inspections, most drivers still will not get inspected, but there’s going to be a higher proportion of drivers inspected. 

“You’re more likely to get inspected on these days. If you don’t have a recent inspection on your record, or if you have a bad recent inspection on your record, you’re more likely to be pulled over on these days.”

FREIGHTWAVES: Your research focused on that it’s just unusual that this inspection is announced, that it’s planned. We were talking before about how normally, if you’re trying to assure quality or compliance, you would not announce an inspection in advance. It would be more of a surprise-type situation. 

Can you walk us through why that’s so unusual, or what’s the rationale that you see behind announcing it in advance?

BALTHROP: “It is unusual, and on the surface, it doesn’t make much sense, but it turns out to be kind of an ingenious strategy. So I’ll walk through it here. 

“Over the course of a year, there’ll be 2 million inspections of 3 or 4 million trucks out there. The average rate of inspections is pretty low. It’s not uncommon for truckers to go years without having an inspection. With this low inspection intensity, the FMCSA has sort of a problem of, how does it get anybody to abide by the regulations?

“I’m a jaded economist, and I don’t worry or consider too much ethics and morality and all that kind of stuff. It comes down to incentives for drivers to follow these inspections. The incentives do guide behavior. So, how could the FMCSA incentivize drivers to follow these regulations more closely and adhere to the standards?

“They do this by announcing the blitz. This does two things. On one side, it allows everybody to prepare in advance. There’s a bunch of anecdotal evidence out there that people do prepare for these blitzes in advance. They will have their trucks inspected beforehand for any problems. They’ll time maintenance and upkeep in advance to make sure that their vehicles are in order. “They’ll be a little bit more cognizant of the driver-side regulations. One thing we notice in our study is that hours-of-service violations really drop during these extensions, because people see them coming. They don’t fudge the books in any way.”

Owner-operators can evade Roadcheck Week. Big carriers, not so much.

BALTHROP: “The issue with the announcement, on the flip side, is that it allows people to just dodge the inspection entirely. For a long time, people have talked about how owner-operators and smaller carriers time their vacations for this particular time. They could do this for a couple reasons. To avoid the hassle is a nice way to put it, but it also allows you to be noncompliant to avoid the high-intensity inspections.

“You have this balance here that on one side you get the behavior you want with people complying with regulations. That’s the behavior the FMCSA wants. But on the flip side, you get a bunch of people that are kind of outright dodging inspections.

“When you compare these two things on balance, the policy is actually pretty effective because you get a lot of people focused on maintaining their trucks and obeying the rules during that particular week. Especially with the vehicle maintenance stuff, that lasts a long time. 

“In our research, we saw that vehicle violations, a month before and up to a month afterwards, is when you still notice your vehicle violations. That trucks are kind of better maintained around these blitzes.

“The ingenious aspect of it is that the FMCSA, by concentrating their inspection resources all at one time and announcing it, they’re making it clear that they’re serious about enforcing these regulations and everybody prepares for it. For the number of inspections that are happening, you get fewer tickets than you would have otherwise expected.

“The FMCSA, they’re putting people through a little bit of a hassle, but they’re not having to write a bunch of tickets to get people to comply. They’re not really punishing a whole bunch of people because, by making this apparent that this is going to happen, people comply and the FMCSA gets what they want essentially without having to come down on carriers too hard.”

A convenient time for a vacation, indeed

FREIGHTWAVES: OK, interesting. And how does this pattern of shutting down, how does that compare for an owner-operator versus a driver for a big fleet?

BALTHROP: “If you’re a motor carrier with thousands of power units, you can’t just pack up and not do business on a particular day. They just don’t have that option. So they get inspected at a higher intensity, and you see the larger carriers kind of more focused on making sure that they’re prepared for these inspections. With so many inspections, the larger carriers are going to be inspected at higher rates. You can really damage your reputation if your equipment isn’t in order on this particular day. 

“Versus the smaller carriers, especially if you’re talking about a single-vehicle fleet, an owner-operator type, it is not that difficult to just not work for those three days. And so you see a lot about that. 

“In terms of what the roadway composition looks like, if we look at inspection data and relative to a typical day with the usual inspections, on these Roadcheck days, you have about 5% fewer owner-operators on the road than you otherwise would expect.”

FREIGHTWAVES: Wow. And when you say owner-operators, you also mean just like fleets with just —

BALTHROP: “One-vehicle fleets.”

FREIGHTWAVES: OK, that’s interesting.

BALTHROP: “You know, you see a little bit of effect with the smaller fleets, below six vehicles, but it basically disappears by the time you get to a hundred vehicles.

“This effect is being driven by smaller carriers staying off the road in terms of avoidance. You see this goes also how you would expect; it’s also older vehicles that stay off the road. This is correlated with carrier size. The larger carriers use newer vehicles and owner-operators tend to use some of the older vehicles. But it’s particularly the older vehicles that are off the road.

“This makes intuitive sense. Older vehicles are more costly to keep compliant. Maintenance is more costly, and they’ve been around longer so there’s time for more stuff to have broken essentially.

How a truck driver gets stopped for inspection

FREIGHTWAVES: Can you explain a little bit more, the idea of having this inspection history and why it would benefit a larger or small carrier?

BALTHROP: “Getting flagged for inspection is sort of random, but not totally. If somebody notices something obviously wrong with your truck, that’s ground for a more in-depth inspection. Or if you get pulled over for some other reason, this can be grounds for inspection of some type. 

“But there’s also the inspection selection service. The computer program that is random, that it randomly flags people in for inspection, but it’s based on your inspection history.

“So if your firm hasn’t been inspected recently, or if your carrier doesn’t have a very dense inspection history, you’ll be more likely to trigger that system to pull you in and have you inspected. If you have a dense inspection history, you’re less likely to get inspected.”

FREIGHTWAVES: So how do you get pulled over for inspection? As a person who only drives a passenger car, my main interaction with being pulled over is, I’m driving down the freeway or wherever, and I get stopped by the police. How does it work for a truck driver? How does getting pulled over or inspected work in that way?

BALTHROP: “The law is that you cannot pass a weigh station without pulling in and getting weighed. At that point they may flag you to be inspected. Now, in the past decade or two, there’s been a bunch of electronic devices that are installed in cabs. You may have heard of PrePass or Drivewise. This allows you to pass weigh stations. 

“I don’t have data on how many trucks have the in-cab devices. But from a trucking perspective, they’re so convenient that you don’t have to stop every time you cross a state line. I think the vast, overwhelming majority of trucks have some sort of one of these electronic devices. The DOT inspectors at these roadside inspection points have a dial they can twist essentially about how many people they want to inspect. 

“So during the roadcheck inspection week, they’ll crank that dial all the way up and pull everybody over. And if they get too backed up, they might crank it back down a little bit and so on.”

FREIGHTWAVES: OK, interesting. It reminds me of a highly sophisticated E‑ZPass.

A $10 million-plus expense to trucking companies every year … but it’s worth it if just one fatal crash is avoided

FREIGHTWAVES: Zooming out, when we hear about large truck crashes, something like a vehicle maintenance issue is not really the most sexy explanation. But just looking at the FMCSA data, in 29% of all truck crashes, a major factor is brake problems. So it seems like a lot of the truck crashes on the road are caused by vehicle maintenance, versus something like the driver using illegal drugs or some other sort of more dramatic explanation. Can you speak a little bit to why this sort of vehicle maintenance is important for safety in preventing large crashes?

BALTHROP: “We did a little bit of a back-of-the-envelope cost benefit analysis of this. Let me try and make sure I remember it clearly, but we have it in the paper that the cost of this on one side is that you have the compliance costs the firms are undertaking, and then you have to add to that the delay costs from doing this, and then the cost of the inspection itself, having to pay federal inspectors to do this.

“On the benefit side, it reduces crashes. So when we add up, just looking at the cost of what an inspection is, we don’t have a good idea of how to measure the compliance cost. It’d be fun to measure the delay cost, but I don’t have good enough price data on that to get at that cost. 

“But if you look at what the cost of an inspection is, it is something like $100 or $120 is what you would pay to have one of these inspections done privately. A lot of people do this in the run-up to inspections, and have it done privately so that you can fix whatever the problems are and be sure that you would pass the FMCSA inspection.

“With that $120 figure, if you aggregate that up to 60,000 inspections or whatever, and you take that in comparison, I’m going to give you a bad figure here, it’s on the order of $10 million. That is about the value of a statistical human life. Looking at this economically, it’s worthwhile if it saves one human life. If you identify just one faulty brake system that would’ve resulted in an accident, you’re getting some value out of the program. 

“When you add those other costs in there, we’re going to need to save a couple of lives, but in terms of cost benefit analysis with this kind of stuff, we’re usually looking at orders of magnitude differences in cost and benefits to say something for sure. 

“If you can save just a couple lives, this program will pay for itself.”

Time to start inspecting in the winter

FREIGHTWAVES: Then one last question: Is there any rationale for this program happening in the summer? 

BALTHROP: “I think part of it is that for the inspectors this gets much harder and much more miserable to do in winter conditions.”

FREIGHTWAVES: That makes sense.

BALTHROP: “Inspectors are less productive. One of the things that we talk about in the paper, that they have in addition to the International Roadcheck, is that they have Brake Week where they focus a little bit more on brake inspections. You have Operation Safe Driver a little bit later on in the summer, usually in September, where it’s a little bit more focused on passenger vehicles and how they drive around these trucks.

“But there’s not one in the winter time. There’s an unannounced brake check that usually happens in May, a surprise inspection that’s just one day. But you’re right in pointing out that it might be worthwhile having one of these in the wintertime. You have this periodic high-intensity inspection that kind of incentivizes everybody to be compliant through the summer. 

“But there’s nothing in the winter, so that’s an area. But if I was managing the FMCSA, that would be one of the first questions I ask, ‘Why don’t we have one of these in the wintertime?’”

FREIGHTWAVES: That makes sense. Maybe they can do it in the South or something. Maybe a Miami January inspection … 

That’s it for this special bonus MODES. Subscribe here if you’re not already receiving MODES in your inbox every Thursday. Email the reporter at rpremack@www.freightwaves.com with your own tales on International Roadcheck Week or any other trucking topics. 
Why the Northeast is quietly running out of diesel

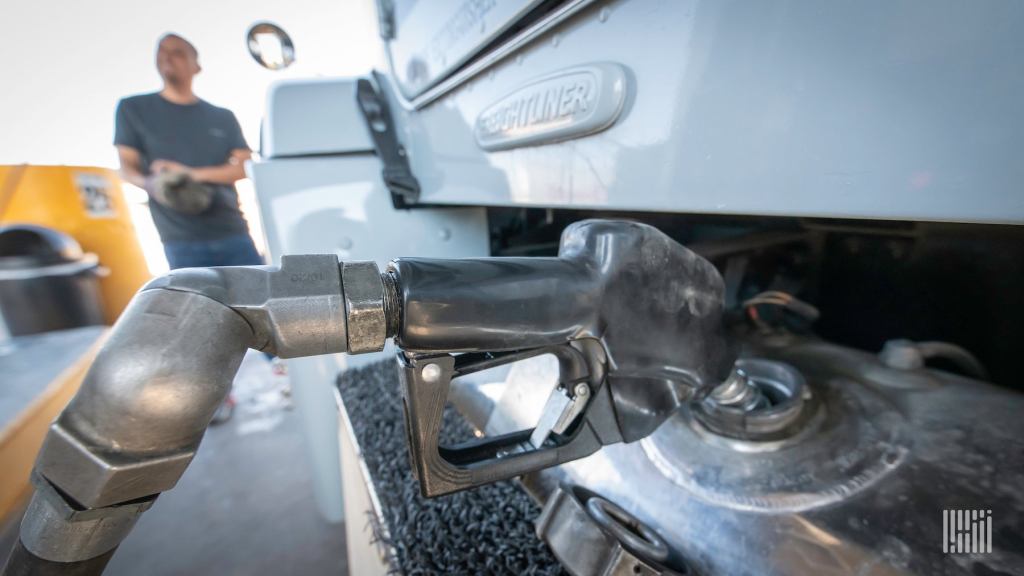
The nozzle of a diesel fuel pump is inserted into the tank of a commercial truck as its driver looks on the bankground.

The East Coast of the U.S. is reporting its lowest seasonal diesel inventory on record. And some trucking companies appear spooked.

The East Coast typically stores around 62 million barrels of diesel during the month of May, according to Department of Energy data. But as of last Friday, that region of the U.S. is reporting under 52 million barrels. 

The sharp increase of diesel prices has been a major stressor in America’s $800 billion trucking industry since the beginning of 2022. According to DOE figures, the price per gallon of diesel has reached record highs — a whopping $5.62 per gallon. It’s even higher on the East Coast at $5.90, up 63% from the beginning of this year. 

When relief is coming isn’t yet clear, and experts say higher prices are the only way to attract more diesel into the Northeast.

“I wish I had some good news for the Northeast, but it’s bedlam,” Tom Kloza, global head of energy analysis at OPIS, told FreightWaves. 

2022 has seen record-setting diesel prices. (SONAR)

Everyday Americans don’t fill up their cars with diesel, but the fuel powers our nation’s agriculture, industrial and transportation networks. More expensive diesel means the price of everything is liable to increase. Trucks, trains, barges and the like consumed about 122 million gallons of diesel per day in 2020. 

Patrick DeHaan, a vice president of communications at fuel price site GasBuddy, reported that retail truck stops are hauling fuel from the Great Lakes to the Northeast, calling it “extraordinary.” We’ve also seen anecdotal reports from truck drivers posting company memos:

Pilot Flying J and Love’s, two of America’s largest truck stops, told the Wall Street Journal yesterday that they were not planning to restrict diesel purchases, but were monitoring low diesel inventory.

Not unlike every other supply chain crunch we’ve seen in the past few years, the cause of the Northeast’s diesel shortage is multifaceted. A yearslong degradation of refineries is rubbing against the Gulf Coast preferring to ship its oil to Europe and Latin America.

Here’s a breakdown:

1. The East Coast has lost half of its refineries. 

As Bloomberg’s Javier Blas wrote on May 4 (emphasis ours): 

In the past 15 years, the number of refineries on the U.S. East Coast has halved to just seven. The closures have reduced the region’s oil processing capacity to just 818,000 barrels per day, down from 1.64 million barrels per day in 2009. Regional oil demand, however, is stronger.

Rory Johnston, a managing director at Toronto-based research firm Price Street and writer of the newsletter Commodity Context, told FreightWaves that refining is a “thankless industry,” with intense regulations that have limited the opening of new refineries. The Great Recession of 2008 led to several East Coast refineries shuttering, but there have been more recent shutdowns too. One major Philadelphia refinery shuttered in 2019 after a giant fire (and it already had declared bankruptcy), and another refinery in Newfoundland shut down in 2020.

2. It’s a financial risk to bring diesel to the Northeast.

The Northeast has increasingly relied on diesel from the Gulf region. Much of that diesel travels to the Northeast through the famous and much-adored Colonial Pipeline. You may remember the 5,500-mile pipeline from last year, when a ransomware attack shuttered it for nearly a week!  

It takes 18 days for oil to travel on the Colonial Pipeline from its source in Houston to New York City (or, more specifically, Linden, New Jersey), Kloza said.

That’s a long enough time to prioritize Colonial pipelines financially risky for traders — or, as Kloza said, “incredibly dangerous” — thanks to a concept called “backwardation.”

Backwardation refers to the market condition in which the spot price of a commodity like diesel is higher than its futures price. It’s only gotten stronger over time in the diesel market, Kloza said. So, a company could send off a shipment of diesel and find that it dropped by $1 per gallon in the time the diesel traveled from the Gulf Coast to New York — er, New Jersey. That could mean hundreds of thousands or more in lost profits, so traders often avoid such a fate.

“We’re not in an era where there are any U.S. refiners or big U.S. oil companies who would ‘take one for the team’ and bring cargo in where it’s needed,” Kloza said. 

The desperation is showing in New England and the mid-Atlantic regions. New England diesel retail prices are up 75% from the beginning of 2022, per DOE data. In the mid-Atlantic, diesel is up 67%. 

It’s not worth the risk, even amid ultra-high prices. As FreightWaves’ Kingston reported last week, the spread between a gallon of diesel in the Gulf Coast and its New York harbor price is usually a few cents. Last week, that swung up to 66 cents.

But that uptick still isn’t justifying moving oil to the Northeast — particularly when traders can make so much more money selling diesel abroad. 

3. Of course, we can blame COVID and the crisis in Ukraine. 

The catalyst for this diesel shortage, of course, is the ongoing conflict in Ukraine — particularly Europe’s desperation for diesel after weaning off Russian molecules. 

As CNBC reported in March, Europe is a net importer of diesel. Europe consumed some 6.8 million barrels of diesel each day in 2019; Russia exported some 600,000 barrels per day of that. Today, Europe has only eliminated one-third of its Russian diesel, so prices are expected to continue to climb amid that transition. Latin America, too, has been clammoring for U.S. diesel.

The Gulf Coast has been happy to provide such diesel, amid “insane” prices for diesel abroad, said Johnston. Waterborne exports of diesel from the U.S. Gulf Coast hit record highs last month, according to oil analytics firm Vortexa. (The records only date back to 2016.)

Naturally, COVID is also to blame for the Northeast’s run on diesel. Those refineries still retained on the East Coast scaled back during the pandemic due to staffing issues. It takes six months to a year to reignite refineries that were previously shuttered, Kloza said.

The ‘everything shortage’ endures

It’s been a tale as old as, well, last year. An industry is quietly hampered by supply issues for years, or even decades, and COVID pulls back the curtains on its unsteady foundation. It’s particularly jarring for commodities we never thought about before, like shipping containers or pallets, but that quietly underpinned our livelihood all along. 

Recall the Great Lumber Shortage of 2020? Big Lumber had unusually low stockpiles of wood by the summer of 2020, thanks to a vicious 2019 in the lumber industry shuttering sawmills and the spring of 2020 sparking staffing issues. (There was also a nasty beetle infestation.) Those in lumber expected the pandemic to slow the economy, not ignite online shopping, construction and housing mania. It meant lumber went from around $350 per thousand board feet pre-pandemic to a crushing $1,515 by the spring of 2021. The lumber price roller coaster persists today.  

In diesel, there’s no beetle infestation, but there are plenty of other headaches. It all means higher fuel prices on the East Coast, particularly the Northeast, to lure molecules from the Gulf Coast. And, down the line, probably more expensive stuff for you. 

Do you work in the trucking industry? Do you want to say that you hate or love MODES? Are you simply wanting to chitchat? Email the author at rpremack@www.freightwaves.com, and don’t forget to subscribe to MODES.

Updated on May 13 with the latest comments from truck stops.

Exclusive: Central Freight Lines to shut down after 96 years

Nearly, 2,100 employees will be laid off right before Christmas. Central Freight Lines is the largest trucking company to close since Celadon ceased operations in 2019.


Waco, Texas-based Central Freight Lines has notified drivers, employees and customers that the less-than-truckload carrier plans to wind down operations on Monday after 96 years, the company’s president told FreightWaves on Saturday.

“It’s just horrible,” said CFL President Bruce Kalem.

A source close to CFL told FreightWaves that CFL had “too much debt and too many unpaid bills” to continue operating, despite exploring all available options to keep its doors open.

Kalem agreed.

“Years of operating losses and struggles for many years sapped our liquidity, and we had no other place to go at this point,” Kalem told FreightWaves. “Nobody is going to make money on this closing, nobody.” 

Central Freight will cease picking up new shipments effective Monday and expects to deliver substantially all freight in its system by Dec. 20, according to a company statement.

A source familiar with the company said he is unsure whether CFL will file Chapter 7 or “liquidate outside of bankruptcy,” but that the LTL carrier has no plans to reorganize.

The company reshuffled its executive team nearly a year ago in an effort to stay afloat, including adding the company’s owner, Jerry Moyes, as CFL’s interim president and chief executive officer. Moyes remained CEO after Kalem was elevated to president in July.

“I think it was surprising that there wasn’t a buyer for the entire company, but buyers were interested in certain pieces but not in the whole thing,” the source, who didn’t want to be identified, told FreightWaves. “Part of it could have been that just the network was so expansive that there was too much overlap with some of the buyers that they didn’t need locations or employees in the places where they already had strong operations.”

Third-party logistics provider GlobalTranz notified its customers that it had removed CFL as “a blanket and CSP carrier option immediately, to prevent any new bookings,” multiple sources told FreightWaves on Saturday.

CFL, which has over 2,100 employees, including 1,325 drivers, and 1,600 power units, is in discussions with “key customers and vendors and expects sufficient liquidity to complete deliveries over the next week in an orderly manner,” a CFL spokesperson said. Approximately 820 employees are based at the company headquarters in Waco.

Despite diligent efforts, CFL “was unable to gain commitments to fund ongoing operations, find a buyer of the entire business or fund a Chapter 11 reorganization,” another source familiar with the company told FreightWaves.

Kalem said the company had 65 terminals prior to its decision to shutter operations. 

FreightWaves received a tip from a source nearly two weeks ago that CFL wasn’t renewing its East Coast terminal leases but was unable to confirm the information with CFL executives. 

Another source told FreightWaves that some of the LTL carrier’s West Coast terminals had been sold recently, but that no reason was given for the transactions.

At that time, Kalem said the company was “working to find alternatives” and couldn’t speak because of nondisclosure agreements. He said executives at CFL, including Moyes, were trying to do everything to “save the company.”

“Jerry [Moyes] pumped a lot of money into the company, but it just wasn’t enough,” Kalem said.

Kalem said he’s aware that a large carrier is interested in hiring many of CFL’s drivers but isn’t able to name names at this point. 

“Central Freight is in negotiations to sell a substantial portion of its equipment,” the company said in a statement. “Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area.”

As of late Saturday night, Kalem said fuel cards are working and drivers will be paid for freight they’ve hauled for the LTL carrier until all freight is delivered by the Dec. 20 target date.

“I’m going to work feverishly with the time I have left to get these good people jobs — I owe it to them,” Kalem told FreightWaves. “We are going to pay our drivers — that’s why we had to close it like we’re doing now. We are going to deliver all of the freight that’s in our system by next week, and we believe we can do that.”

During the outset of the pandemic, Central Freight Lines was one of four trucking-related companies that received the maximum award of $10 million through the U.S. Small Business Administration’s Paycheck Protection Program (PPP). This occurred around the time that CFL drivers and employees were forced to take pay cuts, a move that didn’t go over well with drivers.

“It all went to payroll,” Kalem said about the PPP funds. “Yes, our employees and drivers did take a pay cut over the past few years, and we gave most of it back, even raised pay over the past several months, but it just wasn’t enough to attract drivers.”

FreightWaves staffers Todd Maiden, Timothy Dooner and JP Hampstead contributed to this report.


Watch: Central Freight Lines’ impact on the LTL market


FreightWaves CEO and founder Craig Fuller reacts to the Central Freight Lines news:

“With Central struggling for many years and unable to reach profitability, it makes sense that they would want to liquidate while equipment and real estate are fetching record prices.”


Central Freight Lines statement

Here is the statement given by Central Freight Lines to FreightWaves late Saturday after reports surfaced of its impending closure:

“We make this announcement with a heavy heart and extreme regret that the Company cannot continue after nearly 100 years in operation. We would like to thank our outstanding workforce for persevering and for professionally completing the wind-down while supporting each other. Additionally, we thank our customers, vendors, equipment providers, and other stakeholders for their loyalty and support.

“The Company explored all available options to keep operations going. However, operating losses sapped all remaining sources of liquidity, and the Company’s liabilities far exceed its assets, all of which are subject to liens in favor of multiple creditors. Despite diligent efforts, the Company was unable to gain commitments to fund ongoing operations, find a buyer of the entire business, or fund a Chapter 11 reorganization. Given its limited remaining resources, the Company concluded that the best alternative was a safe and orderly wind-down. As we complete the wind-down process, our primary goal will be to offer the smoothest possible transition for all stakeholders while maximizing the amount available to apply toward the Company’s obligations.

“Central Freight is in negotiations to sell a substantial portion of its equipment. Additionally, Central Freight is coordinating with other regional LTL carriers to afford its employees opportunities to apply for other LTL jobs in their area. Discussions are ongoing and no purchase of assets or offer of employment is guaranteed.”


Brief history of Central Freight Lines

1925Founded in Waco, Texas, by Woody Callan Sr.
1927Institutes regular routes in Texas between Dallas, Fort Worth and Austin.
1938Dallas facility opens as world’s largest freight facility.
1991Receives 48-state interstate operating authority, expands into Oklahoma.
1993Joins Roadway Regional Group and begins service in Louisiana.
1994Expands into Colorado, Kansas, Missouri, Illinois and Mississippi.
1995Consolidation of Central, Coles, Spartan and Viking Freight Systems into Viking Freight Inc. is announced. Central’s Waco corporate HQ starts closure.
1996Becomes the Southwestern Division of Viking Freight Inc.
1997Investment group led by senior Central management purchases assets of former CFL from Viking Freight and reopens as a new Central Freight Lines.
1999Expands into California and Nevada.
2009CFL Network provides service to Idaho, Utah, Minnesota and Wisconsin.
2013Acquires Circle Delivery of Tennessee.
2014Acquires DTI, a Georgia LTL carrier.
2017Acquires Wilson; new division created with an increase of 80 terminals.
2020Wins Carrier of the Year from GlobalTranz.
Acquires Volunteer Express Inc. of Dresden, Tennessee.
Source: Central Freight Lines

Warehouse cramming is about to begin — Freightonomics

nVision Global, is a leading Global Freight Audit, Supply Chain Management Services company offering enterprise-wide supply chain solutions. With over 4,000 global business “Partners”, nVision Global not only provides prompt, accurate Freight Audit Solutions, but also providing industry-leading Supply Chain Information Management solutions and services necessary to help its clients maximize efficiencies within their supply chain. To learn more, visit www.nvisionglobal.com

Warehouse space is at a premium right now and with peak season right around the corner, shippers are starting to scramble for space. 

Zach Strickland and Anthony Smith look into what shippers are doing to prepare for the end-of-year crunch. They welcome Zac Rogers from Colorado State University to the show to talk through the industry tightness. 

The three also talk about the latest Logistics Managers Index results and what they mean for the fourth quarter of 2021. 

You can find more Freightonomics episodes and recaps for all our live podcasts here.

Seasonality pushing rejections and rates higher ahead of the Fourth

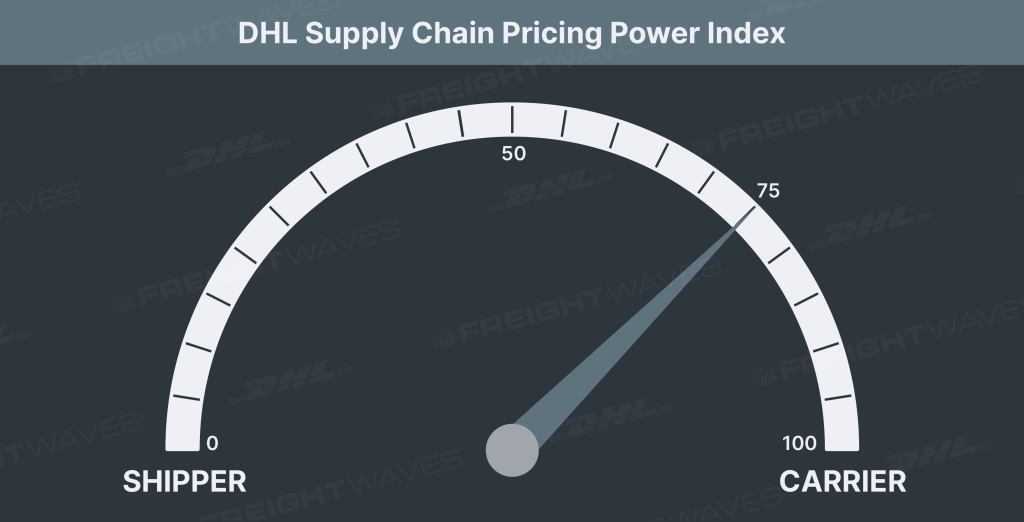
This week’s DHL Supply Chain Pricing Power Index: 75 (Carriers)

Last week’s DHL Supply Chain Pricing Power Index: 70 (Carriers) 

Three-month DHL Supply Chain Pricing Power Index Outlook: 70 (Carriers)

The DHL Supply Chain Pricing Power Index uses the analytics and data in FreightWaves SONAR to analyze the market and estimate the negotiating power for rates between shippers and carriers. 

The Pricing Power Index is based on the following indicators:

Load volumes: Absolute levels positive for carriers, momentum neutral

The Outbound Tender Volume Index at 15,980 is nominally higher now than basically at any point in the past 12 months with the exception of the week prior to Thanksgiving/Black Friday last year. OTVI captures all electronic tenders, including rejected ones, so when accounting for the rejection rate, we can get an even more accurate look at volumes. 

OTVI rose through the back half of May into the national holiday and has risen even further since. Throughout the back half of May and into the middle of June, tender rejections declined substantially. Meaning, current volume throughput is actually understated when comparing OTVI now to OTVI in November 2020. After adjusting for rejected tenders, the accepted outbound tender volume index is just 2.2% below the 2020 peak in November. At that time, OTVI surged towards 17,000, but the rejection rate moved in-kind towards its natural ceiling of 28%. So, the total accepted freight tenders in mid-June is comparable to the peakiest of peak seasons in 2020. Incredible. 

However, since the middle of June, tender rejections have begun increasing again heading into Independence Day, a time when many drivers spend time off the road with their families. The move higher in OTVI this week has been driven primarily by higher rejection rates, rather than higher freight demand. 

Over the past month, the drivers of freight volumes have continued to be imports and from just about every port. The west coast continues to provide seemingly non-stop container ships, while Houston, New Orleans, Miami and Savannah are seeing very strong throughput as well. 

It is van volumes that are driving freight markets higher right now. The Reefer Outbound Tender Volume index has tumbled 25% since its all-time high in the weeks after the polar vortex in February. Since Memorial Day, ROTVI has fallen another 10.5%. This is likely a factor of declining grocery demand, but I would expect the trend to reverse course in the near future as summer festivities accelerate. 

Dry van volumes pushed higher in the back half of May and into June while reefer volumes have declined significantly. 

SONAR: VOTVI.USA (Blue); ROTVI.USA (Green)

The congestion at our nation’s ports has spread from Los Angeles and Long Beach to Oakland, California. The California coastline is a parking lot of container ships, most of which are full to the brim with imports, awaiting berth. As detailed in the economic section, there are some signs that the reversion is underway with Americans paring back spending on pandemic superstar categories in favor of airlines, lodging and entertainment. But spending remains strong despite the moderation, and low inventory levels offset much of the decline that will occur from slowing demand. Real inventories are 3% higher now than pre-pandemic, but real sales growth is far outpacing inventory growth, leading to the lowest inventory-to-sales ratio in decades. 

On the manufacturing side, the ISM Manufacturing PMI expanded in May after declining in April. We’ve been in expansionary territory for 12 consecutive months. New orders, production, imports/exports and employment are all growing. The major issues should come as no surprise: Deliveries are slowing, backlogs are growing and inventories are too low. 

In all, there are many, many catalysts to keep freight demand strong for the foreseeable future. Americans are traveling and spending on services at a high clip, but the high savings rate is enabling it to occur without a massive detriment to goods spending. 

SONAR: OTVI.USA (2021 – Blue; 2020 – Green; 2019 – Orange; 2018 –  Purple)

Tender rejections: Absolute level and momentum positive for carriers

After declining steadily from mid-March to mid-May, the Outbound Tender Reject Index has reversed course heading into Independence Day. This is typical for a national holiday as carriers selectively choose loads to bring drivers closer to home. OTRI now sits above 25% for the first time in June. 

One of our newest indices in SONAR gives us the ability to compare markets on as close to an apples-to-apples basis as possible. FreightWaves’ Carrier Trend Market Score indices are divided into two perspectives – shipper/broker and carrier. The scores are positioned on a scale from 1-100 and have values measuring van and refrigerated (reefer) capacity. The higher values represent more favorable trends for whichever perspective. For instance, a value near the high-end of the range would suggest very favorable conditions for carriers in our carrier capacity trend score index. 

For the past several weeks, capacity disparities have been driven by import volumes. The markets with the tightest carrier capacity coincide with the nation’s busiest ports. Ontario, California, Savannah, Georgia, and Atlanta all have carrier capacity trend market scores of 100. 

SONAR: Capacity Trend Market Score (Carriers – VAN)

By mode. Reefer rejection rates tumbled from it’s all-time high in March to under 35% in mid-June before popping higher over the past two weeks. Reefer rejections are still quite high from a historical standpoint at 38%, but are significantly lower than just three months ago when reefer carriers were rejecting half of all electronically tendered loads. 

SONAR: VOTRI.USA (Blue); ROTRI.USA (Orange)

Dry van tenders make up the majority of all tenders, so the van rejection rate mirrors the aggregate index closely. Van rejections have surged from ~23% to ~26% over the past two weeks. 

Yes, one-in-four loads being rejected is not ideal, but it’s better than 30%. I am unaware of any meaningful signals that capacity is being added at a rate that would change my outlook. With so many catalysts for demand, and many constraints on drivers including the Drug & Alcohol Clearinghouse, driver training school closures and continued government unemployment benefits, the outlook is tight throughout this year and into 2022. That’s not to say we won’t see improvement as consumers revert to pre-pandemic spending habits and drivers enter or reenter the market. But I’m not expecting any quick reversal of this environment; there are simply too many catalysts driving volume and suppressing capacity. 

SONAR: OTRI.USA (2020/21 – Blue; 2020 – Green; 2019 – Orange)

Freight rates: Absolute level and momentum positive for carriers

Throughout June, spot rates have moderated while contract rates have pushed higher. The Truckstop.com dry van rate per mile (incl. fuel) has fallen from $3.21 to $3.11 since the beginning of June, while FreightWaves van contract rates have risen from $2.50 to $2.59/mile, exclusive of fuel. 

I still believe the Truckstop.com dry van national average will not retest the post-vortex surge pricing that brought spot rates up to an all-time high of $3.30. But, there aren’t many catalysts to bring spot rates down anytime soon either. Demand is unwavering with continued strong consumer goods demand, humming industrial recovery and a potentially cooling, yet still sizzling, hot housing market. And carriers can’t fill enough trucks to keep up with demand. 

Prior to the seasonal movements we’re seeing in tender rejections, routing guides generally had been improving through Q2. We should continue to see a convergence between spot and contract rates, but spot rates will remain historically very elevated throughout the summer as demand simply outstrips capacity. 

SONAR: TSTOPVRPM.USA (Blue); VCRPM1.USA (Green)  

Economic stats: Momentum and absolute level neutral

Several economic releases this week are worth noting.

Weekly jobless claims were released Thursday and give us one of the best close-to-real-time indicators of the overall economy.  This week, the data was again very promising as the labor market continues on a bumpy but trajectorially stable recovery path. 

First-time filings totaled 411,000 for the week ended June 19, a slight decrease from the previous total of 418,000 but worse than the 380,000 Dow Jones estimate, the Labor Department reported Thursday. Initial claims have held above 400,000 for consecutive weeks after falling to a pandemic low of 374,000 three weeks ago. As things stand, the current level of initial claims is about double where it was prior to the Covid-19 pandemic. 

The good news on the jobs front is that continuing claims are on the decline, falling to 3.39 million, a drop of 144,000. That number runs a week behind the headline claims total.

Initial jobless claims (weekly in May 2020-May 2021)

At the time of writing, the newest weekly data for the week ending May 29 had not been updated in SONAR. This week, claims fell from 405,000 to 385,000. 

SONAR: IJC.USA

Consumer. Turning to consumer spending, as measured by Bank of America weekly card (both debit and credit) spending data, total card spending (TCS) in the latest week accelerated to 22% over 2019. This is the first time in June that TCS has topped 20% over 2019, but spending has been running up 16-19% consistently on a two-year comp for months. For contect, the average pre-pandemic two-year growth rate was about 8% (from 2012 to 2019). 

The Bank of America team highlighted service spending in the nation’s two largest state economies, California and New York, which are now fully reopened. Spending at restaurants is now well above 2019 in both states, and the team believes there is more capacity for spending to accelerate in the states that were slower to reopen given pent-up demand. 

There was also a notable acceleration in spending on clothing this week, according to Bank of America. It could be a reversal from some softening in the early weeks of June, or an indication of people refreshing wardrobes ahead of a return to work, more travel and vacations. One tepid statement for freight markets from this week;s report: Leisure spending is on the rise and durable goods spending is flatlining.  

FreightWaves’ Flatbed Outbound Tender Reject Index, both a measure of relative demand and capacity, moves directionally with the ISM PMI. 

SONAR: ISM.PMI (Blue); FOTRI.USA (Green) 

Manufacturing. Over the past two weeks, regional manufacturing surveys have reported generally positive readings amid logistical challenges. The New York Fed’s Empire State business conditions index declined 6.9 points to 17.4 in June, retreating from strong readings the past two months. The Empire State Index is a diffusion index with a baseline of zero; any reading above zero indicates improving or expansionary conditions. 

Delivery times lengthened to a new record during the month, new orders and shipments fell, and inventories entered negative territory. The supply chain and transportation challenges are as visible upstream as downstream, but overall the manufacturing sector is handling. Growth continued throughout the second quarter in both the Empire State and Philly Fed indices. 

The Philadelphia Federal Reserve’s business activity index edged lower to a still robust 30.7 in June from 31.5 in the prior month. Unlike NY, the pace of shipments growth accelerated in the Philly region during June. The employment subcomponent rose to a very healthy 30.7 from 19.3 last month, the regional bank said. 

Record-long lead times, wide-scale shortages of critical basic materials, rising commodities prices and difficulties in transporting products are continuing to affect all segments of the manufacturing economy, but demand remains strong. 

For more information on the FreightWaves Freight Intel Group, please contact Kevin Hill at khill@www.freightwaves.com or Andrew Cox at acox@www.freightwaves.com.

Check out the newest episodes of our podcast, Great Quarter, Guys, here.

Project44 acquires ClearMetal to strengthen predictive tools

Project44, a leader in real-time visibility of the global supply chain, announced on Thursday it has acquired ClearMetal, a San Francisco-based supply chain planning software company that focuses on international freight visibility, predictive planning and overall customer experience. The terms of the acquisition were not disclosed.

ClearMetal, founded by top software engineers and data scientists from Stanford, Google and other Silicon Valley elites, has created a “continuous delivery experience” that leverages proprietary machine learning algorithms that can forecast supply chain disruptions. 

In an interview, Jason Duboe, chief growth officer at project44, explained that bringing in ClearMetal’s elite team is essential for the company’s future predictive solutions.

“Their team construct is fundamentally different. When you look at their data science, machine learning and computer science background, they are best in class,” he said. “Applying the team to solve really interesting challenges, starting with highly predictive ETA and deeper exception management to create more predictive analytics is really a key component here.”

Project44 recently acquired Ocean Insights to gain global supply chain vessel visibility and has announced it has expanded its truckload tracking services within Asia. Bringing on this new team of engineers will allow the company to capitalize on strong predictive tools, strengthening the supply chain of its customers.

“We’re going to be expanding deeper into Asia, and from a port perspective, getting data much earlier than competitors,” explained Duboe. “Our freight forwarder integrations will give us much deeper visibility from an end-to-end perspective in these regions.”

Along with the acquired skills the ClearMetal team will bring to project44, it brings a large book of customers, including large CPGs, retailers, manufacturers, distributors and chemical companies. These advanced use cases will strengthen the predictive planning tools, and project44 continues to expand into different customer markets.

“What we gain from ClearMetal is a holistic platform for anybody that joins the platform in the future,” said Duboe. “They have large customers with incredibly demanding and advanced use cases. So when it comes to order and inventory, functionality, supplier onboarding, and moving upstream into those processes, we can capture exceptions earlier on.”

Click here for more articles by Grace Sharkey.

Related Articles:

Project44 expands real-time visibility into China

Project44 reels in Ocean Insights in ‘largest acquisition in visibility space’

‘Project44’s vision has always been global’

LA-Long Beach port strike risk grows as employers say ILWU talks stalled

A contract dispute involving about 250 union watchmen could disrupt cargo movement at the ports of Los Angeles and Long Beach as early as this Saturday, with the Pacific Maritime Association reporting little progress in the latest negotiations with International Longshore and Warehouse Union Local 26.

According to a statement Wednesday from the PMA, talks ended Tuesday with little to no movement from the union on the employer association’s proposals. The ILWU has already held a strike vote and has indicated it is unwilling to extend its contract beyond its expiration at 12:01 a.m. Saturday, PMA said.

The two sides are scheduled to return to the bargaining table Friday, leaving a narrow window to reach an agreement before the deadline. 

Concerns are heightened that ILWU dockworkers would honor pickets set up by the watchmen, all but shutting down some cargo operations.  

Employers said its offer includes a one-time $3,200 bonus for each local member and a wage proposal that would increase average annual earnings for full-time watchmen from more than $170,000 to $198,000.

The proposal would also maintain fully employer-paid healthcare for active workers and retirees, which PMA values at more than $62,000 annually, and increase annual pension benefits to as much as $93,200 for workers with the longest tenure.

PMA said negotiations have continued for more than a year, most recently with assistance from the Federal Mediation and Conciliation Service. The association said it secured a several-week contract extension to allow further negotiations, but that the union participated in bargaining on only three days during that extension.

The association also said Local 26’s demands have not materially changed since negotiations began. 

FreightWaves has reached out to the union for comment.

Local 26 represents unarmed watchmen who perform security duties at six container terminals across the two ports. Their work includes checking identification and credentials at terminal entrances, conducting routine patrols and reporting security or safety concerns.

Although the watchmen account for about 2% of the ports’ ILWU workforce, PMA said the terminals where they work handle more than half of the two ports’ combined cargo, including roughly 85% of cargo at Long Beach and 33% at Los Angeles.

PMA expects thousands of longshore workers, marine clerks and foremen who are not involved in the contract dispute to honor a Local 26 picket line. That could significantly expand the effects of a watchmen’s strike, interrupting cargo handling well beyond the bargaining unit itself.

Potential consequences include idle truck drivers, disrupted rail shipments and reduced hours for warehouse workers. Exporters, including farmers and manufacturers, could face shipping delays, while retailers and small businesses preparing for the holidays could encounter delayed deliveries and higher costs.

Employers quoted data from maritime and aviation analyst Martin Associates that found the six terminals where Local 26 members work handled about 6.2 million containers in 2025, generating 50,000 direct jobs and supporting nearly 4.2 million jobs nationwide.

The analysis linked that cargo volume to $885 billion in national economic activity, $48 billion in federal taxes and $190 billion in personal income. 

Martin warned that losses would grow exponentially the longer a strike continued, as vessels could not be unloaded and containers already inside terminals could not be cleared.

Why it matters: The dispute’s potential impact extends far beyond the roughly 250 watchmen negotiating a contract. If other dockworkers honor picket lines, a strike could interrupt terminals handling a substantial share of cargo at the nation’s busiest port complex, with effects cascading through the supply chain.

Read more articles by Stuart Chirls here.

Read more:

Maersk and Hapag-Lloyd restore Asia-Europe Suez routes as U.S. shippers watch capacity and costs

Red Sea overcapacity looms as ocean container spot rates still 50% above year-ago 

Truck access and wharf upgrades part of $10.3B infrastructure plan at Port of New York and New Jersey

U.S. container imports hit record 2.67 million TEUs in October as port delays rise

Tanker strikes cruise riverboat in New Orleans

From more footage to more focus: Find your fleet’s videosafety stage

Cameras can show what happened on a route. Whether they help a driver avoid the next
collision depends on two things: what the camera tells the driver on the road and what
your safety team does with the footage afterward.


Fleet safety managers know the pattern. Footage builds up faster than anyone can
review it, investigations crowd out coaching and leadership wants proof that the
program is working. Adding cameras won’t solve that on its own. The fix is a clear plan
for what to review, how to coach and what to measure.


Answer the four questions below to find your fleet’s video safety maturity stage, then
use the guidance for that stage to choose your next step. Treat the result as a starting
point for planning.

Four questions to assess your program


Choose the answer that best describes how your fleet works today.

  1. When do you usually talk with a driver about a safety issue?
    • Only after a collision or another incident.
    • When we review video or telematics data to establish fault or support a claim.
    • When in-cab voice coaching flags a behavior and a manager follows up on patterns.
    • Before an incident occurs, when risk insights flag a driver for attention.
  2. How does your team find safety events to review?
    • Only after a collision or another incident.
    • When we review video or telematics data to establish fault or support a claim.
    • When in-cab voice coaching flags a behavior and a manager follows up on patterns.
    • Before an incident occurs, when risk insights flag a driver for attention.
  3. How connected is your video data to the rest of your fleet operations?
    • Video and telematics live in separate systems, if we have telematics at all.
    • Our cameras are cloud-connected, but we use them mainly to record evidence.
    • Video events sit alongside engine and driving data in one platform, which gives context for coaching.
    • Video, telematics and predictive analytics work together to estimate collision risk.
  4. How do you show the value of your video program?
    • We don’t measure it formally because cameras are mainly an insurance requirement.
    • We track driver exonerations, dismissed claims and liability savings.
    • We track changes in specific risky behaviors and completed coaching sessions.
    • We track fleet collision rates and total cost of risk against a baseline or benchmark.

Stage 1: Reactive


Your cameras record incidents, but footage usually comes out only after something
goes wrong. By then, you may be dealing with an injured driver, a damaged vehicle and
an open claim. Drivers rarely get feedback outside those incidents and near-misses go
unseen, so safety conversations become tied to bad news.


What moves you forward: Connectivity. Cloud-connected cameras, such as Geotab’s
GO Focus Plus
and GO Focus Pro, upload event footage automatically when they detect
risky driving. Your team no longer has to retrieve video by hand, investigations move
faster and managers can talk with drivers about a behavior before it becomes a habit.

Stage 2: Protect


You have evidence when an incident happens. That evidence can protect drivers from
false accusations and your company from fraudulent claims, which is a real
accomplishment.


Defending incidents still takes management time and legal effort, even when the
outcome is in your favor. A program built around the aftermath also does little for the
driver who has never been told they follow too closely.

What moves you forward: Feedback as it happens. Cameras with in-cab voice coaching,
such as GO Focus Plus and GO Focus Pro, speak up when they detect distraction,
fatigue or tailgating. Drivers can self-correct on the spot without waiting for a manager.
When an alert reflects what a driver really did, the driver is more likely to accept the
coaching than dispute it, and managers spend less time building cases.

Stage 3: Prevent


Drivers get coaching close to the behavior, risky events are declining and your team isn’t
buried in false alerts. You’ve also built something many programs struggle with:
coaching that drivers see as fair.


The next challenge is volume. As your fleet or program grows, so does the number of
events. Your team needs to know which events deserve attention today and which
drivers need follow-up.


What moves you forward: Prioritization. Look for software that ranks events by severity,
so the most serious ones reach managers first. It should also show the key moment of
each clip with speed and location, so a manager can judge an event without watching
the full video. Geotab’s video platform does both. It also flags drivers whose driving
patterns point to a higher chance of a collision, so managers can step in before an
incident occurs.

Stage 4: Predict


Your program uses risk insights to step in before habits lead to collisions. The challenge
now is proof. A collision that didn’t happen leaves no incident report or claim, so the
value of that work can be hard to show to finance, leadership and insurance carriers.
What moves you forward: Tracking risk over time. Keep a documented record of how
your fleet’s collision risk has changed. Compare risky driving before and after coaching,
using your fleet’s own history as the baseline. Then watch how driver risk changes from
month to month. Geotab’s safety reporting covers both. Bring that record, along with
coaching completion and total cost of risk, into conversations with leadership and
carriers.

Start with one gap


Most fleets don’t fit neatly into a single stage. You may have strong evidence practices
but an inconsistent coaching routine, or good coaching with no clear way to report
results. Pick the area that held your answers back and work on it first. Explain to drivers

how video supports coaching, give managers a consistent review routine and track a
few measures tied to your safety goals.


See how Geotab’s unified video safety brings video and fleet data together to help your
team move to the next stage.

Why Truckload Rates Feel Disappointing Despite Strong Numbers

This FreightWaves SONAR update dives deep into the current freight market, analyzing peak season performance, truckload rejection rates, and their impact on spot and contract rates. Discover why carriers might feel disappointed despite seemingly strong numbers, and what this means for shippers preparing their routing guides for next year. We also break down the latest trends in diesel prices and their effect on the overall energy market.

Truckload spot rates have pulled back from recent highs to $2.58 per mile — net of fuel — after briefly surpassing $3 per mile earlier this year, according to FreightWaves SONAR data reviewed during the latest SONAR Update. The retreat mirrors a softening in the Truckload Rejection Index, which has plateaued after a strong start to 2025, signaling that relative capacity has loosened slightly against demand.

The rejection index currently sits at 12.78%, a figure that is roughly equal to the peak reached during all of December 2024. While that level reflects a healthy market by historical standards, the deceleration from earlier momentum has tempered optimism. “Is this a strong year or is it a weakening year? I would say we’ve lost some momentum, but things are actually pretty good,” said Craig Fuller.

“If you had told a trucker a year ago that we would be looking at $2.58 a mile, they would have celebrated and absolutely been ecstatic. The fact that we went above $3 a mile — and this is net of fuel, by the way — feels a little bit less exciting.”— Craig Fuller

Fuller framed the psychological dynamic facing carriers: after spot rates crested above $3 per mile, a retreat to $2.58 feels deflating even though the number would have been cause for celebration just 12 months ago. The rejection index, which measures the percentage of truckloads turned down by carriers, remains a key barometer of capacity tightness — a rising rate favors carriers, while a declining rate favors shippers.

The more consequential signal for the industry may be contract rates, which continue to trend upward. With peak season underway, shippers are actively building routing guides and preparing requests for proposals for 2026. Fuller noted that the narrowing spread between spot and contract rates indicates shippers are willing to lock in higher prices to secure capacity. Larger public truckload carriers, including Orca, have already predicted rate increases ahead. “If you don’t pay up, you don’t get to play,” Fuller said.

On the cost side, diesel prices have eased from a national average of $6.50 per gallon to $6.02, providing some relief for carriers. FreightWaves energy reporter John Kingston reported the decline the previous day, attributing it in part to a cooling crack spread — the margin that determines diesel refining profitability — and reduced tensions around the Strait of Hormuz, which has allowed refining capacity to expand.

Fuller suggested that if energy market volatility continues to subside — alongside the fading of tariff-related uncertainty that port executive Gene Soroka had previously flagged — the conditions could set up a stronger freight environment heading into 2027.

  • Truckload spot rates have retreated to $2.58/mile net of fuel after topping $3/mile earlier in 2025
  • The SONAR Truckload Rejection Index stands at 12.78%, near last December’s peak but losing upward momentum
  • Contract rates are still rising and the spot-contract spread is narrowing, signaling shipper willingness to pay up ahead of RFP season

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Port of LA Crushes Records: 5M Containers in 5 Months!

The Port of Los Angeles just had its best five-month stretch in 118 years, moving over 5 million container units. Executive Director Gene Seroka breaks down the surging cargo, the unexpected return of China’s market share post-tariff changes, and the challenges facing American farmers. Seroka calls for more stable trade policies to boost exports and balance the Trans-Pacific supply chain, warning that current policy noise impacts consumers and companies.

The Port of Los Angeles has moved roughly 5 million container units over the past five months, its strongest such stretch in the port’s 118-year history, Executive Director Gene Seroka said in an interview with FreightWaves. October alone topped 1 million containers, the second-busiest month on record. Seroka credited a resilient American consumer and surging factory imports of parts and components, but warned that rail congestion and lopsided trade flows are emerging as near-term constraints.

The cargo surge has been fueled in part by tariff policy clarity. After the Supreme Court’s February decision on Section 112 tariffs — which were applied on a temporary 150-day basis — importers rushed to front-load inventory before the window closed. When Section 301 tariffs were reinstated with more stability, volumes climbed again as shippers gained a clearer view of landed costs for the first time in roughly two years.

China has been the primary beneficiary of that clarity. Seroka said that since the Supreme Court ruling, Chinese cargo volumes have “picked up dramatically” and continue to widen the gap over other Asian export nations. He pointed to structural advantages that are hard to replicate: 40 years of refined supply chains, 13-day transit times from Shanghai to Los Angeles, and more than 100 trains a day departing the LA Basin.

“If you put them on a level playing field with other production factory-based countries, they’re gonna win every single time,” Seroka said.

Record imports are straining the rail network. Seroka said approximately 9,500 containers are currently sitting nine days or longer at the BNSF and Phoenix Marine Terminal footprints, and both operators are working around the clock to clear the backlog. The root cause, he argued, is structural: the port has hit 500,000-TEU import months 11 times — a threshold only one other port has reached once — but export and empty container repositioning has not kept pace, leaving Western railroads scrambling for engine power, crews, and rail cars.

Agricultural exports compound the imbalance. Seroka noted that farm commodities — soybeans, No. 5 red wheat, alfalfa, hay, pistachios, and walnuts — represent the port’s largest single commodity grouping but have been depressed since 2016, when the first China tariffs took effect. Because American farmers export two-thirds of their harvest and domestic consumers use only one-third, lost Chinese demand has pushed buyers toward Brazilian soybeans and Australian almonds, eroding the export backhaul volumes that would otherwise help balance rail utilization.

On the broader trade policy outlook, Seroka noted that the U.S. and Chinese presidents have met four times in the past year, including on the sidelines of APEC in Shenzhen and a planned G20 meeting in Doral, Florida, next month. He called the frequency “unprecedented” but said much more work remains. He pointed to specific cost distortions: 50% tariffs on metals such as steel, aluminum, and copper enabled a handful of domestic producers to raise prices by 48%, spreading costs across importers and consumers. After 23 months, Seroka said the data show more trade with China, a wider trade gap, and more open manufacturing jobs than existed in January 2025 — outcomes he used to argue for longer planning horizons and industry expertise in policy advisory roles. “Our planning horizon has been very short for these past 22, 23 months,” he said. “Mostly we’re reacting to these ebbs and flows.”

  • The Port of LA moved ~5 million containers over the past five months, its busiest such stretch in 118 years, with October ranking as its second-busiest month ever.
  • About 9,500 containers are sitting nine days or longer in the BNSF/Phoenix Marine Terminal rail corridor as record imports outpace export and empty-container repositioning.
  • Seroka says depressed U.S. agricultural exports — down since 2016 — are worsening round-trip rail imbalances and costing American farmers market share to Brazil, Argentina, and Australia.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

AI for Logistics: Why 81% of AI Projects Fail

AI tech promises huge returns for logistics, but many companies are seeing disappointing results. Lean Solutions Group CEO Jack Freker reveals a critical flaw: 81% of firms neglect the organizational transformation needed for AI to truly deliver. Learn which processes need human intelligence, which can be automated, and how a balanced “expert in the loop” approach can drive real efficiency and prevent wasted tech investments.

Most logistics companies are investing in artificial intelligence without doing the organizational groundwork required to make it work, according to new research from Lean Solutions Group and Everest Group. The study, based on interviews with roughly 200 industry leaders, found that while 69% of companies have moved past isolated AI use, only 19% have redesigned their workflows — a gap that is driving widespread underperformance.

The findings matter to carriers, brokers, and third-party logistics providers because the costs of a failed AI implementation are not abstract. Freight brokerage is a 5% margin business, and 30% of respondents in the study reported below-expectation returns on their AI investments, according to Jack Freker, CEO of Lean Solutions Group. Many of those firms lack the internal consulting bench to manage a full transformation, leaving them cycling through three or four technology vendors with little to show for it.

“They’ve applied technology, but they haven’t gone deep into the fit and readiness of the organization — in terms of which are the appropriate functions for AI transformation, which are the tasks that need experts in the loop and humans in the loop to complete the task to gain real benefits here,” said Freker.

“They’ve got to take the step first to redesign, create new processes, and then determine which are the processes that still need humans, still need judgment, still need relationships — which are the processes that are maybe lower value, that are more repeatable, that can be automated in a fairly easy and low-risk manner.” — Jack Freker, CEO, Lean Solutions Group

The study also found that 72% of logistics decisions remain human-led. Freker pointed to accounts payable invoice processing and track-and-trace as areas where automation is already delivering measurable results. In one client example, 71% of invoices are now completed entirely by AI, saving 640 hours that staff have been redeployed to higher-value tasks. In another, a 130-person team is tracking 54,000 loads, while a separate client reduced route-deviation response times by 77% after layering AI onto a team of roughly 50 people monitoring high-value loads — allowing the company to remove 15 to 20 headcount from that function.

Freker drew a clear line around carrier sales and customer sales, calling them areas where AI should augment rather than replace human workers. Because of the relationships and judgment involved, he said, those functions need to be treated more carefully. By contrast, he said emails are now 90% AI-handled for some clients, and functions such as invoice matching, proof-of-delivery, payment collections, appointment scheduling, and quote responses are well-suited to full automation.

Lean Solutions Group, which Freker said has been operating for 14 years and now works across six countries following recent acquisitions, has developed a product called Decision Intelligence — a one-click connection to client systems designed to give individual agents what Freker described as an “Iron Man suit” that handles rote tasks and allows staff to increase the number of customer and carrier contacts made per day. The company positions itself as an expert-in-the-loop alternative for brokers and logistics firms that have tried pure technology plays without success.

  • Only 19% of logistics companies have redesigned workflows for AI, even as 69% have moved past isolated use, per a Lean Solutions Group and Everest Group study of ~200 industry leaders.
  • 30% of AI adopters in the study reported below-expectation returns; one client example showed AI handling 71% of invoices and saving 640 hours of manual labor.
  • Carrier sales and customer sales are flagged as high-risk areas for AI replacement due to the judgment and relationships involved, while track-and-trace and back-office tasks show strong automation results.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

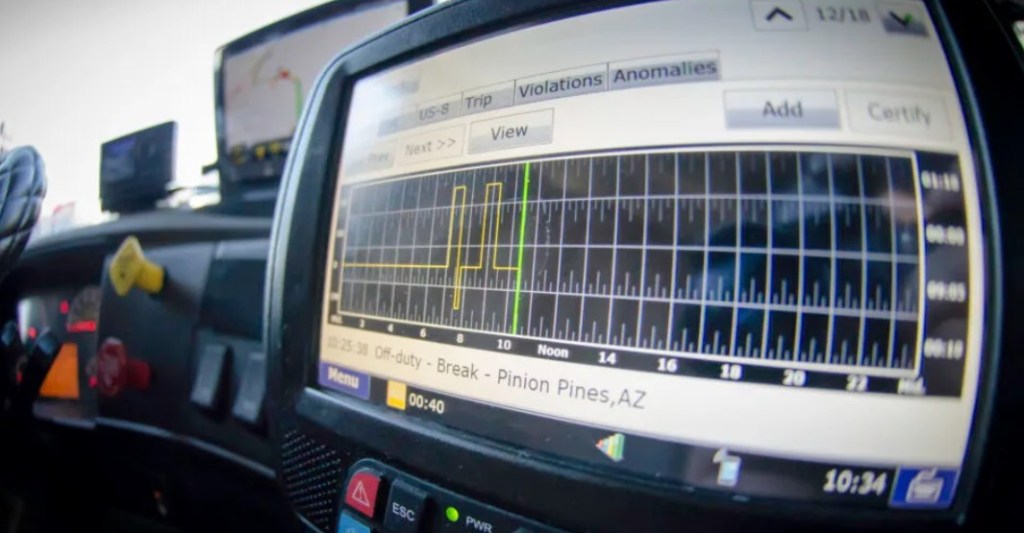
ATA spells out short- and long-term solutions to halt ELD fraud

The American Trucking Association wants the Federal Motor Carrier Safety Administration to go outside in its quest to dramatically slow the use of Electronic Logging Devices (ELDs) in freight fraud.

In a report released earlier this week, the ATA said a certification program for approving ELDs for use in the U.S. should take many of its cues from the current Canadian system.

And the report, put together by an internal task force, said that once that certification program is in place, FMCSA should turn to an outside entity to regularly accredit ELDs for use in the U.S. 

Kevin Grove, ATA’s director of safety and technology policy, said in an interview with FreightWaves that the task force included 25 members from ATA member companies as well as ATA employees.

Grove said the current process to OK an ELD for use is one of self-certification. The requirements for a company to self-certify are provided by FMCSA.

He added that FMCSA “has recently begun scrutinizing those submissions a little more thoroughly than they might have in the past.”

FMCSA has been aggressively paring the ranks of approved ELDs. Last week, it revoked the authorization of 133 ELDs. 

Far surpassing Biden pace

A downloadable Excel file provided by FMCSA on revoked ELDs shows almost 300 revocations since the Trump administration took office. The four years of the Biden administration had less than 200 revocations.

The question the ATA report seeks to answer is what occurs next after the flurry of revocations by the Trump officials running FMCSA runs it course and then how to build a sustainable system that lasts beyond the aggressive approach of the current administration.

As the ATA report says in its introduction, the goal of the task force was to provide “a comprehensive set of policies and actions that will restore trust in the ELD ecosystem in the short term and maintain trust in the ELD system and federal databases of ELD providers over the long term.”

The suggestion of turning to Canada comes after the ATA recommends that FMCSA should “build upon existing certification mechanisms rather than create an entirely new model from the ground up.”

And the existing mechanism it favors is the Great North.

Look to Canada, build a U.S. system

“The Canadian ELD certification framework provides a useful structural model for how independent technical expertise can be incorporated into an effective certification regime,” the ATA says. But the working group at ATA also recommends FMCSA set up its own system, “tailored to the U.S. regulatory environment and administered separately from the Canadian system.”  

There is enough in the Canadian system that the ATA working group found attractive that it also says FMCSA, “whenever possible,” should seek to “maintain alignment between the two programs, particularly with respect to technical requirements and testing approaches.”

The structure ATA suggested for third-party certification begins with FMCSA funding “development of an accreditation program to support a third-party ELD certification framework.”

“Under this approach, FMCSA would retain responsibility for establishing and maintaining the technical requirements, resolving questions of regulatory interpretation, and conducting investigation and enforcement activities, while qualified third-party organization(s) would administer accreditation and certification,” the ATA said in its report.

That structure, it said, would allow the agency to keep its focus on its regulatory activities while “leveraging outside technical expertise.”

Already has some input

FMCSA did have an advanced notice of proposed rulemaking (ANPRM) in 2022 on possible revisions to ELD regulations. But that did not result in any policy shifts, though the ANPRM did attract 1,377 comments. 

Although nothing came out of it, the ATA working group said the comments and other recommendations in the 2022 ANPRM could be used as a “foundation” for the next step in revising the regulatory framework for ELD governance. 

The ANPRM could then morph into the more formal Notice of Proposed Rulemaking (NPRM), the ATA said. FMCSA “should…use the NPRM to gauge interest among prospective accreditation and certification providers and better understand their capacity and requirements for participating in the program,” ATA said.

The ATA’s report avoids a hard timeline. During the NPRM, ATA said, FMCSA can be working concurrently to “establish an appropriate compliance timeline in the final rule that provides sufficient time to stand up the accreditation and certification system and certify existing ELDs before the new requirements take effect.”

The report also stresses that certification “is not a one-time event. It must be maintained through the lifecycle of the devices.”

In the short term, the ATA said, “FMCSA should take a short-term approach that does not require rulemaking to address current known methods of fraud in the existing system.” The long-term solution would follow, it said.

Any solution, according to ATA, should be directed at having the ELD become an ally in fighting fraud, rather than a tool that can be utilized by scammers.

One way to do that: more touch points. “FMCSA’s long-term actions should create more touch points for devices and suppliers,” the report said. “No single touch point would catch all fraud, but, cumulatively, their breadth and frequency would increase the overall chances of detection and reduce the window in which they could operate before being detected.”

One of the short-term solutions the association recommends is to use electronic records of duty status (ERODS) for various giveaways that suggest fraud might be underway.

Telltale data in a fraudulent EROD, the ATA said, could include “out-of-sequence file numbers, impossible distances, and driver info manipulation.”

One way it’s done

As an example of the type of fraud that would use an ELD to get its task done, Grove said he has heard reports of a driver, reaching the Hours of Service limit, would be instructed to call a phone number. 

“They can call the number, and then through wireless communication, they’re able to upload new logs to the device that essentially shows the driver has more hours of service available,” Grove said.

An inspection of the records might look “immaculate,” Grove said. But a further inspection of such other data like fuel receipts and bills of lading can tell a very different story.

More articles by John Kingston

Amazon-focused bill likely to pass in NYC but only after changes

Amazon workers’ union gets a contract, but it’s in Canada

SCOTUS action revives shipper/receiver liability post-Montgomery

Trucking Spot Rates Defy Fuel Costs: An Unexpected Market Move

Spot rates are climbing, defying falling fuel prices. Dive deep into the National Truckload Index (NTI) data with FreightWaves to understand this unusual market divergence. We’ll explore the real drivers behind rising spot rates and what it means for holiday shipping and your supply chain strategy.

Dry van spot rates jumped to their highest level since July in early November, even as diesel prices declined — a divergence that points to capacity constraints and a late-season inventory surge rather than fuel cost pass-throughs. The National Truckload Index, which measures all-in dry van spot rate movement across the United States, rose more than 4% since late October while diesel truck stop prices fell roughly 3.5% over the same period.

The timing is notable. Julie Van de Kamp, reporting on the data as of Tuesday, November 17th, said the early-November move is unusual. “It’s rare that the NTI starts jumping this early in November ahead of the holidays,” she said, underscoring that the market is behaving differently than seasonal norms would suggest.

The disconnect between fuel and spot rates is a key theme. Diesel has not seen a sharp increase since early September, yet spot rates have continued to climb throughout that stretch. Van de Kamp was direct about the relationship: spot rates are primarily a function of available capacity and supply and demand, not a straight pass-through of fuel costs — and the current data reinforces that view.

“Carriers can’t always pass those fuel costs along unless the market bears it. And so we’ve also seen in prior cycles when fuel rates or costs have risen and spot rates have fallen, and we’re seeing the opposite right here.”— Julie Van de Kamp

A last-minute inventory push by retailers appears to be a significant driver. Van de Kamp pointed to the October Logistics Manager Index reading of 66.9 for inventory level growth — the highest reading since 2022 — discussed by Zach Strickland and Dr. Zach Rogers on Freightonomics. Many retailers delayed bringing holiday inventory into the country, a byproduct of demand uncertainty, rising inventory holding costs, and more streamlined supply chains. That compressed ordering window is now pushing freight outside of contracted agreements and into the spot market, adding upward pressure on rates.

The spot market itself represents only a fraction of overall truckload volume — roughly 10% to 25% of truckload freight depending on market conditions — with the remainder moving under contract. That means even a modest surge of freight spilling out of contracted agreements can move spot rates meaningfully.

National dry van tender rejection rates have been trending lower since July but remain between 10% and 15%, a range Van de Kamp describes as still capacity-constrained. Rejection rates above 10% are considered a sign of a tight market, and the current level gives carriers some ability to select freight that fits their networks without the extreme readings seen over the summer. The truckload market, she said, is “still really not fully recovered” and remains in what she characterized as an unhealthy state — but one where carriers retain meaningful optionality heading into the holiday stretch.

  • The NTI rose more than 4% since late October while diesel prices fell 3.5% over the same period, decoupling spot rates from fuel costs.
  • A record-high October Logistics Manager Index inventory reading of 66.9 — the highest since 2022 — points to a last-minute retailer inventory surge driving freight onto the spot market.
  • Dry van tender rejection rates remain between 10% and 15%, signaling a capacity-constrained market that still gives carriers some freight selectivity.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Rail Freight Fraud: Organized Crime’s New Tactic?

FreightWaves Today dives into shocking reports of cargo theft on California trains, where organized criminals are targeting slow-moving rail cars. Bill Stephens from Trains Magazine and Jean Savage, CEO of Trinity Industries, discuss the implications for the rail industry, market cycles, and the outlook for railcar demand and pricing. Discover how these incidents affect the broader supply chain and what to expect in the coming years.

The railcar market is tightening faster than many shippers and carriers anticipated, with new builds running roughly 15,000 units below annual scrappage and lease rates climbing — a dynamic that Trinity Industries CEO Bill Stephens says will intensify through 2027. With 17.5% of the North American fleet now parked — the lowest storage level since 2022 — the gap between available cars and demand is narrowing quickly.

Stephens said the industry is on pace to deliver just under 25,000 new railcars in 2024, the bottom of a prolonged down cycle, while scrapping roughly 40,000 cars. That 15,000-unit annual deficit has been compressing supply for 17 consecutive months. For the leasing segment, which Stephens described as the larger part of Trinity’s business, utilization is high and rates are moving up. New car manufacturing, by contrast, remains depressed.

Looking ahead, Stephens said Trinity’s third-quarter earnings call showed a greater than 1x book-to-bill ratio and a roughly 40% increase in new car orders for 2027 delivery. He now expects 2025 builds to reach 30,000 to 35,000 units — a meaningful step up, but one he cautioned will strain suppliers. Steel producers have already doubled their lead times and are still missing those extended windows by two to four weeks, he noted, and valve manufacturers for tank cars are struggling to keep pace even at current low production levels.

“For our customers, what we’re encouraging them to do is stop delaying because there are going to be some headwinds,” Stephens said. “We think getting to 30,000 to 35,000 new railcar builds next year is going to take the supply chain actually stretching and pushing hard to get there.”

Steel prices are also adding to cost pressure. Stephens said prices were up 63% year over year at the end of the third quarter and have risen an additional 5% to 6% since then. Because the cost of a new car sets an effective ceiling on what lessors can charge for existing equipment, rising input costs are reinforcing lease rate gains across the fleet. Trinity reported an 89% lease renewal rate last quarter, even as rates climbed.

On the demand side, the strongest order activity is coming from grain, metals and metallic ores, and petroleum segments — categories Stephens said are driven largely by replacement needs rather than new traffic growth. He downplayed the AI infrastructure buildout as a material near-term driver of rail cargo, saying its contribution through construction materials and metals is “small.” He attributed petroleum strength instead to war-related energy market disruptions, adding that overseas equipment damage means the market will stay elevated into at least 2028.

Cargo theft along rail corridors also drew attention during the discussion. Trains magazine contributor Bill Stevens described organized criminals targeting slow-moving trains through Tehachapi Pass in Southern California — a key corridor linking Southern California to the Bay Area and Pacific Northwest — by hopping aboard, cutting air hoses to stop trains, and throwing consumer goods overboard. “Clearly, they know what they’re looking for and what containers they want to hit,” Stevens said. Stephens and host Jean Savage both called for passage of CORCA, federal legislation aimed at coordinating law enforcement response to cargo theft, noting bipartisan support in Congress has not yet translated into enactment.

  • Trinity Industries expects 2025 new railcar builds of 30,000–35,000 units, up from roughly 25,000 in 2024, as annual scrappage of ~40,000 cars tightens the fleet.
  • Steel prices rose 63% year over year through Q3 and have climbed an additional 5–6% since, pushing new car costs higher and supporting lease rates on existing fleets.
  • Organized criminals are targeting slow-moving trains through California’s Tehachapi Pass, cutting air hoses to stop trains and stealing consumer goods; advocates are pressing Congress to pass the CORCA cargo-theft legislation.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Trucking Economy in 2024: A K-Shape Threatens Consumer Demand

The trucking economy is navigating a unique ‘K-shaped’ recovery, with industrial strength diverging from struggling consumer demand. Bloomberg Intelligence analyst Lee Klaskow unpacks why this trend, coupled with tight capacity, could lead to a prolonged, less volatile rate cycle extending into 2027. We discuss the unexpected tailwinds from AI and data centers, the impact of federal mandates on driver capacity, and what it all means for freight demand and brokerage consolidation.

Truckload contract rates could climb into the high single digits in 2025 — and touch low double digits if consumer demand holds — according to Lee Klaskow, senior analyst for transportation and logistics at Bloomberg Intelligence. The forecast hinges not on a surge in freight volumes but on a structural tightening of truck supply that Klaskow expects to sustain rate momentum through at least 2027.

“We think that we can get on the contractual side, you know, on average rates at the high single digits to low double-digit level in terms of growth on top of what we’ve had this year in 2026, which has been pretty robust growth as well,” said Klaskow. The analyst added that drivers pushed out of the market by federal mandates are unlikely to return as quickly as in prior cycles, reducing the capacity whipsaw that has historically cut rate rallies short.

The key risk to that outlook is the consumer. Klaskow pointed to a K-shaped economy in which higher fuel and food costs are squeezing lower-income households even as upper-income consumers remain largely insulated. That divergence could dampen freight volumes even while nominal spending holds up.

“If you’re spending more money at the pump and more money at the grocery store, you’re spending less money on stuff. And everyone on this broadcast cares about the delivery and the movement of stuff,” Klaskow said.

On the industrial side, Klaskow cited several positive signals: the ISM manufacturing index has been in expansion territory every month this year, and the AI and data center construction boom has been a notable tailwind for the flatbed market. He cautioned, however, that uncertainty around U.S. trade policy is slowing cross-border investment, particularly in Mexico, as companies wait for clarity on tariffs before committing capital.

Klaskow also weighed in on brokerage consolidation, arguing that the Supreme Court’s Montgomery ruling will accelerate mergers by forcing brokers to build the scale needed to absorb rising insurance costs and legal liability. He said synergies from the RXO and C.H. Robinson transaction — which he described as the largest deal in freight brokerage history — could exceed the $300 million target the companies have outlined. Larger, well-capitalized brokers will increasingly direct freight toward carriers with rigorous driver-vetting processes, he said, favoring publicly traded fleets over small owner-operators.

Looking further out, Klaskow stopped short of calling the current environment a supercycle but said the industry should expect longer, more stable rate cycles rather than the sharp 18-month spikes and collapses of the past. That stability, he argued, benefits shippers as well as carriers by making capacity more reliable and giving fleets the margin to reinvest in their businesses rather than cut corners on safety.

  • Lee Klaskow forecasts high single-digit to low double-digit truckload contract rate growth in 2025-2026, driven by structural capacity constraints rather than demand strength.
  • A K-shaped economy poses the chief downside risk, with lower-income consumers spending more on fuel and food and less on goods that move by truck.
  • The Montgomery Supreme Court ruling is expected to accelerate freight brokerage consolidation; RXO/C.H. Robinson synergies could surpass the $300 million target, Klaskow said.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.

Diesel: Are Sky-High Prices Finally Over?

Diesel prices are seeing a significant drop, with benchmark fuel falling below the $6 mark. FreightWaves’ John Kingston breaks down the latest oil market data, including a surprising 19-cent decline this week and new forecasts predicting a crude surplus for 2026. Despite ongoing geopolitical tensions, the market is showing unexpected stability in food prices. Kingston explains what’s driving these changes and whether the current stability in energy costs is sustainable.

The U.S. Department of Energy’s Energy Information Administration reported a $0.19 drop in diesel prices in its latest weekly release, pushing the national average to $5.937 per gallon — the third-largest single-week decline since the war began. The AAA price fell below $6 per gallon, and futures markets saw a significant sell-off, signaling that the market may be easing from its recent highs.

The price relief is being driven in large part by crude flows through the Strait of Hormuz recovering to roughly 16 to 17 million barrels per day, compared with approximately 20 million barrels per day before the war started. The International Energy Agency’s latest monthly report projected a large crude surplus for 2026, a forecast nearly identical to what the agency issued a year ago before the conflict disrupted markets.

“I don’t know that diesel’s out of the woods. It looks to me like crude might be out of the woods. I still — we still have a lot of inventories that need to be refilled. And the only reason we’re getting all this oil out is because we’re escorting so many tankers. And how long can you keep doing that? That’s not a long-term solution,” said Kingston.

On the refining side, Argus Media reported a significant wave of deferred fall maintenance at U.S. refineries. Facilities that would normally bring in 100 to 150 outside contractors for weeks-long turnarounds postponed those shutdowns because refining margins were too lucrative to pass up. That deferred work could crimp refined product output later. Meanwhile, gasoline margins are currently weak due in part to Renewable Fuel Standard economics, which could lead refiners to either cut back throughput or shift production further toward diesel — adding another variable to diesel supply.

Despite the spike in energy costs this year, fears of broad food-price hyperinflation have not materialized. Bloomberg’s Javier Blas noted that nine months into the war, the U.S. wheat price is actually lower than it was in late February, corn and soybeans are little changed, and urea fertilizer costs 10% less than pre-war levels. John Kingston noted that while beef inflation has been visible, it stems from factors predating the conflict by years.

On the crude price ceiling, the IEA’s surplus forecast likely takes the prospect of $110-per-barrel crude off the table — a level that represented roughly the peak reached during the most acute phase of the conflict. Crude currently sits in the $90 to $95 range. Jeff Currie, former head of commodity research at Goldman Sachs, argued in a recent CNBC interview that the market is in a holding pattern: well-supplied enough to prevent a return to recent highs, but still carrying enough of a geopolitical risk premium to make a drop to $70 unlikely in the near term.

Analysts also flagged the longer-term cost of maintaining military escorts through the Persian Gulf as an underappreciated risk. As Kingston puts it, “If our military’s gonna be stuck in the Persian Gulf for who knows how long, making sure that the supplies get out — what other things are they not doing?” With diesel inventories still below normal levels and refinery maintenance backlogs building, carriers and shippers should not expect a swift return to pre-war fuel economics.

  • Diesel fell $0.19 in one week to $5.937/gallon — the third-largest single-week drop since the war began.
  • Crude flows through the Strait of Hormuz have recovered to 16–17 million barrels/day, down from ~20 million pre-war, with military escorts enabling much of the movement.
  • Deferred refinery maintenance and weak gasoline margins could tighten diesel supply and sustain a risk premium even as crude prices ease.

This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above.